
Call Charles Book a meeting
Mortgage Broker Turrella

Links Property Finance · Home loans in Turrella and across Sydney: Mortgage Broker in Turrella

Turrella is a small suburb of fewer than a thousand homes, split between houses and apartments, with a young median age.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Getting pre-approved to buy in Turrella: how long does it last?

Usually three to six months, often around 90 days, and it can be refreshed with updated documents. It is conditional: a new debt, a job change or a lower valuation can change it before formal approval, so keep your finances steady until settlement.

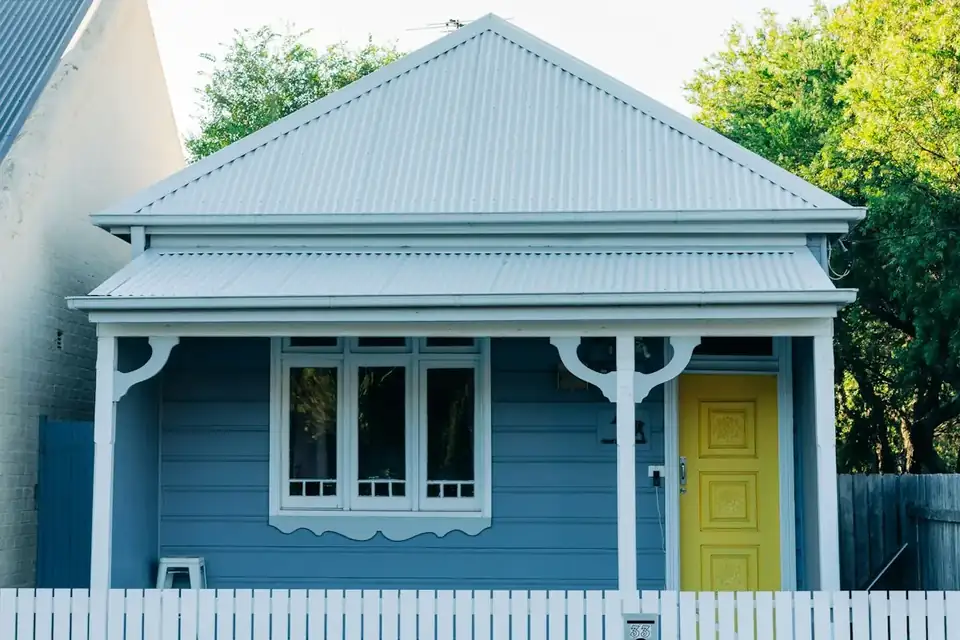
A blue weatherboard cottage
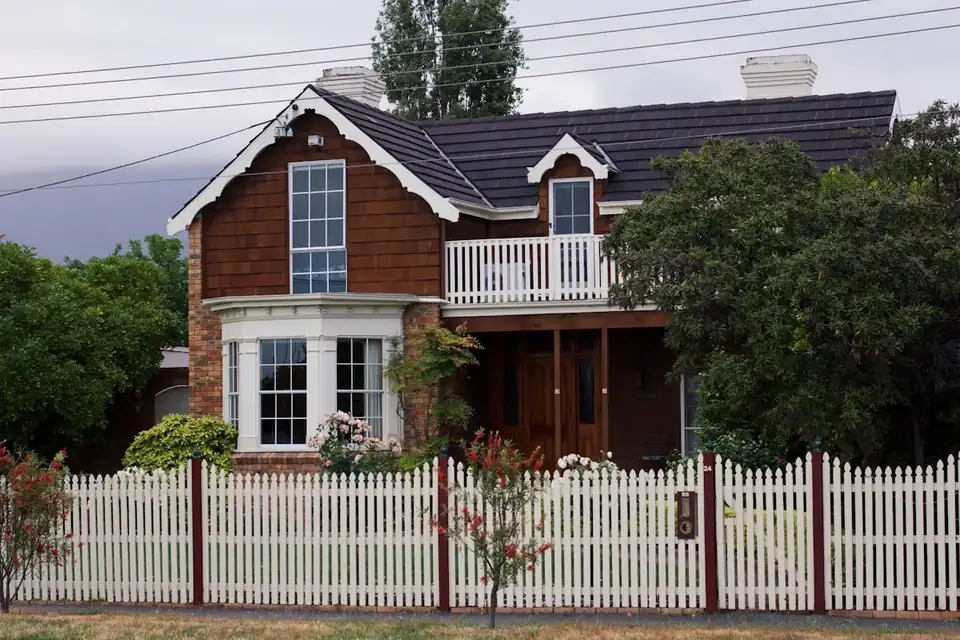
In Turrella, houses make up 46.9% of homes, terraces and semis 8.0% and apartments 44.8% (ABS Census 2021).

Turrella by its homes

Apartments are just over four in ten homes here (44.8%, against 21.7% statewide). Small studios and older blocks with thin sinking funds narrow the lender list, which is worth knowing before you bid. With only 978 dwellings, Turrella sees few sales in any year, and valuers sometimes reach into neighbouring suburbs for evidence.

  • Postcode2205
  • CouncilBayside Council
  • From the Sydney CBD10 km south west
44.8%

apartments NSW 21.7%

46.9%

separate houses NSW 65.6%

8.0%

terraces and semis NSW 11.7%

43.0%

rented NSW 32.6%

30.5%

with a mortgage NSW 32.5%

978

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL14000).

A row of red-brick terraces

Stamp duty on a Turrella purchase

NSW first home buyer stamp duty

NSW first home buyer stamp duty

$750,000
Transfer (stamp) duty$0Exempt under the First Home Buyers Assistance Scheme, saving $27,937

Assumes an eligible NSW first home buyer purchasing an existing home under the First Home Buyers Assistance Scheme (exempt to $800k, concession to $1m). Indicative only, check Revenue NSW for your exact position.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles at Links Property Finance made buying our first home so much easier than we expected. As first home buyers, we had a lot of questions around borrowing capacity, our deposit and the different government schemes available to us. Charles explained everything clearly, compared different lenders and kept us updated throughout the whole process. He was always easy to reach and made sure we understood what was happening from pre approval right through to getting our home loan approved. We would definitely recommend Links Property Finance to anyone looking for a mortgage broker, especially first home buyers who want someone to guide them through the process.
Michael Google review
★★★★★
Charles looked after us really well and his knowledge gave us the confidence to purchase our property. He wasn’t pushy and always ensured we felt comfortable with the repayments.
Sandra Google review
★★★★★
Had a really good experience with Charles at Links Property Finance. He was easy to deal with, always quick to respond and kept everything simple and clear throughout the whole process. You can tell he genuinely cares about getting the best outcome for his clients rather than just getting things done quickly. Really happy with the experience and would happily recommend Charles and Links Property Finance to anyone.
Christian Google review

Pre-approval in Turrella

Pre-approval is a lender’s conditional indication of how much it is prepared to lend, based on your income, expenses, debts and credit file.

It usually lasts around three to six months, depending on the lender. It is not a guarantee: formal approval still depends on the lender valuing the property and confirming nothing material has changed.

Things that can undo a pre-approval include a new debt or credit card, a change of job, a drop in income, missed payments, or a property the lender will not accept.

Keeping your finances steady between pre-approval and settlement is the simplest way to protect it. How pre-approval works in detail

A terrace with an iron-lace balcony

Young buyers in Turrella

A couple carrying a box into their new home
  • Links Property Finance is based in Enfield, about fifteen minutes from Turrella, with conversations by phone, video or in person.The first one is about your budget and the kind of home you want.
  • Turrella’s homes are split between houses and apartments, and its median age is in the early thirties.Many buyers here are looking for a first place close to the city.

Keeping pre-approval valid

A first home buyer working through their numbers at the kitchen table
  • No new debts.Avoid new credit cards, car loans and buy now pay later accounts.
  • No surprises.Tell your broker before changing jobs or making large purchases.

Wolli Creek, the station and Turrella housing

Turrella lies about ten kilometres south-west of the city on the southern bank of Wolli Creek, in the Bayside Council area. It is mostly residential, with light industrial buildings around Turrella railway station and north along the line.

It borders the Wolli Creek Valley bushland, and community campaigns helped see the motorway built in a tunnel beneath the valley. Its heritage places include the house Cairnsfoot in Loftus Street and the Wolli Creek Aqueduct in Thompson Street.

  • In 1842 William and Eleanor Favell farmed a property named Hillside here, beside the orchards and gardens of the Curtis and Blackwell families.
  • When a Turrella buyer is getting pre-approved, Links compares a panel that includes ING, Resimac, Macquarie, ANZ and Westpac.
Read the full detail

In 1842 William and Eleanor Favell farmed a property named Hillside here, beside the orchards and gardens of the Curtis and Blackwell families. The farms were subdivided when the railway came, and the station opened in 1931.

Light industry grew near the line, including a well-known ice cream factory that has since closed. The post office opened as West Arncliffe in 1933 and took the name Turrella in 1952. Today homes are split between houses and apartments.

When a Turrella buyer is getting pre-approved, Links compares a panel that includes ING, Resimac, Macquarie, ANZ and Westpac.

Example scenario (illustrative, not a real client): a Turrella renter gets pre-approval and starts looking, but four months pass without finding the right apartment.

Before the pre-approval lapses, they update their payslips and statements, avoid any new credit in the meantime, and renew the pre-approval so they can keep making offers with confidence.

What does pre-approval check?

For pre-approval, the lender reviews your income, expenses, debts and credit file, and sometimes your deposit. Some lenders do a full assessment at this stage, while others do a lighter one and check everything again later.

A full assessment up front makes the formal approval more reliable. Pre-approval checklist.

A cottage behind a picket fence

When does it expire?

If your search takes longer than the pre-approval period, you can usually renew it with updated documents. The lender may reassess, and policies or rates may have changed.

Renewing before it expires avoids a gap when you find the right home. How pre-approval works.

Credit checks and your file

Applying for pre-approval usually involves a credit enquiry, which appears on your file. Several applications in a short time can look like financial stress.

One well-prepared application to a suitable lender is better than several at once. Check your loan ready score.

Pre-approval, formal approval or unconditional?

Three stages of approval, and what each means.

  • Pre-approval. A conditional indication of what the lender will lend. Usually lasts around three to six months.
  • Formal approval. Issued once the lender has valued the property. May still carry conditions.
  • Unconditional. All conditions met. The loan is ready to settle.

While you are pre-approved

The habits that keep approval on track.

  • No new creditCards, car loans or buy now pay later.
  • Steady employmentTalk to your broker before changing jobs.
  • Bills paid on timeEvery account up to date.
  • Your depositKept in place, not spent.
  • The expiry dateDiarised, with time to renew.
  • Property checksSize, type and title that lenders accept.

Common questions about pre-approval in Turrella

What is pre-approval?

A lender’s conditional indication of how much it will lend you, based on your finances. It is not a guarantee, because the lender still has to value the property and confirm your details.

How long does pre-approval last?

Usually around three to six months, depending on the lender. You can often renew it with updated documents.

Can a pre-approval be withdrawn?

Yes. A new debt, a job change, a drop in income or missed payments can all lead the lender to reconsider.

Does pre-approval affect my credit score?

Yes, slightly: it usually involves a credit enquiry, which appears on your file. One application is fine; several in a short time can raise concerns.

Do I need pre-approval to make an offer?

Not legally, but it gives you a realistic budget and speeds up formal approval, which matters at auction and during a cooling-off period.

Can I change jobs while pre-approved?

It is best to talk to your broker first. Some changes, such as moving to a similar role, may be fine, while others can require reassessment.

Talk to a broker about your Turrella home loan

Bring your Turrella plans to a free 30-minute call: your borrowing range, the lenders that fit the property and your next step.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.