Links Property Finance · Home loans in Belmore and across Sydney: Mortgage Broker in Belmore
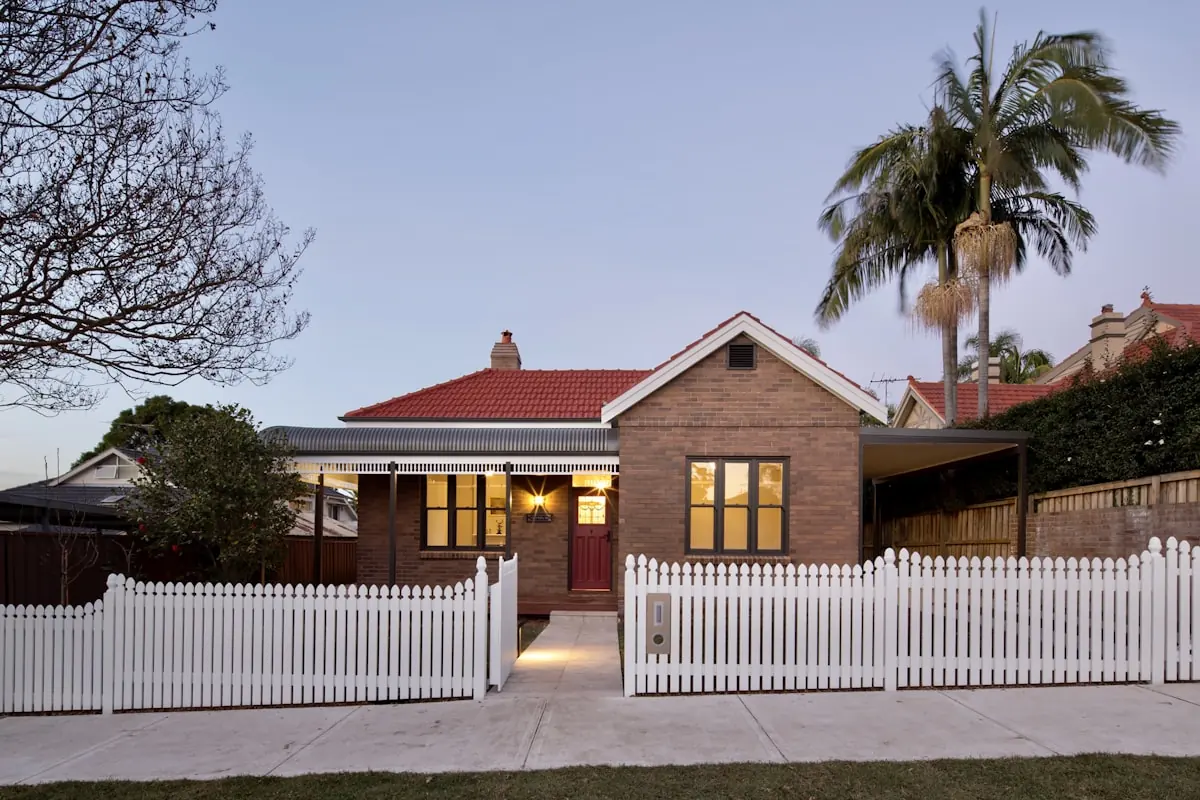
Belmore’s homes are split almost evenly between houses and apartments, with period family homes on the side streets and newer units along Canterbury Road.
Buying in Belmore with a sibling or friend: how do you share the loan and the title?
Buying with a sibling or friend usually means one loan, joint and several, so each of you is liable for all of it, and a title held as tenants in common with shares that match what each put in.
Read more
A written co-ownership agreement should cover who pays what and what happens when someone wants out, before you exchange.
In Belmore, houses make up 43.8% of homes, terraces and semis 9.5% and apartments 46.1% (ABS Census 2021).
What Belmore is built of
With 46.1% of dwellings in apartment buildings, strata is a big part of buying in Belmore. Lenders measure internal living area, not the advertised size, so check the floor plan on the contract before the bank does.
Postcode2192
CouncilCity of Canterbury-Bankstown
From the Sydney CBD11 km south west
Belmore
NSW
Separate housesTownhouses and semisApartments
46.1%
apartments NSW 21.7%
43.8%
separate houses NSW 65.6%
9.5%
terraces and semis NSW 11.7%
43.0%
rented NSW 32.6%
26.4%
with a mortgage NSW 32.5%
5,611
private dwellings
Source: ABS Census 2021, Suburbs and Localities (SAL10279).
What stamp duty would you pay in Belmore?
NSW first home buyer stamp duty
NSW first home buyer stamp duty
Transfer (stamp) duty$0Exempt under the First Home Buyers Assistance Scheme, saving $27,937
$750k
$800k$1m
No dutyConcessionFull duty
Full duty, no concession$27,937
You pay$0
Assumes an eligible NSW first home buyer purchasing an existing home under the First Home Buyers Assistance Scheme (exempt to $800k, concession to $1m). Indicative only, check Revenue NSW for your exact position.
Had a really good experience with Charles at Links Property Finance. He was easy to deal with, always quick to respond and kept everything simple and clear throughout the whole process. You can tell he genuinely cares about getting the best outcome for his clients rather than just getting things done quickly. Really happy with the experience and would happily recommend Charles and Links Property Finance to anyone.
Had a great experience with Charles at Links Property Finance. He made the whole home loan process straightforward and easy to understand, kept me updated throughout and was always quick to answer any questions.
When two people who are not a couple buy together, the lender assesses both incomes, both sets of expenses and both credit files, and both of you usually sign for the whole loan.
That means each of you is responsible for the full debt, not just your share, if the other stops paying. Our guide to buying a house with friends or family covers the agreement to put in place.
Ownership can be split on the title in agreed shares as tenants in common, which suits unequal deposits, or held equally as joint tenants.
A written co-ownership agreement covering contributions, costs and what happens if one person wants to sell is worth arranging with a solicitor before you buy. Buying with someone else in detail
Charles Touma, Mortgage Broker.
Period homes and co-buyers in Belmore
Links Property Finance is based in Enfield, a short drive from Belmore, with conversations by phone, video or in person.The first one can include both of you, so everyone hears the same thing.
Belmore’s homes are split almost evenly between houses and apartments.That gives co-buyers a choice between a shared first apartment and pooling for a house.
What do lenders assess for co-buyers?
Both of you, together.Both incomes, both sets of expenses and both credit files are part of one application.
One loan, shared liability.Each borrower is usually responsible for the whole loan, whatever the ownership shares on the title.
Burwood Road, art deco shopfronts and Belmore housing
Belmore lies about eleven kilometres south-west of the city in the City of Canterbury-Bankstown. Its main commercial area runs along Burwood Road, where art deco shop façades line the small shopping strip, and commercial and industrial buildings sit along Canterbury Road.
It is a predominantly low-rise suburb of period family homes with large backyards and wide tree-lined streets, with a growing number of apartments along Canterbury Road.
The suburb is named after the fourth Earl of Belmore, Governor of New South Wales from 1868 to 1872, and the area was known as Darkwater in its early days.
When co-buyers in Belmore are comparing loans, Links compares a panel that includes Westpac, Resimac, ING, ANZ and Macquarie.
Read the full detail
The suburb is named after the fourth Earl of Belmore, Governor of New South Wales from 1868 to 1872, and the area was known as Darkwater in its early days.
First land grants date from 1810, and the land was used for market gardens and orchards before subdivision in the 1890s. Its heritage-listed places include Federation and inter-war houses in Isabel Street and Wilson Avenue, and a row of Californian bungalows in Lakemba Street.
When co-buyers in Belmore are comparing loans, Links compares a panel that includes Westpac, Resimac, ING, ANZ and Macquarie.
Example scenario (illustrative, not a real client): two sisters, one with a larger deposit than the other, want to buy a Belmore apartment together.
Before applying, they agree to own it as tenants in common in shares matching their deposits, have a solicitor draw up a co-ownership agreement covering a future sale or buyout, and apply for one loan together.
Tenants in common or joint tenants
As tenants in common, each owner holds a defined share, which can be unequal, and each share can pass under that person’s will. As joint tenants, both own the whole property equally, and if one dies it passes to the other.
Siblings and friends often choose tenants in common so the title reflects what each person put in. Your solicitor or conveyancer can explain which suits your situation. Buying with someone else.
The 5% Deposit Scheme for two buyers
The 5% Deposit Scheme can accept two eligible joint applicants who are not a couple, such as siblings or friends, provided both meet the criteria. Each applicant must be eligible in their own right, including as a first home buyer where that applies.
The scheme rules change from time to time, so it is worth checking the current criteria before relying on it. First home buyer schemes in NSW.
When does one person want out?
Plans change. One co-owner may want to sell, move in with a partner or buy elsewhere. The usual options are selling the property, or one owner refinancing into their own name and paying the other out.
A buyout refinance is assessed on the remaining owner’s income alone, so it helps to think about that possibility at the start. Refinancing explained.
Sibling, friend or parent?
Three kinds of co-buyer, and what each means for the loan.
Sibling. Both borrowers, both on the title, often as tenants in common. Each is responsible for the whole loan.
Friend. The same as a sibling from the lender’s view. An agreement about exits matters even more.
Parent. Can co-own and co-borrow, or guarantee without owning. A guarantee is often simpler for everyone.
What should I check before co-buying in Belmore?
The conversations to have before you sign anything.
Who puts in whatEach person’s deposit and share of costs.
Ownership sharesTenants in common or joint tenants.
A written agreementCovering sales, buyouts and disputes.
Both credit filesAny issue on either file affects the application.
Ongoing costsHow rates, strata and repairs will be shared.
WillsHow each share would pass if one of you died.
Common questions about co-buying in Belmore
Can I buy a home with my brother, sister or a friend?
Yes. Lenders assess both of you together, and you both usually sign for the loan. You can own the property in equal or unequal shares, depending on how you set up the title.
Am I responsible for all of the loan or just my share?
Usually all of it. Borrowers on a joint loan are generally each liable for the full debt, whatever the ownership shares on the title, so if one person stops paying, the lender can look to the other.
What is the difference between tenants in common and joint tenants?
Tenants in common hold defined shares, which can be unequal and can pass under each person’s will. Joint tenants own the whole property equally, and it passes to the survivor if one dies.
Can we use the 5% Deposit Scheme as siblings or friends?
Yes: the scheme accepts two eligible joint applicants who are not a couple, such as siblings or friends, if both meet the criteria. Check the current scheme rules, as they change from time to time.
Do we need a co-ownership agreement?
It is not required by lenders, but it is strongly worth having. It sets out contributions, how costs are shared and what happens if one of you wants to sell or be bought out.
What happens if one of us wants to sell?
You can sell and divide the proceeds, or one of you can refinance into their own name and pay the other out. The refinance is assessed on that person’s income alone.
Talk to a broker about your Belmore home loan
Thirty minutes with Charles: what you could borrow, which lenders suit Belmore property and what to do next. Free, with no credit check.
Reviewed by Charles ToumaDirector & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.
General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.