


Call Charles Book a meeting
Property types

Links Property Finance · Construction loan mortgage broker, Sydney: Heritage and Period Home Loans

A heritage listing or a conservation area does not stop a home loan. It changes the valuation conversation: condition, renovation limits and the cost of doing things properly all feed into what a lender will lend against a terrace, a Federation house or a worker’s cottage.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Heritage or period home? What does the listing mean for the loan?

Usually not much for the loan itself. Lenders finance heritage and period homes every week; the listing or conservation area mostly limits what you can change later.

Read more

The valuation is where it shows: condition, renovation limits and the cost of doing work properly all feed into what the lender will lend against.

Part of the construction loans guide.

A couple sitting among moving boxes

Recent Links clients

  • Three Links Property Finance clients in front of the agent’s board at the home they bought Family buy · South West Sydney
    Bought, and all smiles. A family purchase in Sydney’s south-west.
  • A family in front of the sold sign at the home they bought together Family buy · Inner West
    The whole family turned up. A parents’ guarantee, done properly.
  • Next one

    The next sold sign could be yours.

    A free 30-minute call shows where you stand.

    Book my free call
Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Highly recommend Charles! Professional, knowledgeable and very easy to work with. He helped us navigate the home loan process and found a great solution that suited our needs. Excellent service from start to finish.
Daniel Google review
★★★★★
Charles is an absolute star at what he does. He was straight-up, highly professional, and worked hard to secure a fantastic rate for our home loan. Communication was prompt and clear the entire way through. I would trust him with any future financial needs
Alan Google review
★★★★★
Charles looked after us really well and his knowledge gave us the confidence to purchase our property. He wasn’t pushy and always ensured we felt comfortable with the repayments.
Sandra Google review

Listing, conservation area, or just old: which applies?

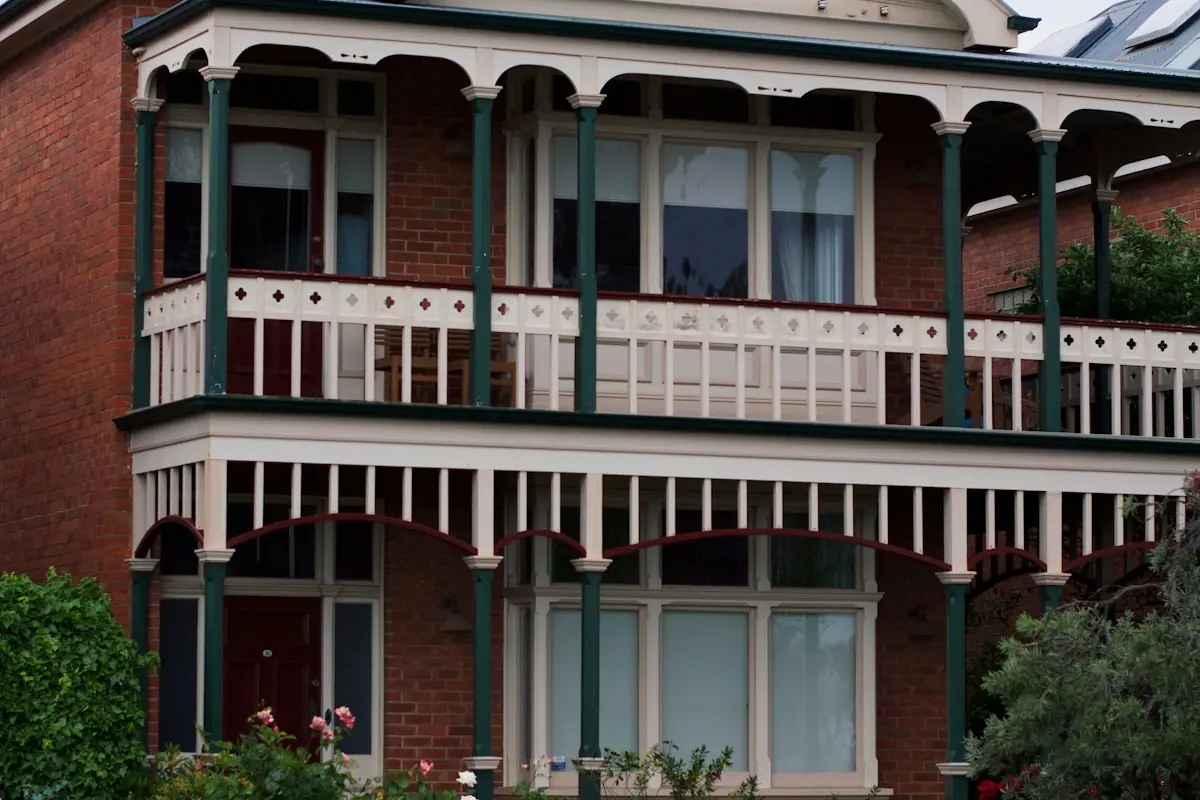
A terrace with an iron-lace balcony
  • An individual heritage listing is on the property itself.It appears on the council’s local environmental plan or the State Heritage Register and restricts changes to the listed fabric. Valuers note it; lenders treat it as a standard security with renovation limits.
  • A conservation area covers the street or suburb.Changes visible from the street need council approval and must respect the character of the area. Interiors and rear additions are usually more flexible.
  • An old house with no listing is assessed on condition alone.Most period homes in Sydney fall here. The valuation question is wiring, plumbing, roofing, damp and structure, not heritage.
  • Approvals already in place are worth money.A rear extension with council approval and a final occupation certificate is valued in full. One without approval can be excluded from the valuation and flagged for the lender.

What do valuers look for in a period home?

The items that move a valuation on an older Sydney house, and what they mean for the loan.

Rising damp or salt dampCommon in terraces; cost to rectify noted. Usually none unless severe; may be a condition.
Roof near end of lifeSlate or terracotta replacement is costly. Noted; rarely a decline.
Unapproved additionsExcluded from value or flagged. Can reduce the loan amount.
Structural movementEngineer’s report may be requested. Lender may hold approval until reported.

Illustrative. Each valuation reflects the specific house and recent sales nearby.

Book my free call

How do you renovate a listed or conservation-area home?

Renovation finance for a period home works like any other: a loan increase or a construction loan drawn against the works, with the valuer assessing the end value. The difference is approvals.

Council will want heritage-sensitive design for anything visible from the street, and some works to listed fabric need a heritage impact statement. Lenders want to see the approval before they release funds, so the sequence is approval, quote, valuation, loan.

Where the works are internal and do not need approval, a loan increase against existing equity is the simpler route. The renovation loans guide walks through both, and the home equity calculator shows what the house will support.

What should you check before you offer on a period home?

Four checks that save money after exchange.

  • Building and pest reportNon-negotiable on a house over fifty years old. Damp, termites and roof condition are the usual findings.
  • Council recordsConfirms the listing status, the conservation area rules and whether past additions were approved.
  • Comparable salesRecent sales of similar period homes nearby anchor the valuation. Charles checks them before you set a limit.
  • Insurance quoteListed homes can cost more to insure because repairs must match the original. Lenders require building insurance from settlement.

Common questions about heritage and period home loans

Can you get a home loan on a heritage-listed house?

Yes. Lenders finance listed homes on standard terms. The listing is noted in the valuation and any renovation plans are checked against it, but the loan itself is a normal home loan.

Does a heritage listing lower the valuation?

Not by itself. Valuers compare the house with recent sales of similar period homes nearby. Condition and approvals move the figure far more than the listing does.

What is the difference between a heritage listing and a conservation area?

A listing applies to an individual property and protects its significant fabric. A conservation area applies to a precinct and controls changes visible from the street. Most Inner West period homes are in conservation areas rather than individually listed.

Will a lender finance a terrace with rising damp?

Usually yes. Damp is common in older masonry and the valuer notes the cost to fix. Severe structural issues are a different matter and may require an engineer’s report before approval.

Can I renovate a heritage home with my home loan?

Yes, through a loan increase or a construction loan once council approval is in place. Lenders release renovation funds against approved plans and quotes, and value the end result.

Are unapproved extensions a problem for the loan?

They can be. A valuer may exclude unapproved work from the value, and some lenders ask for the work to be regularised. It is worth knowing before exchange, when the price can still reflect it.

See the renovation loans guide for financing the works, the low valuation guide for a short valuation, and the Inner West mortgage broker page for the suburbs where most of these homes sit.

Get advice on heritage and period home loans

Charles has the building and pest report, the council listing and the valuation read together before the offer, so the loan is sized to the house you are buying. Free, no credit check.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · Inner West mortgage broker · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies on property types change and differ between lenders, and the examples are illustrations rather than quotes. Links Property Finance holds an Australian Credit Licence authorisation and can confirm how a specific property would be assessed.



