






Call Charles Book a meeting
Mortgage Broker Birrong

Links Property Finance · Home loans in Birrong and across Sydney: Mortgage Broker in Birrong

More than eight in ten Birrong homes are separate houses, many of them long-held family homes.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Inheriting a Birrong family home: how do you use it or buy out your siblings?

If you keep the home, the usual route is refinancing in your own name to pay out your siblings’ shares under the estate. If you sell, your share becomes a deposit once the money is in your account with the estate papers.

Read more

Lenders want the will, probate and a valuation before they lend.

A corner cottage with a hedge
Birrong housing mix: 83.4% houses, 10.8% terraces and semis, 5.5% apartments (ABS Census 2021).

How a lender reads an address in Birrong

Birrong is mostly detached homes, 83.4% of everything built here. With little strata to assess, the lending questions tend to be about the buyer and the block, not the building. Birrong is small, at 1,049 private dwellings, so comparable sales are thin and a valuation can be harder to predict.

  • Postcode2143
  • CouncilCity of Canterbury-Bankstown
  • From the Sydney CBD22 km south west
5.5%

apartments NSW 21.7%

83.4%

separate houses NSW 65.6%

10.8%

terraces and semis NSW 11.7%

30.9%

rented NSW 32.6%

28.5%

with a mortgage NSW 32.5%

1,049

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL10378).

A red-roofed house on a quiet street

Borrowing power for a Birrong purchase

How much could you borrow?

$140,000
None

What moves the number

Choose any that apply. Each shows roughly how much it changes the figure, the way a lender’s assessment would.

$635,000

is an indicative borrowing figure at today’s typical rates. Lenders typically count around 80% of rental income, which is why an investment purchase can lift your number, your real figure comes from a proper assessment.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles Touma from Links Property Finance was a great help with buying my first home. I had plenty of questions and he took the time to explain things clearly without making me feel rushed. He kept me updated throughout and made the process much less stressful. Really appreciated his patience and would happily recommend him to other first home buyers.
Catherine Google review
★★★★★
Charles looked after us really well and his knowledge gave us the confidence to purchase our property. He wasn’t pushy and always ensured we felt comfortable with the repayments.
Sandra Google review
★★★★★
Had a really good experience with Charles at Links Property Finance. He was easy to deal with, always quick to respond and kept everything simple and clear throughout the whole process. You can tell he genuinely cares about getting the best outcome for his clients rather than just getting things done quickly. Really happy with the experience and would happily recommend Charles and Links Property Finance to anyone.
Christian Google review

Inheritances and sibling buyouts in Birrong

When a home is left to several people, one of them can often keep it by borrowing to pay the others their shares.

The lender treats this much like a purchase: it values the property, assesses the borrower’s income, and your inherited share acts like a deposit. The family usually agrees a value, often guided by an independent valuation.

Lenders generally cannot lend against an inheritance you have not yet received. The estate usually needs probate and the executor’s authority before property can be transferred or funds released.

Your solicitor can advise on the estate, the transfer and any stamp duty, which is worth confirming before the family agrees a plan. Inheritances and buying in detail

Terrace houses along a tree-lined street

Family houses in Birrong

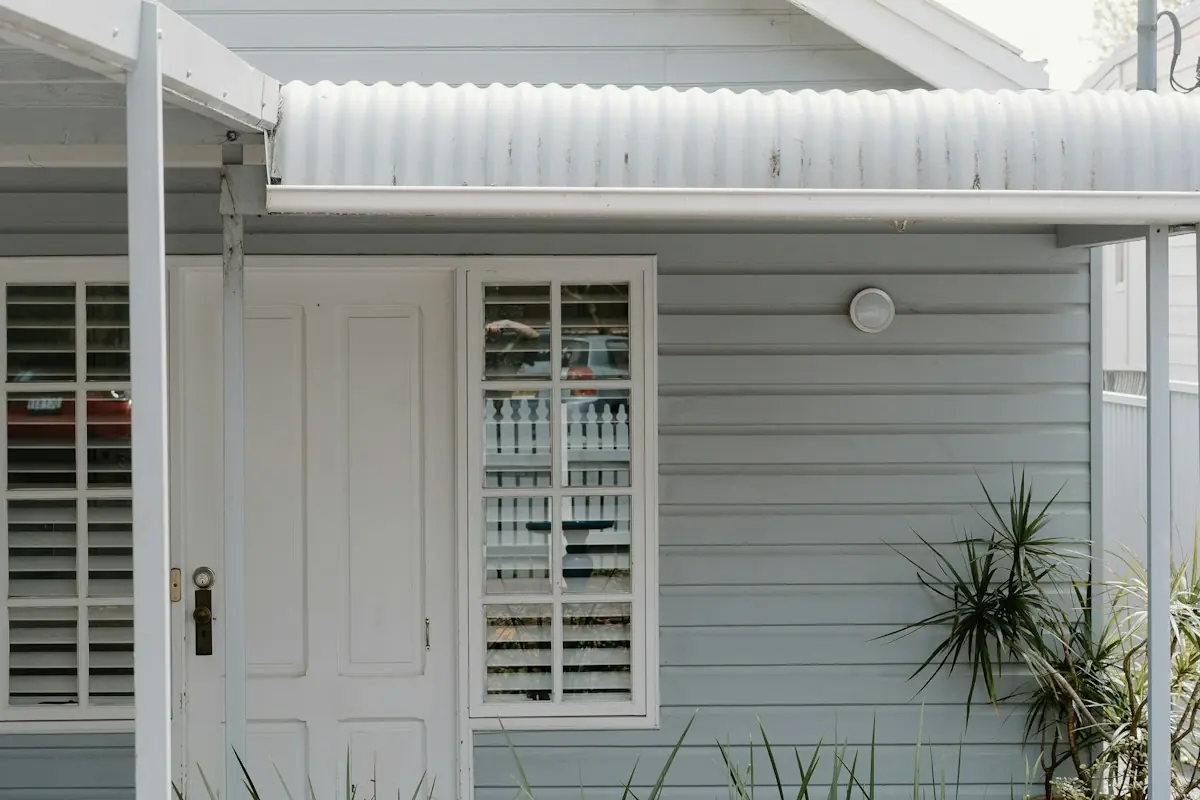
A white weatherboard home with plantation shutters
  • Links Property Finance is based in Enfield, about fifteen minutes from Birrong, with conversations by phone, video or in person.The first one is about the family’s wishes and what one of you can borrow.
  • More than eight in ten Birrong homes are separate houses.Many have been family homes for decades, which is why inheritance questions come up here.

What do lenders need for a buyout?

A first home buyer working through their numbers at the kitchen table
  • The estate position.Probate, the executor’s authority and the agreed shares.
  • Your income alone.The loan to pay out your siblings is assessed on your own finances.

Auburn Road, the parks and Birrong housing

Birrong lies about twenty-two kilometres south-west of the city by its official measure, in the City of Canterbury-Bankstown, and shares postcode 2143 with Regents Park and Potts Hill. A small group of shops is located on Auburn Road.

It has a large number of community facilities, including six playing fields, tennis courts, a large natural reserve, a bowls club and a swimming pool, along with Birrong Boys and Birrong Girls High Schools and a primary school.

  • The Aboriginal word Birrong, meaning star, was adopted as the suburb’s name around 1927.
  • When a Birrong family is working through an inherited home, Links compares a panel that includes ING, Westpac, Resimac, Macquarie and ANZ.
Read the full detail

The Aboriginal word Birrong, meaning star, was adopted as the suburb’s name around 1927. One of the first settlers was Joseph Hyde Potts, who was granted land here in 1835.

Development increased after the railway opened in 1928, and Birrong Park, once subject to flooding, was drained as relief work during the Great Depression. The post office opened in 1955. Today separate houses make up more than eight in ten homes.

When a Birrong family is working through an inherited home, Links compares a panel that includes ING, Westpac, Resimac, Macquarie and ANZ.

Example scenario (illustrative, not a real client): three siblings inherit their parents’ Birrong house, and one wants to keep it.

Once probate is granted, the family agrees a value based on an independent valuation, the sibling staying applies for a loan to pay the other two their shares, and their solicitor handles the transfer from the estate.

Agreeing a fair value

An independent valuation, or appraisals from local agents, gives the family a starting point. The lender will also value the property, and its valuation sets how much it lends.

If the family’s agreed figure is higher than the lender’s valuation, the borrower needs to cover the difference. Estimate the equity.

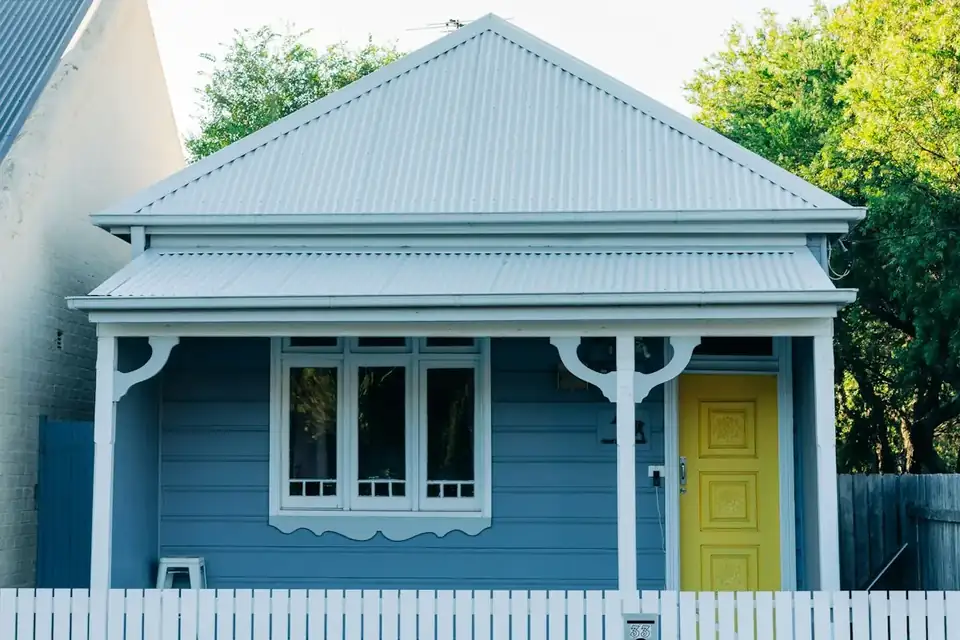
A blue weatherboard cottage

Before probate is granted

Until the estate is administered, the executor controls the property and the beneficiaries cannot usually borrow against their future share. Timelines vary, and some estates take many months.

In some situations short-term finance can help bridge a gap, but it needs care and advice. Bridging loans.

Using an inheritance to buy elsewhere

Once received, inherited money can be used as a deposit. Lenders usually want evidence of its source, such as a letter from the solicitor or executor and statements showing the funds arriving.

Because it arrives as a lump sum, it may not count as genuine savings by itself, although a larger deposit often means that does not matter. Using an inheritance.

Keep, sell or share?

Three paths families weigh for an inherited home.

  • One sibling keeps it. A loan pays the others their shares. Assessed on that sibling’s income.
  • Sell it. Proceeds are divided as the will directs. Simplest for the loan, and a clean outcome for everyone.
  • Keep it together. Co-owned by the beneficiaries, perhaps rented out. A written agreement about the future helps.

What should I check before planning a buyout in Birrong?

The groundwork that keeps things fair and on time.

  • ProbateGranted, or its timeline understood.
  • Legal adviceOn the estate, the transfer and any stamp duty.
  • An agreed valueBased on an independent valuation.
  • Your borrowing powerChecked on your income alone.
  • The other beneficiariesAgreement on figures and timing.
  • Ongoing costsRates, insurance and upkeep on one income.

Common questions about inherited homes in Birrong

Can I buy my siblings out of an inherited house?

Often, yes. You borrow to pay their shares, and your own inherited share acts like a deposit. The lender assesses your income alone.

Can I borrow against an inheritance before probate?

Generally not. Until the estate is administered, the executor controls the property. Some specialist short-term options exist, but they need careful advice.

How do we agree what the house is worth?

An independent valuation or agent appraisals give a starting point. The lender’s valuation sets how much it lends, so large differences need to be covered.

Is stamp duty payable when I buy out my siblings?

It depends on how the transfer is structured and the terms of the will. Your solicitor or conveyancer can advise before the family agrees a plan.

Does inherited money count as genuine savings?

Usually not by itself, because it arrives as a lump sum. With a larger deposit, many lenders do not require genuine savings anyway.

What if I cannot borrow enough to pay out my siblings?

Options can include a longer term, family agreeing to a lower payout or a delay, or selling. Knowing your borrowing power early helps.

Talk to a broker about your Birrong home loan

Thirty minutes with Charles: what you could borrow, which lenders suit Birrong property and what to do next. Free, with no credit check.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.



