Call Charles Book a meeting
Mortgage Broker Burwood Heights

Links Property Finance · Home loans in Burwood Heights and across Sydney: Mortgage Broker in Burwood Heights

Federation houses and apartment buildings share the few streets of Burwood Heights, so a move from one to the other need not mean leaving the suburb.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Moving from a Burwood Heights unit to a house: can you keep the unit?

Often, yes, if your income supports both loans. The unit becomes an investment with its own loan, the house gets a separate loan, and the unit’s equity can help with the deposit without tying the two properties together.

Read more

Lenders count most of the unit’s rent, around 80 per cent, against the new borrowing.

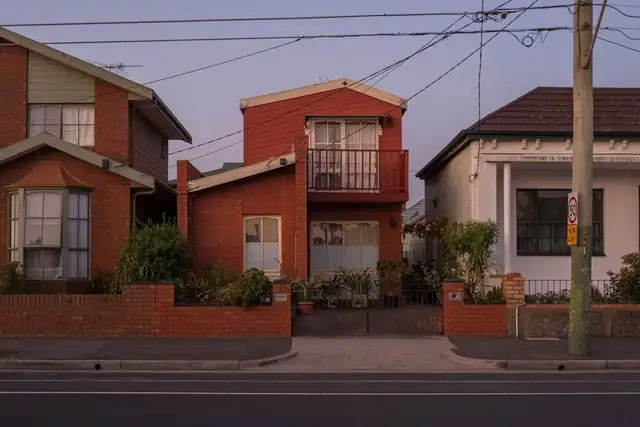
A red-roofed house on a quiet street
In Burwood Heights, houses make up 48.1% of homes, terraces and semis 15.1% and apartments 36.3% (ABS Census 2021).

What Burwood Heights is built of

At 429 homes, Burwood Heights is one of the smaller suburbs nearby, which can make a valuation the slowest part of the loan.

  • Postcode2136
  • CouncilMunicipality of Burwood
  • From the Sydney CBD10 km west
36.3%

apartments NSW 21.7%

48.1%

separate houses NSW 65.6%

15.1%

terraces and semis NSW 11.7%

34.1%

rented NSW 32.6%

29.8%

with a mortgage NSW 32.5%

429

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL10717).

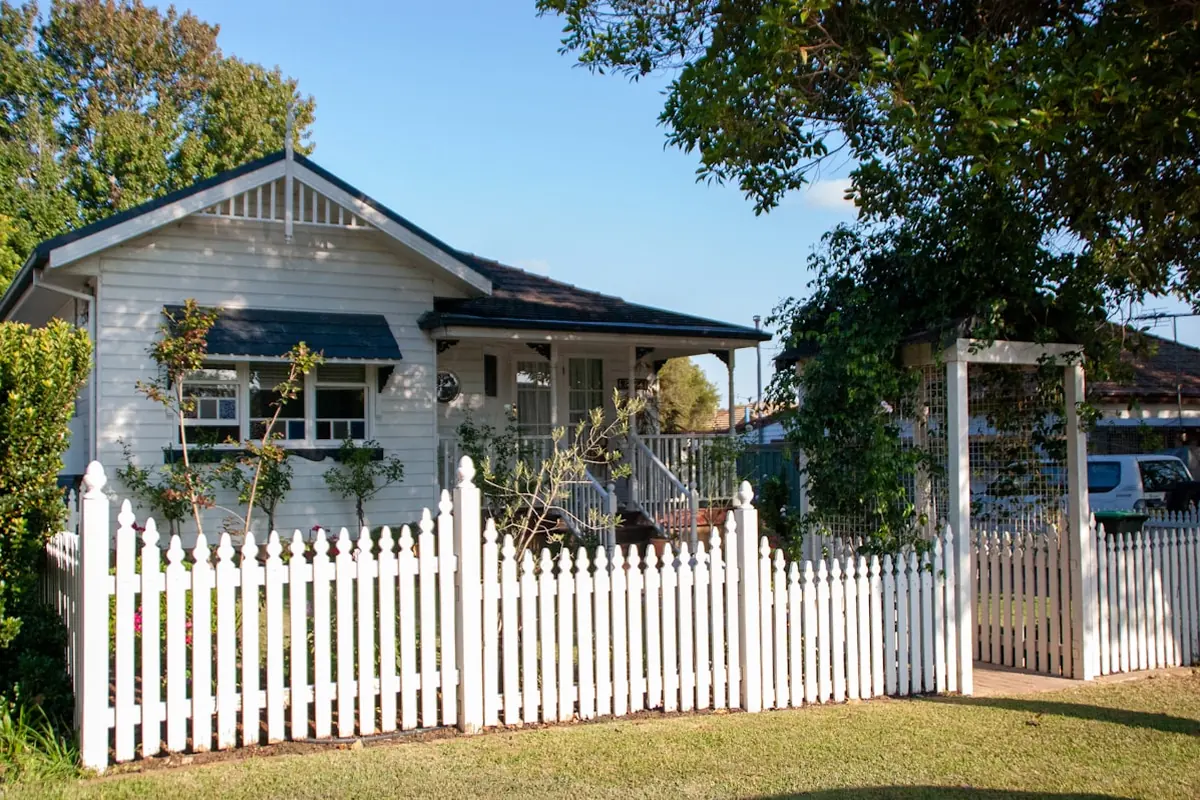
A corner cottage with a hedge

What your Burwood Heights home could fund

Home equity calculator

Home equity calculator

For upgraders and investors, how much of your home could work as a deposit.

$1,100,000
$600,000
  • Total equity$500,000
  • Usable equity (to 80% LVR)$280,000

That usable equity could work as a deposit on an investment property or renovation, structured so your properties aren’t tied together unnecessarily.

Usable equity assumes lending to 80% of your home’s value against your current loan. Lender policy and serviceability decide the real figure.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles Touma from Links Property Finance was a great help with buying my first home. I had plenty of questions and he took the time to explain things clearly without making me feel rushed. He kept me updated throughout and made the process much less stressful. Really appreciated his patience and would happily recommend him to other first home buyers.
Catherine Google review
★★★★★
Charles went above and beyond to help us secure our home loan. He worked hard to find the best option for us and kept us updated throughout the whole process. His knowledge of the lending market was impressive and he made everything straightforward.
Anthony Google review
★★★★★
Had a really good experience with Charles at Links Property Finance. He was easy to deal with, always quick to respond and kept everything simple and clear throughout the whole process. You can tell he genuinely cares about getting the best outcome for his clients rather than just getting things done quickly. Really happy with the experience and would happily recommend Charles and Links Property Finance to anyone.
Christian Google review

Keeping your Burwood Heights unit as a rental

Moving out does not change the unit loan by itself, but it changes what the loan is for.

Lenders generally expect to hear when a home becomes a rental, and the pricing or product can change as a result, so raise it before the tenant signs rather than after the first rent arrives.

The house loan should normally stand on its own, secured by the house, while the unit loan stays in its own account against the unit.

Whether any equity in the unit is drawn for the house deposit is a decision to make once, carefully, with your accountant involved, because unpicking a tangled structure later costs time and fees. How releasing equity works

A terrace with an iron-lace balcony
A Federation-style house in Sydney
  • Links Property Finance is based in Enfield, next door to Burwood Heights and in the same 2136 postcode.Most of the work happens by phone and video, and the job is to test both properties against lender policy before the house contract is signed, so the unit and the house end up financed as two tidy pieces.
  • For a suburb of only a few streets, Burwood Heights holds a wide spread of homes, from Federation houses to apartment buildings on Burwood Road and Liverpool Road.That spread is what lets an owner trade a unit for a house without changing suburb, and it is also why the two loans need to be thought about separately.

Why should the two loans stay separate?

A family together in their backyard
  • Lenders price and assess borrowing for a rental differently from borrowing for the home you live in, and one loan doing both jobs makes the records hard to follow.Whether any interest is deductible is for your accountant to say. The lending side keeps each loan tied to one purpose, so that question has a clean answer.
  • Paying extra off the unit loan just before you move out can feel responsible, yet it shrinks the debt left on the unit once it is rented.An offset account holds spare cash against a loan without lowering the balance, while extra repayments lower it. Put the choice between offset and redraw to your accountant before moving any money.

Liverpool Road, Burwood Road and the streets between

Burwood Heights has no railway station inside its boundaries. Buses on Liverpool Road, the northern edge, stop beside the suburb and run towards Ashfield station one way and Strathfield station the other, and services on Burwood Road, the western edge, head north to Burwood station.

Tenants may weigh that bus access, but an investment application still rests on rent evidence for the unit itself.

A blue-roofed house with a front path

Valuing a Federation house under conservation controls

A valuer looks at the land, the state of the house, the original detail that survives and recent sales of comparable older houses. The figure is based on the house as it stands on inspection day.

Plans you have not yet had approved add nothing to it, however good they are.

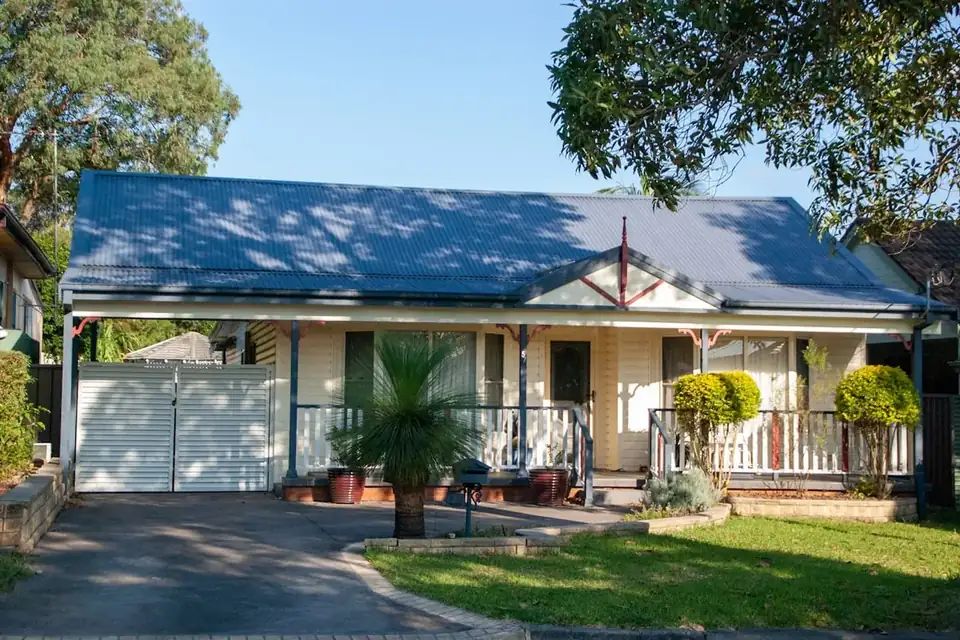
A house with a wide front verandah

Offset, redraw and the order of moves

Order matters here. Speak to your accountant while you still live in the unit, set up any offset account before savings build up, and hold off redrawing from the unit loan for the house until that advice is in hand.

If equity in the unit goes towards the house deposit, it is usually set up as a separate split, so the statements show plainly what that money paid for. Your accountant can confirm how it should be treated. Offset accounts explained.

Burwood Heights apartments and the strata records

Apartments in Burwood Heights are spread across separate buildings, including some on Burwood Road and Liverpool Road, and each building has its own records and upkeep history, so a first buyer should not assume two units here carry the same risk.

The strata records show the balance of the sinking fund, now called the capital works fund in NSW, any special levies voted or flagged in the minutes, and repairs the owners corporation is planning.

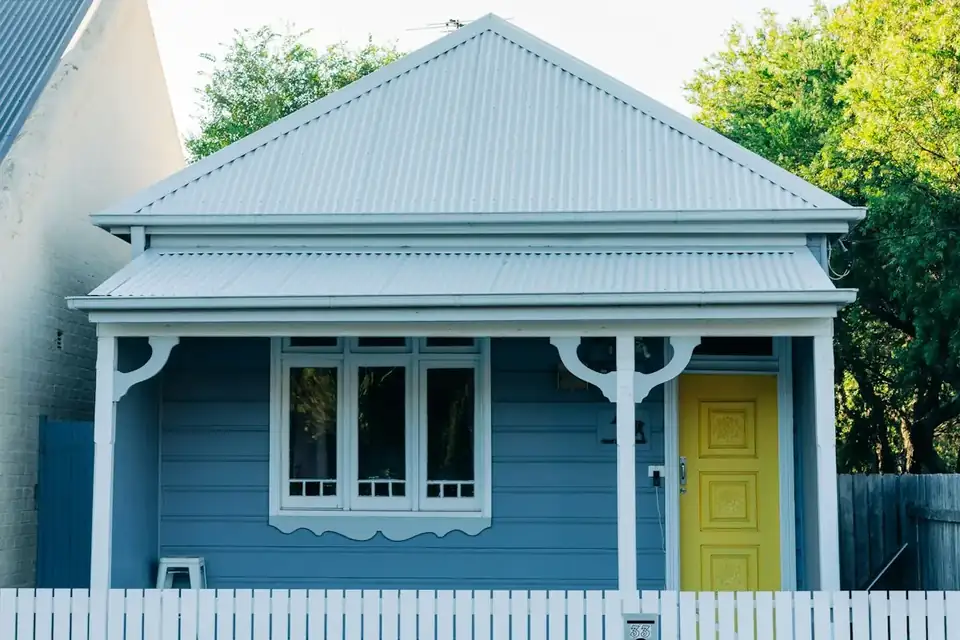
A blue weatherboard cottage

How does a unit to house move run?

One. A first call. Bring the unit loan details, a rough idea of the rent and the sort of house you want. You finish knowing whether keeping the unit looks workable and roughly what the house deposit needs to be.

  • Two. The structure. Your accountant’s view comes in here. Together we settle which property secures which debt, whether any equity comes out of the unit, and where an offset account belongs.
  • Three. Pre-approval. Both loans are assessed together, with the rent evidence on file. The house loan goes to a lender whose rules suit the pair, which is not always the lender that already holds the unit.
  • Four. Contract, valuation, settlement. The house is valued, conditions are cleared, and the lender on the unit is told about its new use. Book a call or call 0423 952 184.
A brick bungalow with a tidy front lawn

Before you offer in Burwood Heights

What to have in hand before an offer on a house here, particularly when a unit is being kept.

  • The planning certificate in the contractIt shows whether heritage controls affect the land. For a house on Claremont Road, Culdees Road or Kelso Street, read it before you sketch any building work.
  • Rent evidence for the unitIf the rent helps you afford the house, the lender will want proof of it. A current lease or a written appraisal from a local agent usually covers it.
  • A building report on the houseOlder houses can hide tired wiring, roof wear or damp. An inspection before you offer tells you what the valuer is likely to notice.
  • Strata records, if it is an apartmentLevies, the capital works fund and the minutes of recent meetings. The same records are worth keeping for the unit you hold onto.
  • Your accountant’s view, in writingBefore the house settles and before a tenant moves in. A loan structure is far easier to set correctly at the start than to rearrange afterwards.

Common questions about moving up in Burwood Heights

Charles Touma, mortgage broker at Links Property FinanceCharles Touma is glad to talk any of these through with you on a call.

Can I keep my unit as an investment when I buy a house?

Often, if your income can carry both loans once the lender has counted part of the rent and applied its buffer. The deposit for the house can come from savings, from equity in the unit, or both.

The earlier the structure is agreed with your accountant, the easier it is to keep each loan tied to one purpose and one property.

Does the conservation area on Culdees Road and Claremont Road affect a loan?

Usually not for a straightforward purchase: Burwood Council’s Badminton Road to Culdees Road Conservation Area governs what can be changed on the property, not whether a lender accepts it as security.

It matters when the plan includes building work, because construction funds generally need approved plans. Check with council what applies to the particular house before you set a renovation budget.

How do lenders count rent from a unit I move out of?

They add a reduced share of the expected rent to your income, leaving room for vacancies and costs, and they count the unit loan repayments and strata levies against you.

Before a tenant is in, an agent’s written rental appraisal is the usual evidence. Afterwards, the lease and rent statements do the job. The exact share counted differs from lender to lender.

Should I pay down the unit loan before I move out?

Not before asking your accountant: extra repayments reduce the debt left on the unit once it becomes a rental.

Many owners in this position hold spare cash in an offset account instead, which lowers the interest charged without lowering the balance. Your accountant can say which approach suits your circumstances.

What is the difference between an offset account and redraw?

An offset is a separate transaction account linked to the loan, and its balance is set against the loan when interest is worked out, while the loan balance stays the same.

Redraw lets you take back extra repayments you have already made, which means the loan balance went down and then goes back up. Not every loan offers both, and fees vary.

Can equity in my unit fund the deposit on a house?

It can, provided the unit is worth enough more than its loan and your income supports the extra borrowing.

The equity is usually released as a separate split secured by the unit, which keeps a clear record of what it paid for. Usable equity is normally worked out against a percentage of the unit’s value, not the whole of it.

Talk to a broker about your Burwood Heights home loan

Thirty minutes with Charles: what you could borrow, which lenders suit Burwood Heights property and what to do next. Free, with no credit check.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.