Call Charles Book a meeting
Mortgage Broker Belfield

Links Property Finance · Home loans in Belfield and across Sydney: Mortgage Broker in Belfield

Belfield’s streets were first sold as home sites after the First World War. When an early house on one of those blocks stops working for you, rebuilding can make more sense than moving.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Rebuilding on your Belfield block: how does the construction loan work?

Your land is the equity. The lender values the block plus the finished home under a fixed-price contract and pays the builder in stages as each one is inspected.

Read more

You pay interest only on what has been drawn, and you will usually need somewhere to live during the build, which is part of the borrowing test.

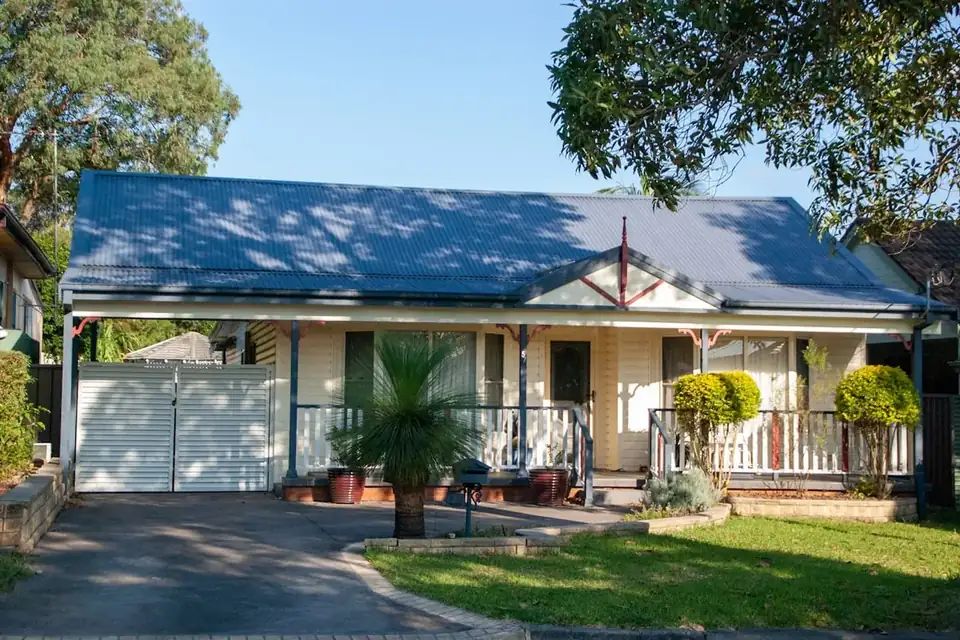
A house with a wide front verandah
Belfield housing mix: 66.8% houses, 23.7% terraces and semis, 8.9% apartments (ABS Census 2021).

The housing mix in Belfield

Belfield is house country: 66.8% of dwellings are freestanding, against 65.6% for NSW. Valuers have plenty of comparable house sales to lean on, which tends to make valuations predictable. Attached homes are a big part of Belfield, at 23.7% against 11.7% statewide. Older terraces can carry renovation upside that a lender values only once the work is done, which is a timing question.

  • Postcode2191
  • CouncilCity of Canterbury-Bankstown
  • From the Sydney CBD12.3 km west
8.9%

apartments NSW 21.7%

66.8%

separate houses NSW 65.6%

23.7%

terraces and semis NSW 11.7%

30.3%

rented NSW 32.6%

34.2%

with a mortgage NSW 32.5%

2,409

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL10257).

A brick house with a gabled roof

How much equity could you use in Belfield?

Home equity calculator

Home equity calculator

For upgraders and investors, how much of your home could work as a deposit.

$1,100,000
$600,000
  • Total equity$500,000
  • Usable equity (to 80% LVR)$280,000

That usable equity could work as a deposit on an investment property or renovation, structured so your properties aren’t tied together unnecessarily.

Usable equity assumes lending to 80% of your home’s value against your current loan. Lender policy and serviceability decide the real figure.


Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles at Links Property Finance made buying our first home so much easier than we expected. As first home buyers, we had a lot of questions around borrowing capacity, our deposit and the different government schemes available to us. Charles explained everything clearly, compared different lenders and kept us updated throughout the whole process. He was always easy to reach and made sure we understood what was happening from pre approval right through to getting our home loan approved. We would definitely recommend Links Property Finance to anyone looking for a mortgage broker, especially first home buyers who want someone to guide them through the process.
Michael Google review
★★★★★
Charles looked after us really well and his knowledge gave us the confidence to purchase our property. He wasn’t pushy and always ensured we felt comfortable with the repayments.
Sandra Google review
★★★★★
Charles went above and beyond to help us secure our home loan. He worked hard to find the best option for us and kept us updated throughout the whole process. His knowledge of the lending market was impressive and he made everything straightforward.
Anthony Google review

Talk to a broker about your Belfield home loan

Tell Charles what is owed on the Belfield property, what the household earns and the kind of home you have in mind. You leave with a borrowing range, a draw-down plan and a short list of what to line up first. It costs nothing and commits you to nothing.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together

Belfield blocks, bungalows and what comes next

A family on the porch of their home
  • Belfield owners can talk to Links by phone or video, or meet at home, with the business based a short drive away in Enfield.There is no Belfield office. There is one broker who knows that funding a build is a different job from funding a purchase.
  • Belfield’s streets were subdivided and sold as home sites after the First World War, and some were set aside for war service homes.Council’s local history describes the War Service Homes precinct as early bungalow style and counts it among the area’s most interesting heritage assets. When a cottage like that stops suiting the family, the block becomes the starting point for the loan, and that is where rebuild finance begins.

Why is a rebuild loan paid out in stages?

A family together in their backyard
  • Rebuilding on land you already own means there is no purchase price for the lender to lean on.Instead it looks at your block, the approved plans and a fixed-price contract from a licensed builder, then estimates what the completed house should be worth.
  • The money is then released in instalments as the builder finishes each agreed stage.An inspection normally comes before each payment, interest is charged only on what has been drawn so far, and the facility turns into an ordinary home loan once the house is finished and signed off.

Burwood Road shops, Punchbowl Road and the bungalow streets

Belfield has no railway station of its own, so buses link it to the rail network. Route 415, between Campsie and Chiswick, stops at the Belfield shops on Burwood Road and carries on to Strathfield and Burwood stations.

Route 450, between Strathfield and Hurstville, stops where Punchbowl Road meets Burwood Road, and Punchbowl Road itself forms the suburb’s northern edge. For a rebuild, that mostly shapes where you rent during construction, ideally close to school and those buses.

A blue-roofed house with a front path

Rebuild finance in Belfield, stage by stage

The order that keeps a rebuild moving.

A red-roofed house on a quiet street

From first call to final draw

One. A first conversation. Around thirty minutes and no paperwork: what you owe on the Belfield property, what the household earns and the home you want to end up in. You finish the call knowing whether a rebuild looks achievable.

  • Two. Matching the lender. Construction lending varies more than most products, so your application is placed with a lender whose approach suits your income, your builder’s contract and the finished home, not simply to the bank you already use.
  • Three. Plans, contract and approval. With plans and a fixed-price contract in hand, the application is lodged. Approval arrives before demolition starts, never after it.
  • Four. Building and completion. Each progress claim is checked and paid in turn, and the facility settles into a standard home loan when the house is complete. Book a call or call 0423 952 184.

Renovate the bungalow, or start again?

A weatherboard house with a white picket fence

First home buyers who want a Belfield house

Apartments are thin on the ground here, so a first purchase usually means a semi, a townhouse or a house.

  • The 5% Deposit SchemeHouses qualify as well as units. The Sydney price cap is $1.5 million, and an eligible buyer can purchase with a 5% deposit and no lenders mortgage insurance. Check eligibility.
  • NSW duty reliefFor eligible first home buyers in NSW there is no transfer duty up to $800,000 and a concession between $800,000 and $1 million. Run your price.
  • Help from familyA family guarantee or a documented gift can close the gap when savings fall short of the deposit plus costs.
  • Buying now, rebuilding laterIf a knock-down is the long-term plan, say so at the start. The first loan can be set up with the later construction stage in mind.
A row of red-brick terraces

Before you sign a building contract in Belfield

Settle these before the builder’s contract is signed, because each one changes what the lender will fund.

  • A fixed price, not a list of allowancesProvisional sums leave the final cost open. Valuers and lenders are more comfortable with a set price and the extras written out in full.
  • Demolition and site work itemisedRemoving the old house, excavation, soil conditions and service connections can fall outside the base price. Have them written into the contract so the loan can cover them.
  • Planning controls checked earlySpeak with council and read the planning certificate before paying for full plans, so the design you finance is one that can be approved.
  • Payment stages that matchThe builder’s claim schedule and the lender’s draw stages should line up, or each claim takes longer to pay.
  • Somewhere to liveLine up the rental and its cost before demolition, since you will be paying it and the loan interest at the same time.

Common questions about rebuilding and buying in Belfield

How does a knock-down rebuild loan work if I already own the block?

Your existing property becomes the security. The lender reviews the land, the approved plans and a fixed-price contract from a licensed builder, estimates what the finished home will be worth and approves a construction facility, usually folding in any mortgage you still have.

My house is north of Punchbowl Road. Is it still in Belfield?

If it was in the part of Belfield north of Punchbowl Road that sat in Strathfield Council’s area, it is now in Strathfield South, following a Geographical Names Board decision. Belfield today lies wholly within the City of Canterbury-Bankstown.

Can the equity in my land stand in for a cash deposit on the build?

Often, yes. If you own the property outright or have paid down enough of the current loan, the land can cover the share of the project a deposit would normally cover. You will still want savings for costs and a buffer for changes during construction.

Do we need to budget for rent while the new house goes up?

Yes. Once the old house is demolished you will be paying rent, or another housing cost, while interest runs on the construction loan. A lender looks at whether your income can carry both for the length of the build, and delays can add months.

Is it better to renovate an early bungalow or knock it down?

It depends on the house and on what you want from it. A structurally sound bungalow that needs a new kitchen, bathroom or rear extension can often be improved with an equity release or a smaller loan.

Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.