




Call Charles Book a meeting
Professional lending

Links Property Finance · Construction loan mortgage broker, Sydney: Knock-Down Rebuild Loans

Rebuilding on land you already own: no purchase price, so everything runs on the value of the finished home.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Knock down and rebuild? How do you finance the whole build?

A knock-down rebuild replaces your existing house with a new one on the same land. It is funded with a construction loan against your land. You also need to cover where you live during the build, which is part of the borrowing test.

Read more

The lender values the land plus the finished home under a fixed-price contract, pays the builder in stages after each inspection, and charges interest only on what has been drawn.

Part of the construction loans guide.

An empty room with a view, ready to move into

Recent Links clients, including a new build

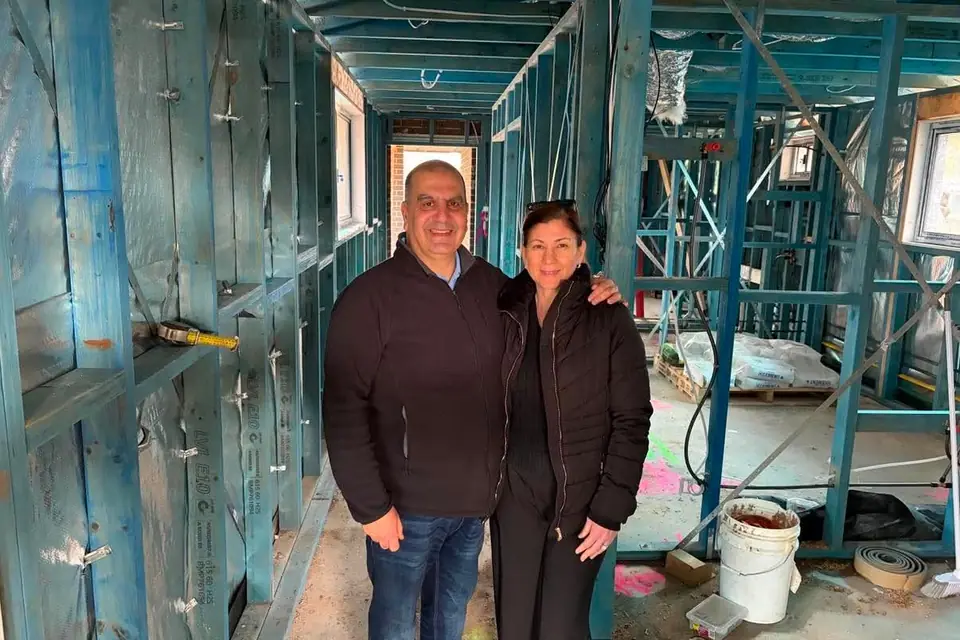
  • Two Links Property Finance clients standing inside the timber frame of their new home Building · Sydney
    Their new home, at frame stage. Walls next. The frame is up.
  • Three Links Property Finance clients in front of the agent’s board at the home they bought Family buy · South West Sydney
    Bought, and all smiles. A family purchase in Sydney’s south-west.
  • Next one

    Yours could be the next one.

    One short call tells you what you can borrow and what to do first.

    Book my free call

How much could you borrow?

How much could you borrow?

$140,000
None

What moves the number

Choose any that apply. Each shows roughly how much it changes the figure, the way a lender’s assessment would.

$635,000

is an indicative borrowing figure at today’s typical rates. Lenders typically count around 80% of rental income, which is why an investment purchase can lift your number, your real figure comes from a proper assessment.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles Touma from Links Property Finance was a great help with buying my first home. I had plenty of questions and he took the time to explain things clearly without making me feel rushed. He kept me updated throughout and made the process much less stressful. Really appreciated his patience and would happily recommend him to other first home buyers.
Catherine Google review
★★★★★
Charles and the team at links property finance recently assisted me with my purchase of my first property in Burwood. As a first home buyer, Charles made the process simple and easy. I would recommend Charles to all first home buyers
Elijah Google review
★★★★★
Highly recommend Charles! Professional, knowledgeable and very easy to work with. He helped us navigate the home loan process and found a great solution that suited our needs. Excellent service from start to finish.
Daniel Google review

How is the lending structured?

A family on the porch of their home
  • Your existing property, usually with the house still on it, provides the security.
  • The lender assesses the completed dwelling's value based on the plans and the fixed-price build contract, then approves a facility covering the build.
  • Funds are released in stages as construction progresses, commonly at slab, frame, lockup, fit-off and completion, each after an inspection.
  • Interest accrues only on what has been drawn, so repayments start small and grow as the build advances.

What is the lender assessing?

Three things. The end value of the completed home, which caps the facility. Your capacity to service the eventual full debt, tested at a buffer rate. And the build itself: a licensed builder, a fixed-price contract, council or complying development approval, and adequate insurance.

Owner-builder projects face a much shorter lender list and tighter terms, which is worth knowing before committing to that path.

Where do rebuilds go wrong?

Almost always the same two places. Contingency: variations, site costs and selections accumulate, and a mid-build application for more money is assessed hard and slowly. Holding the contingency inside the approved facility from the start means changes get funded at loan pricing on your timeline.

And accommodation: you are paying a mortgage on a site with no house on it while also paying rent somewhere, for as long as the build takes. Both belong in the budget from day one.

Rebuild against renovate against move

Worth comparing. A major renovation avoids demolition and can sometimes be funded more simply through an equity release. Moving avoids the build entirely but incurs transfer duty and selling costs. There is no universally right answer, only arithmetic and temperament.

A rebuild delivers exactly the house you want on land you already have, at the cost of complexity and time.

A client at the timber frame stage of their build

The sequence, in order

Each stage depends on the one before it, which is why the finance is arranged before the builder is booked.

  • Capacity confirmed firstBefore plans are finalised, before a builder is engaged. The end value and your servicing set what is possible.
  • Approval and fixed-price contractCouncil or complying development approval, a licensed builder and a fixed-price contract are what lenders want to see.
  • Staged drawdownsFive stages is typical, each after inspection, with interest on drawn funds only. The construction guide.
  • Contingency inside the facilityNot a savings account you hope not to touch. Inside the approved amount, available at loan pricing.

Common questions about knock-down rebuild

Can I borrow against land I already own?

Yes, that is the usual structure. Your existing property provides the security, and the lender assesses the completed home's value from the plans and the build contract.

Existing equity in the land frequently means little or no additional cash deposit is required, which is one of the genuine advantages of rebuilding.

How do progress payments work?

The approved facility releases funds at completed construction stages, commonly slab, frame, lockup, fit-off and completion, each after an inspection.

You pay interest only on what has been drawn, so repayments start low and rise as the build advances. The builder is paid from the facility rather than by you directly.

What happens if the build runs over budget?

Variations and site costs come from your contingency, which is precisely why it should sit inside the approved facility rather than in a savings account. Applying for additional funds mid-build is possible but assessed hard and slowly, and it happens at the worst possible moment.

Where do I live during construction?

Wherever you arrange, and it costs money. You will typically be servicing the loan on a site with no house while paying rent elsewhere, for the duration of the build. It is the cost most rebuild budgets omit, and it belongs in the plan from the beginning.

Is a rebuild better than renovating?

It depends on the existing house and what you want. Renovating avoids demolition and can sometimes be funded more simply; rebuilding gives you exactly the home you want without the compromises of working around old structure. Compare build cost plus contingency plus holding costs against the renovation alternative before choosing.

Get advice on knock-down rebuild loans

Charles can price the rebuild against buying elsewhere, including the holding costs nobody budgets for.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A Links Property Finance client in front of the sold sign at the first home she bought
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Professional lending policies, eligible occupations and loan-to-value thresholds vary by lender and change over time. Eligibility is confirmed against current lender policy in an assessment; nothing on this page is a promise that any lender will approve any application.



