
Call Charles Book a meeting
Building and renovating

Links Property Finance · Refinance mortgage broker, Sydney: Home Renovation Loans

Most renovations are funded from savings, redraw or a loan top-up using your equity, while major structural work usually needs a construction loan.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Renovating? How do you fund it for the size of the job?

Match the funding to the job. Small work comes from savings, an offset or redraw; medium work from a loan top-up using your equity, valued on today’s home or the finished one; structural work or a second storey from a construction loan paid in stages.

Read more

Lenders want quotes, plans and approvals before they release funds.

Part of the refinancing guide.

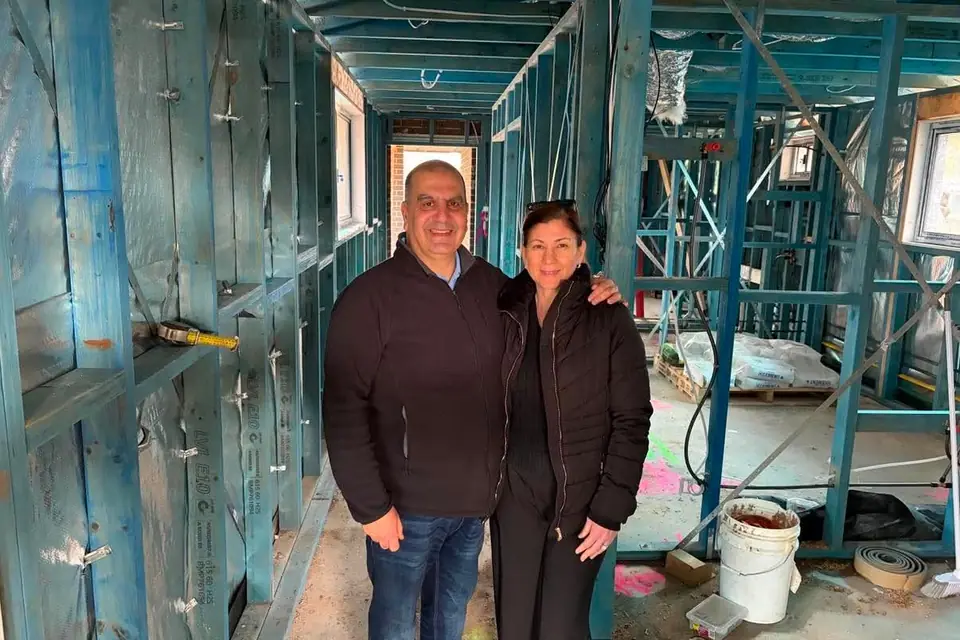
A client at the timber frame stage of their build

Recent Links clients, including a new build

  • Two Links Property Finance clients standing inside the timber frame of their new home Building · Sydney
    Their new home, at frame stage. Walls next. The frame is up.
  • A Links Property Finance client in front of the sold sign at the first home she bought First home · Inner West
    Sold. Her first home. Deposit, scheme and lender, sorted.
  • Next one

    Your sold sign could be next.

    A free 30-minute call shows where you stand.

    Book my free call

How much equity could you use?

Home equity calculator

Home equity calculator

For upgraders and investors, how much of your home could work as a deposit.

$1,100,000
$600,000
  • Total equity$500,000
  • Usable equity (to 80% LVR)$280,000

That usable equity could work as a deposit on an investment property or renovation, structured so your properties aren’t tied together unnecessarily.

Usable equity assumes lending to 80% of your home’s value against your current loan. Lender policy and serviceability decide the real figure.
Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
I found Charles and Links Property Finance very prompt and professional to deal with. Made it all so easy.
Marg Google review
★★★★★
Charles went above and beyond to help us secure our home loan. He worked hard to find the best option for us and kept us updated throughout the whole process. His knowledge of the lending market was impressive and he made everything straightforward.
Anthony Google review
★★★★★
Charles is an absolute star at what he does. He was straight-up, highly professional, and worked hard to secure a fantastic rate for our home loan. Communication was prompt and clear the entire way through. I would trust him with any future financial needs
Alan Google review

Four ways to fund a renovation

A brick bungalow with a front garden
  • Savings, offset or redraw.The cheapest route for smaller jobs, because there is no application and no new debt beyond what you already have.
  • A loan top-up using your equity.The lender increases your home loan, usually up to 80 per cent of the property’s value, and pays the extra to you. It suits cosmetic and mid-sized work.
  • A construction loan for major work.Structural renovations, extensions and second storeys are usually funded in progress payments as the builder reaches each stage. See construction loans.
  • A personal loan for small jobs.Quick to arrange but at a much higher rate than a home loan, so it suits only small amounts you can repay quickly.

Renovating with a construction loan

A house behind a white picket fence
  • The lender values the property as if the work were already complete.That valuation of the finished home is what lets you borrow against the value the renovation creates.
  • Funds are released in stages, against the builder’s invoices.You pay interest only on what has been drawn, and the lender may inspect the work before each payment.
  • A fixed-price contract with a licensed builder is usually required.Owner-builder work and cost-plus contracts narrow the lender options considerably. See owner builder loans.

Council approval and heritage areas

Major work often needs a development application or a complying development certificate before a lender will fund it. Across the Inner West, many streets sit in heritage conservation areas, where approvals take longer and design changes are common.

Allow for that time in your plans, because loan approvals and valuations only stay current for a limited period.

How much can you borrow to renovate?

For a top-up, the limit is usually your equity: up to 80 per cent of the property’s current value, less what you owe, without paying LMI, and provided your income supports the larger repayment.

For a construction loan, the lender works from the as-if-complete value instead. The calculator on this page shows the equity side, and Charles can test the repayments across lenders.

Common questions about renovation loans

Can I add renovation costs to my home loan?

Usually, yes. If you have enough equity and your income supports the higher repayment, your lender can increase the loan, known as a top-up. Larger structural work is more often funded through a construction loan that pays the builder in stages.

What is the cheapest way to pay for a renovation?

Money you already have in savings or an offset account, because there is no new debt and no application. After that, a home loan top-up is usually cheaper than a personal loan or a credit card because of the lower interest rate.

Do I need council approval before getting a renovation loan?

For structural work, generally yes. Lenders funding major renovations usually want approved plans and a building contract before they commit. Cosmetic work such as a kitchen or bathroom refresh often needs neither.

Can I borrow to renovate an investment property?

Yes, and the loan structure matters for tax. Keeping the renovation borrowing in its own split, separate from personal debt, makes the interest easier to track. Repairs and improvements are treated differently for tax, so check with your accountant.

Will a renovation add to my home’s value?

It can, but rarely dollar for dollar. Valuers look at what comparable renovated homes sell for, so overcapitalising is a real risk in some streets. A construction loan valuation done on an as-if-complete basis gives you an independent view before you start.

Thinking bigger than a renovation? Our guide to knock down rebuild loans covers starting again on the same block.

Get advice on home renovation loans

Charles can work out how much equity you can use, which structure suits the scope of work, and what the lender will need before you sign a builder.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · Construction loans

General information only, not credit or financial advice. Lender policies on renovation and construction lending, valuations and progress payments vary and change over time. Council requirements depend on the property and the scope of work.