



Call Charles Book a meeting
Mortgage Broker Penrith

Links Property Finance · Home loans in Penrith and across Sydney: Mortgage Broker in Penrith

Penrith is house-and-land country at Sydney’s western edge, with an older river city at its centre.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Buying a house in Penrith: how much can you borrow?

As much as your income supports after living costs and debts, tested at a rate about 3 per cent above the one you would pay; the suburb does not change that.

Read more

What Penrith changes is the property: a house-and-land package needs a construction loan and progress payments, while an established house is valued on land and recent sales.

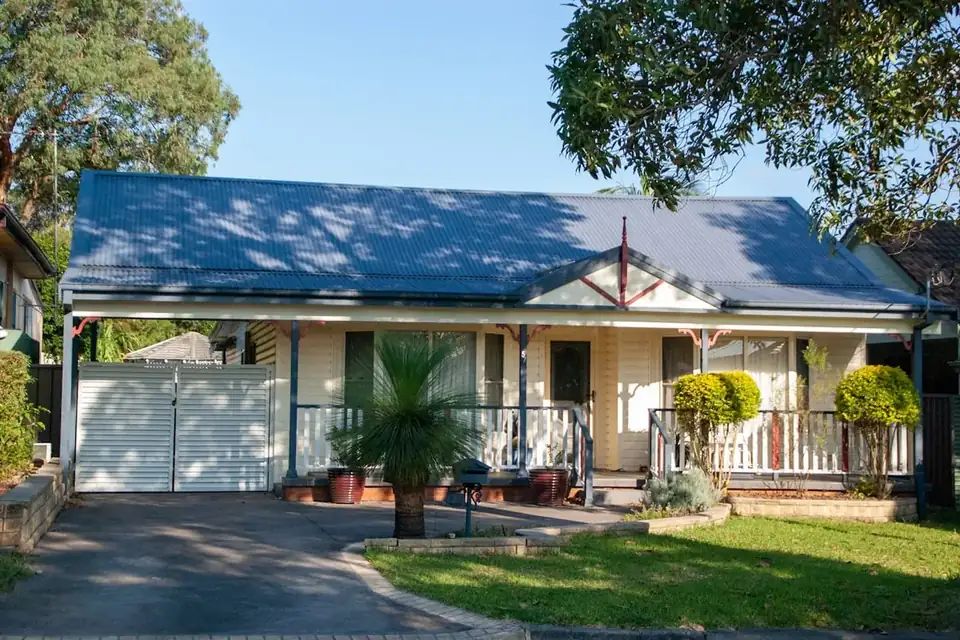
A blue-roofed house with a front path
Of Penrith's homes, 36.0% are houses, 20.4% terraces and semis and 43.4% apartments (ABS Census 2021).

Penrith’s housing, in numbers

With 60.2% of households renting, Penrith is a tenant market. High rental demand here helps an investment loan, because lenders count part of the expected rent toward servicing. Just over four in ten homes in Penrith are apartments, about twice the share across NSW. Some lenders cap how much they lend into one large complex, so a unit can be easy at one bank and full at another.

Terraces and semis are a familiar sight in Penrith, at 20.4% of the housing. Heritage controls on some streets limit what can be changed, which matters if the plan is to renovate with the loan.

  • Postcode2750
  • CouncilCity of Penrith
  • From the Sydney CBD55 km west
43.4%

apartments NSW 21.7%

36.0%

separate houses NSW 65.6%

20.4%

terraces and semis NSW 11.7%

60.2%

rented NSW 32.6%

20.6%

with a mortgage NSW 32.5%

9,388

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL13195).

A weatherboard house with a white picket fence

Borrowing power for a Penrith purchase

How much could you borrow?

$140,000
None

What moves the number

Choose any that apply. Each shows roughly how much it changes the figure, the way a lender’s assessment would.

$635,000

is an indicative borrowing figure at today’s typical rates. Lenders typically count around 80% of rental income, which is why an investment purchase can lift your number, your real figure comes from a proper assessment.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
As a first home buyer, I was pretty overwhelmed at the start, but Charles made everything much easier. He explained the process step by step and helped me understand my borrowing options. His professionalism and responsiveness were excellent.
Ric Google review
★★★★★
Charles at Links Property Finance made buying our first home so much easier than we expected. As first home buyers, we had a lot of questions around borrowing capacity, our deposit and the different government schemes available to us. Charles explained everything clearly, compared different lenders and kept us updated throughout the whole process. He was always easy to reach and made sure we understood what was happening from pre approval right through to getting our home loan approved. We would definitely recommend Links Property Finance to anyone looking for a mortgage broker, especially first home buyers who want someone to guide them through the process.
Michael Google review
★★★★★
I found Charles and Links Property Finance very prompt and professional to deal with. Made it all so easy.
Marg Google review

Helping buyers and builders in Penrith

A Sydney house with a picket fence
  • Links Property Finance works across Western Sydney by phone, video and in person when it helps.Penrith splits cleanly: the established city, houses and units financing conventionally at the west's best-value prices, and the release belt, where files are land registrations, build contracts and staged drawdowns.
  • Both halves are first-home country.The schemes' caps clear almost everything here, and the deposit maths that looks impossible closer in becomes a plan with a date on it.

Building at the frontier

A family together in their backyard
  • House-and-land around Penrith runs the standard sequence, land settling on registration, build drawing in stages against a fixed-price contract, with the frontier's usual frictions: registration estimates that slip, price-review clauses, site costs that vary with the ground.
  • The defences are structural: finance shaped before contracts are signed, approvals kept current through delays, contingency held inside the facility.The construction guide walks every stage.

Penrith station, the Nepean and the release belt

Penrith station, on Jane Street in the city centre, is served by suburban trains to the city and by Blue Mountains intercity services, with a large bus interchange on its southern side.

The suburb sits on the eastern bank of the Nepean River, with Westfield Penrith and High Street forming the commercial centre.

  • Housing in Penrith itself is a mix of freestanding houses, townhouses and semis, and apartment blocks close to the station and the city centre.
  • Links compares lenders such as ANZ, Westpac, Macquarie, ING and Resimac, so a unit near the station, an established house and a new build can each be matched with a lender whose policy suits that security.
Read the full detail

Housing in Penrith itself is a mix of freestanding houses, townhouses and semis, and apartment blocks close to the station and the city centre. Around it, newer estates and house-and-land releases make up the release belt described above.

For a lender, a unit a few minutes’ walk from Penrith station is assessed on strata records, building size and internal area, and commuter demand helps an investor document the rent.

An established house on a full block is valued mainly on land and nearby sales. A house-and-land package brings the registration, fixed-price contract and staged drawdown questions covered above.

Links compares lenders such as ANZ, Westpac, Macquarie, ING and Resimac, so a unit near the station, an established house and a new build can each be matched with a lender whose policy suits that security.

Example scenario (illustrative, not a real client): A couple living with family in Glenmore Park are choosing between a townhouse a short walk from Penrith station and a house-and-land package in a newer estate nearby. The townhouse is a single settlement, with strata or community title records to check.

The package means land settling on registration and a build drawn down in stages. Comparing lender policies on both, including how each handles the 5% Deposit Scheme and progress payments, lets them decide on the real cost and timing.


Refinancing and releasing equity in Penrith

Owners of established Penrith houses often hold equity built over years, which can fund a move to a newer estate or a first investment.

What the equity is for shapes how a lender assesses it. A repricing request to your current lender costs nothing and comes first. Start with a loan health check.

A red-roofed house on a quiet street

How does investment lending work in Penrith?

About six in ten Penrith homes are rented, and commuter demand near Penrith station helps investors document rent.

Lenders count only part of the rent, and new estates rely on recent leases in the same release. Investment lending.

Valuations in Penrith: what moves the number

A unit near Penrith station is valued on building records and nearby sales, while an established house on a full block is valued mainly on land.

House-and-land packages are valued on the plans and again at completion. What to do about a low valuation.

Self-employed and professional borrowers in Penrith

Many Penrith buyers are tradespeople and contractors, and lenders differ on how they read ABN income and recent trading.

Some accept a shorter history with prior employment in the same field. Self-employed lending.

Build or buy built

Penrith's fork in the road, priced on both sides.

A brick bungalow with a tidy front lawn

First home buyers in Penrith

Penrith prices sit comfortably inside the first home supports’ caps.

  • The 5% Deposit SchemeThe $1.5 million cap clears essentially the entire Penrith market. Five per cent down, no lender's insurance, no income caps. Check eligibility.
  • Stamp duty at zeroThe $800,000 exemption covers a substantial share of Penrith houses, real duty, gone. Your figure.
  • First Home Owner Grant$10,000 on eligible new builds within the grant’s value caps, stackable where criteria align.
  • Help to Buy, liveShared equity from a 2% deposit inside its caps, an alternative to the 5% scheme at Penrith prices. Settings verified against your file.

Common questions about buying in Penrith

Is Penrith where the schemes work best?

It is certainly where they work most completely: the 5% cap clears the market, the duty exemption catches houses rather than just units, the grant applies to the new builds the release belt produces, and Help to Buy's caps fit local prices as an alternative to the 5% scheme. A Penrith first-home file can combine more support than most of Sydney.

Are units near Penrith station financed differently from houses?

Yes, because the security differs: a unit close to Penrith station is read on its strata report, building size, internal area and rental evidence, and commuter demand helps an investor show the rent.

A house is valued mainly on its land and nearby sales, and a new build in the release belt brings a fixed-price contract and progress payments. Your own assessment is the same either way, but the shortlist of suitable lenders can change.

What should I know before signing a house-and-land contract?

Three things: your finance capacity across both contracts plus contingency, verified before signing; the registration estimate's softness, plan around it, not on it; and the build contract's price-review and variation clauses, your solicitor reads them, your finance structure absorbs them. Signed in that order, packages behave. The full guide.

How does the airport corridor change buying here?

Infrastructure of that scale anchors long-term employment and demand, which is context, not a prediction, we don't forecast prices. What it concretely changes now is supply: more releases, more packages, more choice, and the same disciplines applying to each. Buy on today's numbers; let the corridor be upside.

Can my parents help without handing over cash?

Yes, a family guarantee uses their equity to close your deposit gap without money moving, released once your loan-to-value ratio clears the threshold. It is the west's other great deposit engine beside documented gifts, and done with a planned exit, it works exactly as intended.

Established Penrith or the new estates, which holds value better?

That is a prediction, and we don't sell those. What we can price is the present: land content versus build warranty, duty differences, grant eligibility, timing risk. Buyers who choose on today's verified numbers, and hold either kind for years, have history's better record. The calculator prices the present accurately.

Talk to a broker about your Penrith home loan

One free call covers what you could borrow in Penrith, the lenders that suit the property you want and the order to do things in.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.




