Quick repayment estimate
If things change
Principal and interest, constant rate, monthly repayments. An estimate only, not credit advice or an offer.
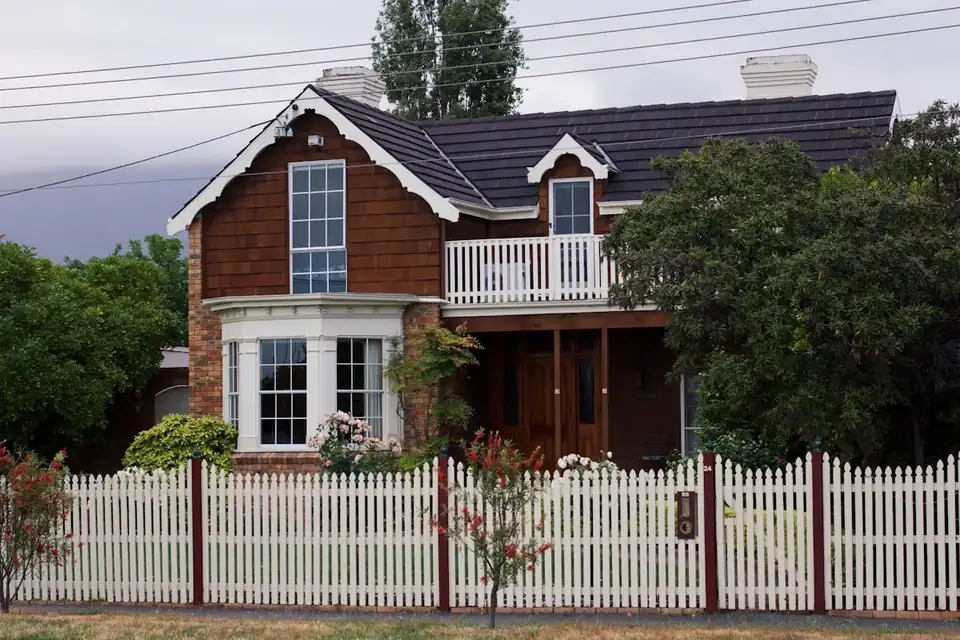
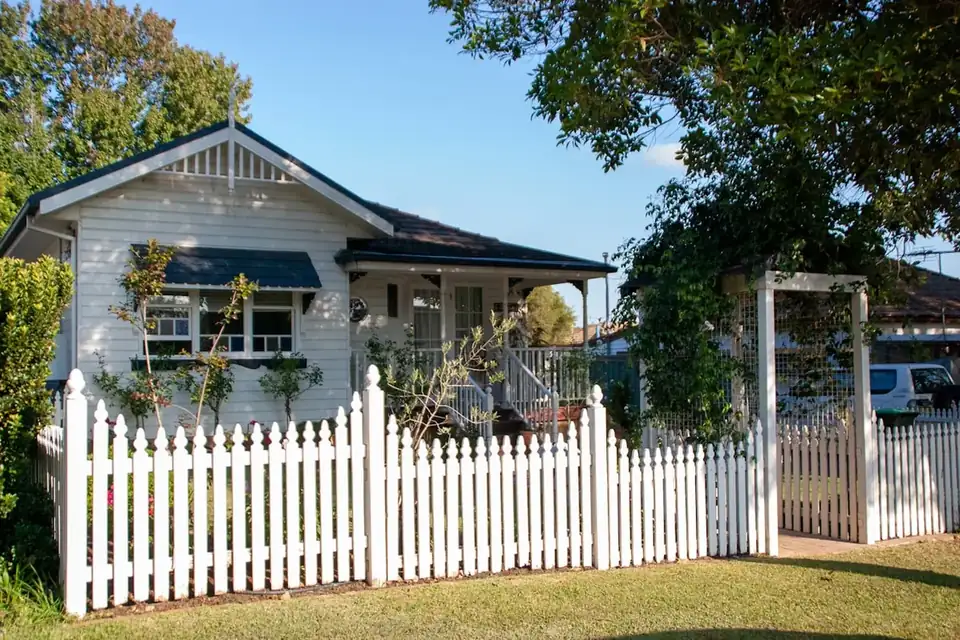
Canada Bay the suburb, not the council that borrowed its name, is a quiet strip of villas, townhouses and single-level homes along the bay walk.
Sometimes. Villas and townhouses here may be strata, community or Torrens title, which changes the levies you pay, the records you check and occasionally which lenders accept the property.
Torrens title homes are treated like houses; strata and community title add a levy figure to the borrowing test and a records check before exchange.

At 510 homes, Canada Bay is one of the smaller suburbs nearby, which can make a valuation the slowest part of the loan.
Separate housesTownhouses and semisApartments
apartments NSW 21.7%
separate houses NSW 65.6%
terraces and semis NSW 11.7%
rented NSW 32.6%
with a mortgage NSW 32.5%
private dwellings
Source: ABS Census 2021, Suburbs and Localities (SAL10784).

Quick repayment estimate
If things change
Principal and interest, constant rate, monthly repayments. An estimate only, not credit advice or an offer.
Confirm your numbers.
Charles and the team recently assisted us with a refinance of our investment property. Recommend Charles and the team to all
As a first home buyer, I was pretty overwhelmed at the start, but Charles made everything much easier. He explained the process step by step and helped me understand my borrowing options. His professionalism and responsiveness were excellent.
I found Charles and Links Property Finance very prompt and professional to deal with. Made it all so easy.


Canada Bay has no railway station or ferry wharf of its own, so its draw is the quiet streets beside the bay rather than a quick commute.
The main road through the suburb is Lyons Road West, and that matters at valuation: a home fronting the main road is compared differently from one in a quieter street near the water.
The suburb is small, so recent sales are few, and a valuer often has to draw evidence from neighbouring Concord and Five Dock.
Separate houses are the larger share of the stock, as the housing panel below shows, with villas, townhouses and apartments making up the rest, so title type comes up on many Canada Bay files.
A freestanding house on Torrens title carries no levies and the least paperwork. A villa or townhouse may be strata or community title, which adds levies to your expenses and the scheme’s records to the checks.
Title type also shapes the choice of lender, so Links checks it against a panel that takes in ANZ, Westpac, Macquarie, ING and Resimac before an application goes anywhere.
Example scenario (illustrative, not a real client): a couple selling a larger family house elsewhere in the Inner West want a single-level villa in Canada Bay before their sale settles.
The villa sits in a small strata scheme, one partner has recently retired, and the purchase needs bridging finance until the sale completes.
Lenders differ on bridging terms, on how retirement income is counted and on how they read a small scheme’s records, so setting those policies side by side shows whether the purchase can proceed before the couple commits to a settlement date.

The practical differences by title and form.
Small schemes, four to twelve dwellings, with modest levies and simple records. Lenders treat them close to houses; the strata report is shorter but still worth every page, especially insurance adequacy on older schemes.
No body corporate, no levies, no shared insurance: the cleanest lending profile there is. Party-wall and shared-driveway arrangements still deserve a conveyancer’s eye, but the finance is plain house lending.
Estate by-laws and association levies layer above your lot, and the combined levy figure enters serviceability. The community management statement is part of the purchase, read alongside the contract, not after it.
Villas attract downsizers competing with first buyers for the same stock, keeping the market firm. For finance, downsizers bring the asset-rich income-modest pattern, structures for that are on our Breakfast Point page and apply here identically.
Villas and older townhouses here sit where the schemes still function: within the 5% Deposit Scheme’s Sydney cap, often near the NSW duty relief lines. For buyers priced out of houses but wary of towers, a small-scheme villa is a different third option.
The first-home pathway, and the deposit compared three ways.
Low-maintenance villas let well to long-staying tenants, and small schemes avoid the investor-concentration questions towers attract. Standard investment assessment applies, discounted rent, higher rates, with the levy line depending on title type as above. How the assessment runs.
Torrens means you own land and dwelling outright, no levies, no shared insurance, the simplest assessment a lender does.
Strata means owning a lot in a scheme: levies enter serviceability and the scheme’s records enter due diligence. Both finance readily; they’re just different applications, and knowing which you’re buying shapes the numbers from the start.
Because the suburb is small, there are few recent sales of similar homes, and villas, townhouses and houses on the same handful of streets each need their own comparisons.
A valuer may draw on sales in Concord or Five Dock, and that evidence can pull the figure either way. Checking recent nearby sales yourself before you bid, and keeping some room in the budget for a shortfall, stops a cautious valuation becoming a problem at settlement.
Both, confusingly, the City of Canada Bay covers Concord, Drummoyne, Five Dock and more, while Canada Bay the suburb is the modest strip by the bay itself. Property listings usually mean the suburb; news usually means the council. We cover the lot either way.
Often, yes: lenders treat villas much like houses, levies are modest, and few of the size or density rules that complicate apartments apply. Supply is the constraint, so pre-approval matters more than usual when one lists.
Yes, lenders treat ongoing association levies as the permanent commitment they are, alongside any strata component. Get the combined figure in writing early; it belongs in your first borrowing estimate.
The sequence: know your sale-side equity, decide whether you’ll bridge or sell first, and structure any loan around income as lenders will count it, pension, super drawdown and investment income each have their own treatment. The structures are covered on our Breakfast Point page and translate directly.
Bring your Canada Bay plans to a free 30-minute call: your borrowing range, the lenders that fit the property and your next step.
Prefer a callback?
Charles calls back within one business day. No documents needed yet.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.