Call Charles Book a meeting
Mortgage Broker Sutherland Shire

Links Property Finance · Home loans across the Sutherland Shire: Mortgage Broker in the Sutherland Shire

The Shire is a self-contained market: Cronulla units, family houses, downsizers and first home townhouses.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

What does a Sutherland Shire purchase take to finance?

Financing a Sutherland Shire purchase depends on the property. Beachside units need a lender comfortable with the building and its strata record, family houses are valued on land and recent sales, and townhouses sit in between.

Read more

Downsizers moving within the Shire often need bridging finance, and parents helping children buy can use a family guarantee instead of cash.

An aerial view of a Sydney suburb

Recent Links clients, including a new build

  • Three Links Property Finance clients in front of the agent’s board at the home they bought Family buy · South West Sydney
    Bought, and all smiles. A family purchase in Sydney’s south-west.
  • Two Links Property Finance clients standing inside the timber frame of their new home Building · Sydney
    Their new home, at frame stage. Walls next. The frame is up.
  • Next one

    Buying in Sutherland Shire? Yours could be next.

    One short call tells you what you can borrow and what to do first.

    Book my free call

What would the repayments be?

Quick repayment estimate

Quick repayment estimate

$600,000
6.00%
30
Estimated repayment$3,597/mo≈ $1,660 per fortnight · total interest $695,029

If things change

Rate rises 1%$3,992/mo+$395 a month
25‑year term$3,866/mo+$269 a month, saves $135,287 interest
Lender’s test rate (+3%)$4,828/mowhat your budget is assessed at

Principal and interest, constant rate, monthly repayments. An estimate only, not credit advice or an offer.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles Touma from Links Property Finance was a great help with buying my first home. I had plenty of questions and he took the time to explain things clearly without making me feel rushed. He kept me updated throughout and made the process much less stressful. Really appreciated his patience and would happily recommend him to other first home buyers.
Catherine Google review
★★★★★
Had a really good experience with Charles at Links Property Finance. He was easy to deal with, always quick to respond and kept everything simple and clear throughout the whole process. You can tell he genuinely cares about getting the best outcome for his clients rather than just getting things done quickly. Really happy with the experience and would happily recommend Charles and Links Property Finance to anyone.
Christian Google review
★★★★★
I have had a number of dealings with Charles from Links Property Finance. He is very knowledgeable, thorough, and detailed with his advice. Importantly, he is very approachable and easy to deal with. His advice has been beneficial to myself and my acquaintances. I highly recommend him.
Joseph Google review

The Sutherland Shire in numbers

Across the 4 suburbs on this page, apartments are 50% of homes against 21.7% statewide, and 34% of households rent. That mix is why lender rules on strata, building size and postcode come up so often here.

38%

separate houses NSW 65.6% · highest Engadine (79.4%)

11%

terraces and semis NSW 11.7%

50%

apartments NSW 21.7% · highest Cronulla (72.5%)

34%

rented homes NSW 32.6% · highest Sutherland (42.4%)

33%

homes with a mortgage NSW 32.5%

29,277

private dwellings counted 4 suburbs on this page

Weighted by dwellings across the 4 suburbs this page covers. Source: ABS Census 2021, Suburbs and Localities.

Book my free call

Mortgage brokers in the Sutherland Shire: what to look for

Four things to ask any broker before you let them lodge an application for a home in the Sutherland Shire.

  • They should know the suburb, not just the postcode.Cronulla units, first home townhouses and downsizers moving from a family house each raise different lender questions in the Sutherland Shire. Each suburb listed has its own page.
  • They should choose the lender after reading your file.With more than 70 lenders on the panel, the right one depends on your income, your deposit and the property, so the choice comes last.
  • They should be clear about commission.You pay no broker fee on most loans, and the commission the lender pays is disclosed in writing before you commit.
  • They should stay with the loan, not just the purchase.A yearly rate review and help when a fixed rate ends are part of the service, from the person who arranged the loan.
Terrace houses along a tree-lined street

Sutherland Shire mortgage broker: who we help

The usual starting points for Sutherland Shire borrowers.

  • Checking your current rateIf the loan has not been looked at since settlement, it is probably time. Sometimes the fix is a repricing request, not a refinance. Free loan health check.
  • First home buyersWhether 5% is enough, whether duty applies, and what a lender will make of your savings history. First home buyer loans.
  • Buying an investmentHow a lender counts rent, what the monthly shortfall looks like, and whose name the loan should sit in. Investment property loans.
A Federation-era house with a tiled roof and front garden

Sutherland Shire suburbs, at a glance

MirandaCronullaSutherlandEngadine

Distances and councils from each suburb's published profile; housing mix from ABS Census 2021 dwelling structure. Each suburb links to its own page with the local lending detail.

Book my free call

A broker for the Shire's own market

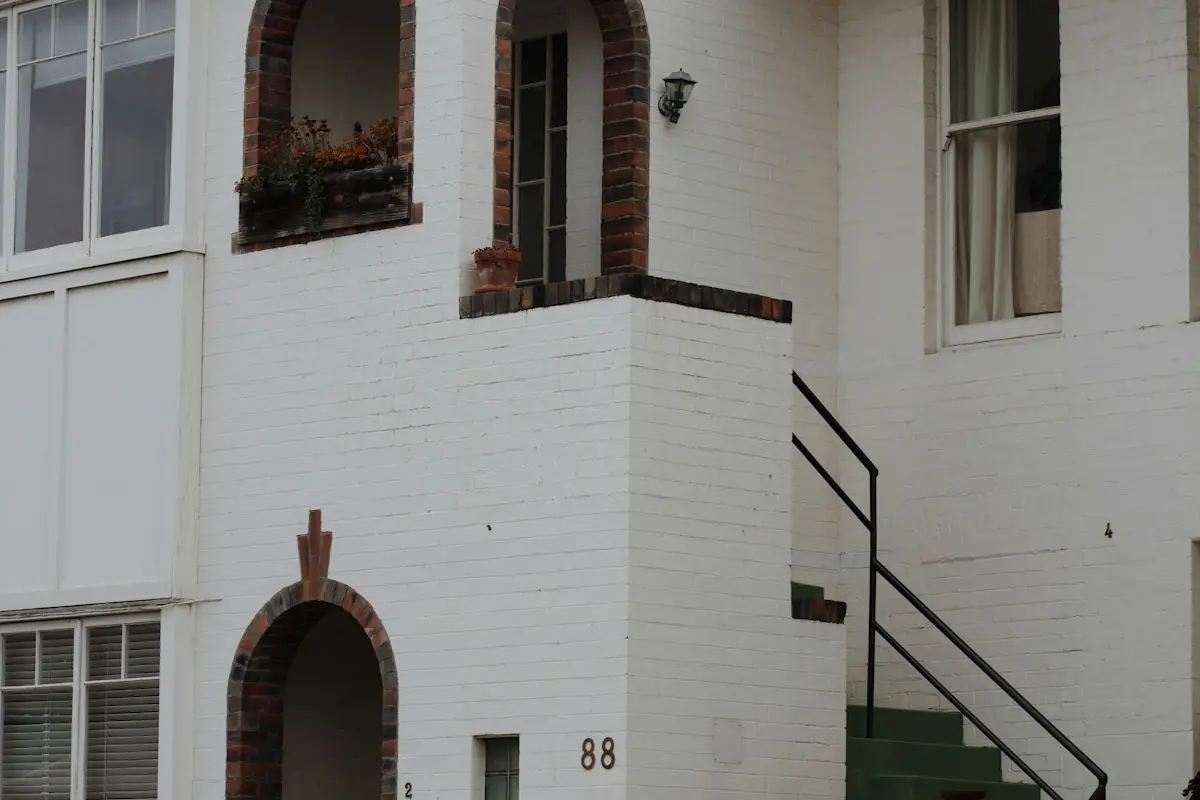
A white apartment block in Sydney
  • Links Property Finance works across the Sutherland Shire by phone, video and in person when it helps.The Shire trades with itself more than most regions, locals upgrading locally, parents helping children buy nearby, downsizers releasing house equity into beachside units, which gives its lending a distinctive shape: equity-rich, family-linked and sequenced.
  • The stock splits cleanly too: Cronulla's unit market with its own beachfront economics, the family-house heartland through Miranda, Gymea and Sutherland, and townhouse belts that serve as the Shire's first-home gateway.

Equity moving between generations

A family together in their backyard
  • Decades of Shire ownership built serious equity, and the region's signature lending moves it around: guarantees launching first purchases, documented gifts closing deposit gaps, and downsizer sales releasing capital that funds the next generation's start.
  • Each instrument is routine when structured, exits planned on guarantees, paperwork done on gifts, and surplus equity given a deliberate home.That structure is the work we do before any application.

From Sutherland station to Cronulla and Port Hacking

The Shire’s rail spine runs south from the city to Sutherland station, where it splits: one branch heads east through Miranda to Cronulla, and the main line continues south through Engadine towards the Illawarra. At Cronulla, a ferry crosses Port Hacking.

Unit and townhouse stock gathers around the stations, including Cronulla, Miranda and Sutherland, so that is where a lender checks strata records, apartment size and how many loans it already holds in the complex. Those precincts also give investors the nearby rents a lender asks to see.

Who do you deal with in Sutherland Shire?

His background in residential real estate means family guarantees, beachside units and Shire houses are familiar ground.

More about Charles · What clients say.

Houses stepping down to Sydney Harbour

How does it run?

One. A conversation. Thirty minutes, no documents needed. Your income, savings and who in the family may help.

  • Two. The lender question. Guarantee terms and how they are released differ between lenders, so the file goes to one whose policy suits the whole family.
  • What follows. Paperwork and a pre-approval, then the Sutherland Shire contract, the valuation and settlement day. Files stall on missing documents far more often than on income, so the list comes early. Floor area under 50 square metres, a thin sinking fund or a defect history can all narrow the lender list for a unit; see the small apartment guide. Book a call or call 0423 952 184.

What does the Sutherland Shire market mean for a loan?

Freestanding homes, townhouses and coastal unit stock, with a strong family and upgrader market and pockets of newer development.

  • Upgrader timing and equity release dominate. Coastal and waterfront properties bring their own valuation and insurance questions, and the newer townhouse stock raises the usual strata considerations.
  • These are not reasons to look elsewhere. They are reasons to match the lender to the property, since the same application can pass easily with one lender and fail with the next, and policies are revised regularly.
A brick house with a gabled roof

Who do we work with across the Sutherland Shire?

First home buyers. Shire first buyers often start with a unit or townhouse near Sutherland, Miranda or Cronulla station, often with family help towards the deposit. First home buyer guidance · Check the 5% scheme.

  • Upgraders. Upgrading to a family house in the Shire, or downsizing to a Cronulla unit, usually means timing a sale and a purchase in the same local market. Bridging finance · Usable equity.
  • Investors. Units near the Shire’s stations give investors nearby rental evidence, and lenders check how many loans they already hold in each complex. Investment lending.
  • Refinancers. Long-held Shire loans are often priced above current offers. Asking for a review costs nothing and frequently closes the gap. Free loan health check.
A blue-roofed house with a front path

Common questions about buying in the Sutherland Shire

Why does the Shire feel like its own property market?

Because it functions as one: high local loyalty means buyers and sellers are often the same families at different life stages, stock moves between generations, and demand is structurally local.

Does being near Cronulla, Miranda or Sutherland station change a Shire loan?

For owner-occupiers it mostly shapes the price, not the policy. Further from the rail line the stock is mainly houses, where the assessment turns on land and condition; either way, the building or block is checked before the lender is chosen.

I'm downsizing from a family house to a Cronulla unit. What's the smart sequence?

Usually sell first, buy with certainty, and give the surplus equity a deliberate destination, offsetting a remaining loan, funding family help, or structured savings. Bridging exists if the perfect unit appears before your sale.

How do Shire parents typically help their kids buy?

Two instruments: the family guarantee, equity securing the deposit gap without cash moving, released when the ratio clears; and the documented gift, cash with a signed non-repayable letter and clean transfer trail.

Are the beachfront Cronulla towers financed like normal units?

Mostly, with beachfront wrinkles: premium price points reaching larger-loan tiers, strata schemes with coastal maintenance profiles, and valuations that respect the front's scarcity but move with it. The strata record and the lender's appetite for the building both get read before you offer.

Talk to a broker about your Sutherland Shire home loan

One free call covers what you could borrow in Sutherland Shire, the lenders that suit the property you want and the order to do things in.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together

Sutherland Shire areas we cover

Each suburb page covers the property stock, the lending questions it raises and the tools worth running before you look.

Other Sydney regions we help

Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.