
Call Charles Book a meeting
Mortgage Broker Kingsgrove

Links Property Finance · Home loans in Kingsgrove and across Sydney: Mortgage Broker in Kingsgrove

More than eight in ten Kingsgrove homes are separate houses, and its median age is one of the older ones in the area.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Borrowing later in your working life in Kingsgrove: what do lenders ask?

How the loan will be repaid if the term runs past your expected retirement. Lenders ask for an exit strategy, such as downsizing, selling an investment, super or extra repayments, and may shorten the term. Strong equity in a long-held Kingsgrove house usually helps.

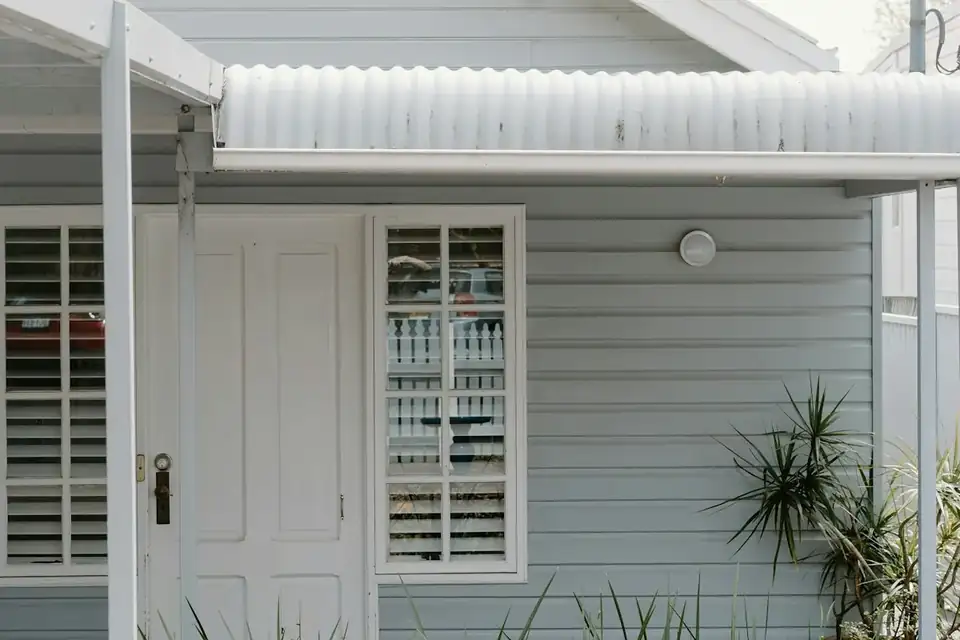
A weatherboard house with a white picket fence
Of Kingsgrove's homes, 82.0% are houses, 8.0% terraces and semis and 8.9% apartments (ABS Census 2021).

The housing mix in Kingsgrove

Kingsgrove is house country: 82.0% of dwellings are freestanding, against 65.6% for NSW. A house on its own title is the simplest security a lender takes, and the land carries most of the value.

  • Postcode2208
  • CouncilBayside Council
  • From the Sydney CBD13 km south west
8.9%

apartments NSW 21.7%

82.0%

separate houses NSW 65.6%

8.0%

terraces and semis NSW 11.7%

25.8%

rented NSW 32.6%

30.5%

with a mortgage NSW 32.5%

4,694

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL12166).

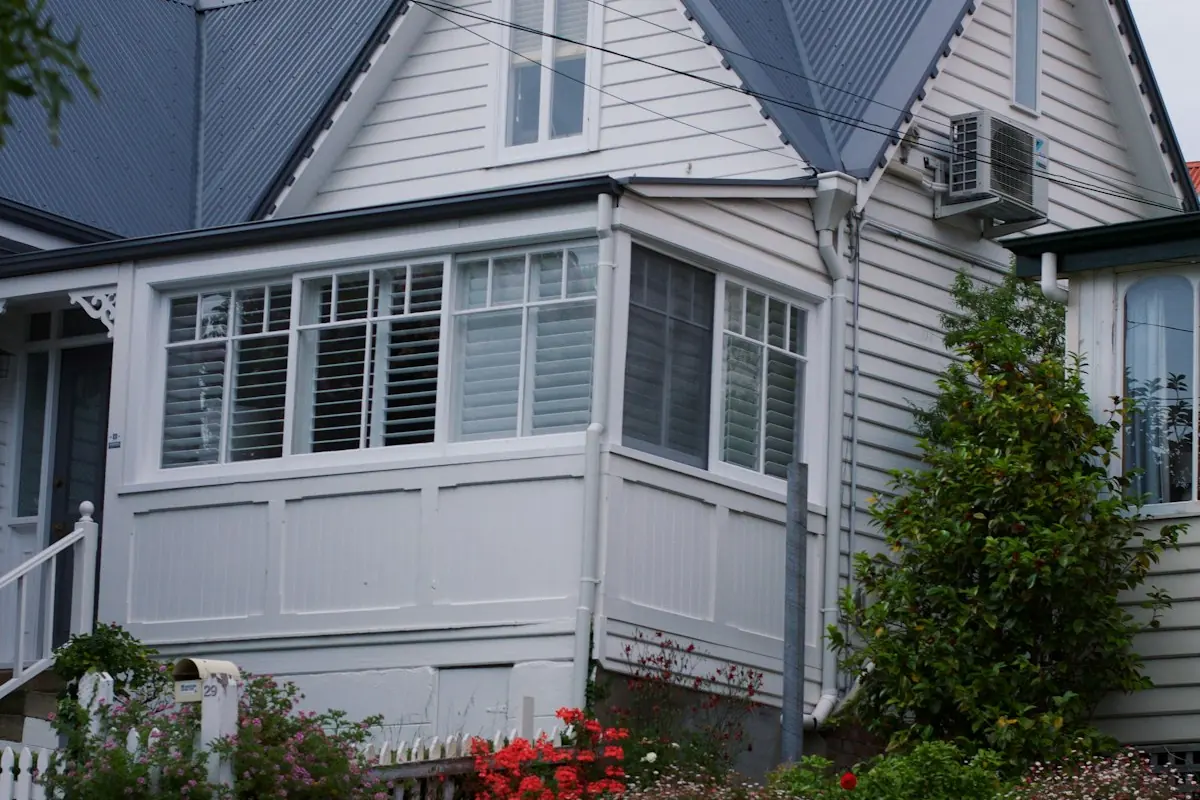
A brick house with a gabled roof

Guarantor sums for Kingsgrove

Quick guarantor check

Two sliders. See what your parents would need to guarantee.

Guarantor calculator

How a parent’s equity can stand in for the deposit, often with no LMI.

$800,000
$30,000
  • 20% deposit + costs target$163,500
  • Guarantee needed from family$133,500

With a family guarantee covering that portion, you could potentially buy with your $30,000 and no LMI. Costs assume NSW first home buyer duty.

Limited to this portion, secured against the guarantor’s property, released once you reach 20% equity, subject to lender approval. Indicative only, not credit advice.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles Touma from Links Property Finance was a great help with buying my first home. I had plenty of questions and he took the time to explain things clearly without making me feel rushed. He kept me updated throughout and made the process much less stressful. Really appreciated his patience and would happily recommend him to other first home buyers.
Catherine Google review
★★★★★
A huge thank you to Charlie for his exceptional support and expertise throughout the process of securing finance for my first home.
Julian Google review
★★★★★
Had a great experience with Charles at Links Property Finance. He made the whole home loan process straightforward and easy to understand, kept me updated throughout and was always quick to answer any questions.
Louie Google review

Borrowing later in your working life in Kingsgrove

Age by itself does not stop you getting a loan, but responsible lending means a lender must consider whether you can repay it.

If the term runs past the age you expect to retire, most lenders ask for an exit strategy: how the loan will be repaid, or reduced to something manageable, when your working income stops. Our guide to home loans for retirees covers what lenders accept.

Common exit strategies include downsizing, selling an investment property, using super, or paying the loan down faster before retirement. A shorter term with higher repayments can also work. The lender wants the plan to be realistic and documented, not just stated. Complex lending in detail

Terrace houses along a tree-lined street

Established owners in Kingsgrove

A Sydney house with a front verandah
  • Links Property Finance is based in Enfield, about fifteen minutes from Kingsgrove, with conversations by phone, video or in person.The first one is about your plans for the next ten or twenty years.
  • More than eight in ten Kingsgrove homes are separate houses, and about a quarter are rented.Many owners here have held their homes for years and are planning the next stage.

What do lenders ask about retirement?

A family on the porch of their home
  • When you expect to stop working.The lender compares that with the loan term.
  • How the loan will be repaid.Downsizing, selling an asset, super or faster repayments, explained and supported.

Kingsgrove Road, the railway and Kingsgrove housing

Kingsgrove lies about thirteen kilometres south-west of the city and spreads across the City of Canterbury-Bankstown, Bayside Council and Georges River Council. Parks include Beaumont Park and Dowsett Park.

Its main shopping centre is on Kingsgrove Road, south of Kingsgrove railway station, with commercial and industrial buildings north of the line and a small group of shops on Stoney Creek Road known as Kingsway.

  • In 1804 Governor King granted five hundred acres to Hannah Laycock, wife of Quartermaster Thomas Laycock, and she named the farm King’s Grove in his honour.
  • When a Kingsgrove owner is borrowing later in life, Links compares a panel that includes Westpac, ANZ, Macquarie, ING and Resimac.
Read the full detail

In 1804 Governor King granted five hundred acres to Hannah Laycock, wife of Quartermaster Thomas Laycock, and she named the farm King’s Grove in his honour.

Her sons were granted land nearby, and by 1829 the farm extended from Campsie and Clemton Park to Stoney Creek Road when it was sold to Simeon Lord. Today separate houses make up more than eight in ten homes in Kingsgrove.

When a Kingsgrove owner is borrowing later in life, Links compares a panel that includes Westpac, ANZ, Macquarie, ING and Resimac.

Example scenario (illustrative, not a real client): a Kingsgrove couple in their mid-fifties want to borrow to renovate the family home, with a term that would run past their planned retirement.

Before applying, they set out their exit strategy, which is to downsize in their sixties, and apply with a shorter term and repayments they can meet from their current incomes.

What counts as an exit strategy?

Lenders generally accept a clear plan such as selling the home and downsizing, selling an investment property, using super at retirement, or reducing the loan through higher repayments before you stop work. Each lender has its own view of what it will accept.

Evidence helps: a statement of your super balance, details of an investment property, or a repayment plan that clears most of the loan before retirement. Complex lending.

A brick bungalow with a tidy front lawn

A shorter term instead

Choosing a term that ends near your planned retirement means higher repayments, but it can remove the need for an exit strategy altogether. The lender then assesses whether your income supports those higher repayments.

Extra repayments and an offset account can help you reach the same result more flexibly. See what extra repayments save.

Helping children with equity

Owners with equity sometimes help adult children buy, through a guarantee or by borrowing against their own home. Either option affects your own finances and your plans for retirement.

It is worth understanding the risks, and getting independent advice, before committing your home to someone else’s loan. Guarantor home loans.

Downsize, sell or repay sooner?

Three common exit strategies, and what each means for the loan.

  • Downsize. Sell the family home and buy something smaller. Lenders want the plan to be realistic for your situation.
  • Sell an asset. Sell an investment property or other asset at retirement. Details of the asset support the plan.
  • Repay sooner. A shorter term, or higher repayments before retirement. Assessed on your current income.

What should I check before borrowing later in life?

The details that make the application straightforward.

  • Your retirement ageWhen you realistically expect to stop working.
  • Your superA recent statement of the balance.
  • Other assetsInvestment properties or savings.
  • The loan termWhether a shorter term is affordable.
  • The purposeRenovating, upgrading or helping family.
  • Independent adviceEspecially before a guarantee or large new loan.

Common questions about borrowing in Kingsgrove later in life

Am I too old to get a home loan?

No, age alone does not rule you out. Lenders must be satisfied you can repay, and if the term runs past your expected retirement, they will ask how the loan will be repaid.

What is an exit strategy?

An exit strategy is a realistic plan for repaying or reducing the loan when your working income stops, such as downsizing, selling an investment property or using super.

Can I get a thirty-year loan in my fifties?

Sometimes: some lenders allow it with a documented exit strategy, while others prefer a shorter term. Your income, assets and plans all come into it.

Does a shorter term help?

It can. A term ending near retirement means higher repayments, but it may remove the need for an exit strategy. The lender assesses whether your income supports the higher repayments.

Can I use super as my exit strategy?

Yes, many lenders accept super as part of the plan, supported by a recent statement, if the balance is realistic for the amount involved.

Can I borrow to renovate the family home at this stage?

Often, yes, with the same questions about repayment. Renovation loans may also involve quotes and approvals for the work.

Talk to a broker about your Kingsgrove home loan

Thirty minutes with Charles: what you could borrow, which lenders suit Kingsgrove property and what to do next. Free, with no credit check.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.