





Call Charles Book a meeting
Mortgage Broker Enmore

Links Property Finance · Home loans in Enmore and across Sydney: Mortgage Broker in Enmore

Nearly half of Enmore’s homes are semis or terraces and about half are rented, in a suburb built around the Enmore Road strip.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Freelance, casual or contract income in Enmore: how do lenders read it?

On history and consistency. Lenders usually want six to twelve months for casual income, two years of tax returns for freelancers, and a current contract and history in the field for contractors.

Read more

Payslips, invoices and bank statements that match each other make the most of what is counted.

Terrace houses along a tree-lined street
In Enmore, houses make up 17.3% of homes, terraces and semis 46.2% and apartments 32.3% (ABS Census 2021).

How a lender reads an address in Enmore

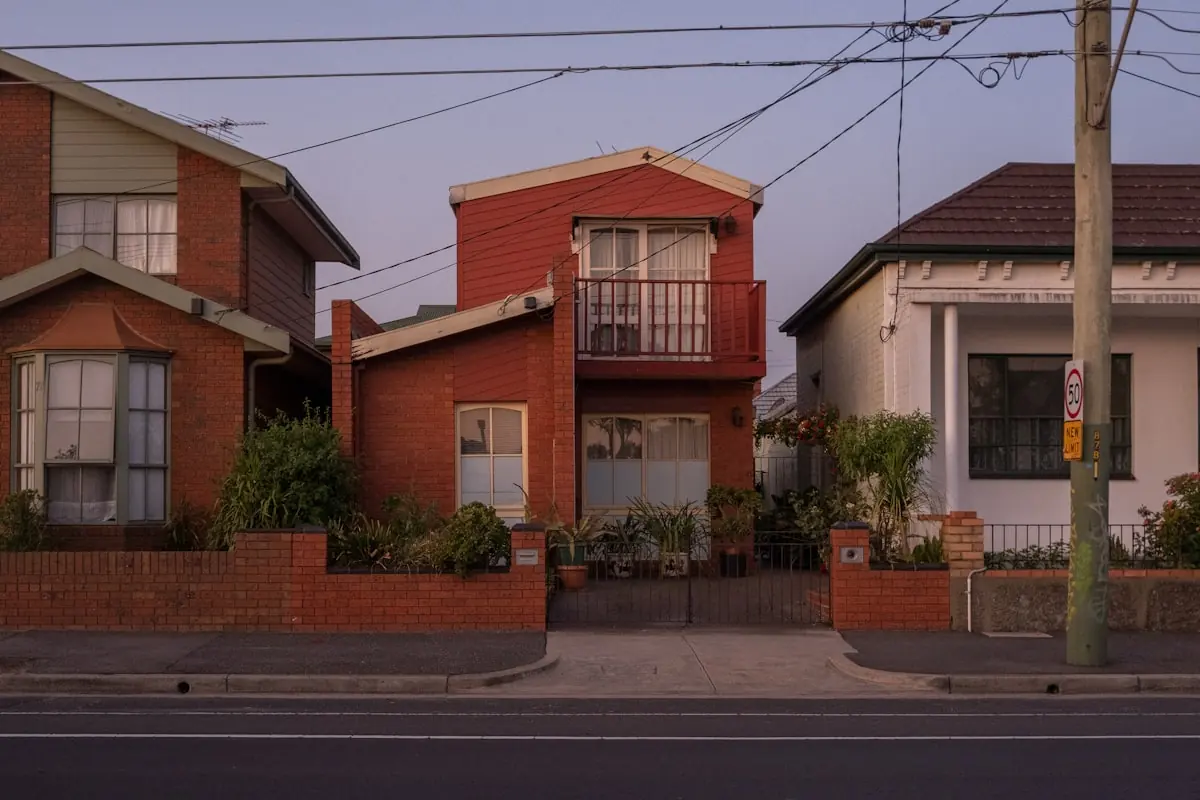
46.2% of dwellings here are attached houses, the terrace and semi stock that defines these streets. Heritage controls on some streets limit what can be changed, which matters if the plan is to renovate with the loan.

49.5% of homes here are rented, against 32.6% across NSW. For an investor that means a deep rental market, and an agent’s rental appraisal is easy to get when a lender asks. With only 1,829 dwellings, Enmore sees few sales in any year, and valuers sometimes reach into neighbouring suburbs for evidence.

  • Postcode2042
  • CouncilInner West Council
  • From the Sydney CBD5 km south west
32.3%

apartments NSW 21.7%

17.3%

separate houses NSW 65.6%

46.2%

terraces and semis NSW 11.7%

49.5%

rented NSW 32.6%

29.3%

with a mortgage NSW 32.5%

1,829

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL11428).

A brick house with a gabled roof

How much could you borrow for Enmore?

How much could you borrow?

$140,000
None

What moves the number

Choose any that apply. Each shows roughly how much it changes the figure, the way a lender’s assessment would.

$635,000

is an indicative borrowing figure at today’s typical rates. Lenders typically count around 80% of rental income, which is why an investment purchase can lift your number, your real figure comes from a proper assessment.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles and the team at links property finance recently assisted me with my purchase of my first property in Burwood. As a first home buyer, Charles made the process simple and easy. I would recommend Charles to all first home buyers
Elijah Google review
★★★★★
Charles and the team recently assisted us with a refinance of our investment property. Recommend Charles and the team to all
Tony Google review
★★★★★
I found Charles and Links Property Finance very prompt and professional to deal with. Made it all so easy.
Marg Google review

Irregular income and borrowing in Enmore

Lenders are not against irregular income, but they want to see that it is likely to continue. For casual employees that usually means a period in the job or the industry, often six to twelve months, with payslips showing steady hours.

For freelancers and sole traders it usually means tax returns, often for the last two years, though some lenders accept one.

The same income can be read differently by different lenders: one may average two years, another may use the most recent year if it is higher and consistent.

Presenting it clearly, with the documents a particular lender wants, often matters as much as the income itself. How income is assessed

A corner cottage with a hedge

Freelancers and casuals in Enmore

A row of red-brick terraces in Sydney
  • Links Property Finance is based in Enfield, with conversations by phone and video at hours that suit shift and freelance work.The first one is about how you earn and what records you already have.
  • Nearly half of Enmore’s homes are semis or terraces, about four times the New South Wales share.Most are on their own title, so the property is usually the simpler half of the application.

What do lenders look for in irregular income?

A cafe owner at the counter of her business
  • A track record long enough to rely on.Casual workers usually need months in the role or industry, and self-employed borrowers usually need a year or two of tax returns.
  • Consistency, or a clear reason for any change.A rise, a dip or a gap is fine if it can be explained and the current income is sustainable.

Enmore Road, King Street and Enmore housing

Enmore lies about five kilometres south-west of the city in Inner West Council, sharing postcode 2042 with Newtown. It is mainly residential, with its commercial strip along Enmore Road, which turns off King Street.

The former Enmore Post Office, built in 1895 on the corner of Enmore and Stanmore Roads, was designed by the government architect Walter Vernon and is listed on the Register of the National Estate as an example of Federation Queen Anne architecture.


Casual employment

Casual employees can borrow, often on a similar basis to permanent staff, if the hours are regular and there is enough history. Many lenders look for six to twelve months in the role or the same line of work.

Recent payslips and a year-to-date figure are the usual evidence, sometimes with the last tax return.

A house with a wide front verandah

Freelancers and sole traders

For self-employed income, lenders usually want personal tax returns and notices of assessment for the last one or two years, plus business financials if you trade through a company or trust.

Some accept one year of returns if you have a longer history in the same field.

Where tax returns are not yet lodged, some lenders offer alternative documentation loans using business activity statements or an accountant’s letter, usually with a larger deposit or a higher rate. Self-employed lending explained.

Contractors on day rates

Contractors paid a day or hourly rate through an agency or their own company are assessed in different ways. Some lenders annualise the current contract rate, particularly for professionals with an established history in their field.

Others treat contractors like self-employed borrowers and ask for tax returns.

A current contract, evidence of past renewals and a history in the same field all help. The difference between lenders can be large, so the choice of lender matters as much as the rate. Home loans for contractors.

Casual, freelance or contract?

Three ways of earning that come up in Enmore, and what each means for the loan.

  • Casual. Regular hours and time in the role or industry are the main tests. Payslips and a year-to-date figure are the usual evidence.
  • Freelance. Tax returns and notices of assessment, usually for one or two years. Alternative documentation is possible with some lenders, often at a cost.
  • Contract. Some lenders annualise the current rate, while others ask for tax returns. A current contract and a history of renewals help.
A terrace with an iron-lace balcony

What should I check before buying in Enmore?

The groundwork that lets irregular income count.

  • Your tax returnsThe last two years, with notices of assessment, if you are self-employed.
  • Recent payslipsSeveral months, with year-to-date totals, if you are casual or on contract.
  • Your contractA copy of any current contract, and evidence of past renewals.
  • Business statementsRecent statements for any business account you use.
  • An explanationA short note on any dip, gap or change in how you earn.
  • Every debt and limitCards, car loans, buy now pay later and any HECS or HELP balance.

Common questions about buying in Enmore

Can I get a home loan as a casual worker?

Yes, many casual employees do. Lenders usually look for regular hours and a period in the role or the same line of work, commonly six to twelve months. Payslips and a year-to-date figure are the usual evidence, and some lenders are more flexible than others about shorter histories.

How many years of tax returns do I need as a freelancer?

Commonly two years, with notices of assessment, though some lenders accept one year if you have a longer history in the same field. Where returns are not lodged yet, alternative documentation loans may be available, usually with a larger deposit or a higher rate.

My income went up this year. Will the lender use the higher figure?

Some will, if the increase is consistent and supported by your records. Others average the last two years, which can lower the figure. That difference is one of the main reasons to match your application to the right lender.

Do contractors need two years of tax returns?

Not always. Some lenders assess contractors by annualising their current contract rate, particularly for professionals with an established history in their field. Others treat contractors as self-employed and ask for tax returns. The contract, its term and your history all come into it.

Can I combine a salary with freelance income?

Yes. The salary is assessed from payslips, and the freelance income usually from tax returns. Some lenders count only part of side income or want a longer history of it, so the salary often carries more weight in the calculation.

Does a gap between jobs hurt my application?

Not usually, if it was short and explained: lenders look at whether your current income is stable and likely to continue. A long gap, or a recent move into a new industry, can mean a lender wants a little more history first.

Talk to a broker about your Enmore home loan

Bring your Enmore plans to a free 30-minute call: your borrowing range, the lenders that fit the property and your next step.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.




