
Call Charles Book a meeting
Mortgage Broker Mount Lewis

Links Property Finance · Home loans in Mount Lewis and across Sydney: Mortgage Broker in Mount Lewis

Mount Lewis is a small suburb of fewer than four hundred homes, and more than eight in ten are separate houses.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Paying off your Mount Lewis home faster: offset, extra repayments or redraw?

An offset saves interest on money you can still use; extra repayments save the same interest but are harder to get back on some loans; redraw lets you withdraw extra repayments, with conditions.

Read more

If you may need the money, or the home may become an investment, an offset is usually the better choice.

A brick bungalow with a tidy front lawn
In Mount Lewis, houses make up 85.2% of homes, terraces and semis 12.5% and apartments 0.8% (ABS Census 2021).

Mount Lewis by its homes

Mount Lewis is mostly detached homes, 85.2% of everything built here. Owners here often build equity faster than they expect, which opens a top-up, a renovation or help for family later. Mount Lewis is small, at 389 private dwellings, so comparable sales are thin and a valuation can be harder to predict.

  • Postcode2190
  • CouncilCity of Canterbury-Bankstown
  • From the Sydney CBD18 km south west
0.8%

apartments NSW 21.7%

85.2%

separate houses NSW 65.6%

12.5%

terraces and semis NSW 11.7%

30.4%

rented NSW 32.6%

31.8%

with a mortgage NSW 32.5%

389

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL12785).

A row of red-brick terraces

Refinancing a Mount Lewis home loan: the saving

Calculate your savings

$550,000
6.40%
25
6.00%

Example rates only, not current advertised rates. Set both sliders to your own figures.

Interest at 6.40%Interest at 6.00%
You could save$40,706≈ $1,628 a year in repayments
Current repayments$3,679/month
New repayments$3,544/month

Over the remaining term, before switching costs and fees, we model those before recommending a move. Estimates only, not credit advice.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles and the team at links property finance recently assisted me with my purchase of my first property in Burwood. As a first home buyer, Charles made the process simple and easy. I would recommend Charles to all first home buyers
Elijah Google review
★★★★★
Paperwork and finances were never my strong suit. He has made this process as simple and dummy proof for me as humanly possible. This is not the first time I use a mortgage broker, however it was the easiest and most pleasant.
Mikhail Google review
★★★★★
Charles went above and beyond to help us secure our home loan. He worked hard to find the best option for us and kept us updated throughout the whole process. His knowledge of the lending market was impressive and he made everything straightforward.
Anthony Google review

Offset, extra repayments and redraw in Mount Lewis

An offset account is a transaction account linked to your loan, and its balance reduces the amount you pay interest on while keeping the money available. Extra repayments go straight into the loan, reducing the balance, and on many variable loans you can take them back out through redraw.

Both reduce interest in a similar way. The difference is flexibility and structure: offset money stays yours to spend, while redraw rules are set by the lender and can change.

If the home might later become an investment, how you have used the loan can matter for tax, so it is worth asking your accountant before choosing. Offset accounts in detail

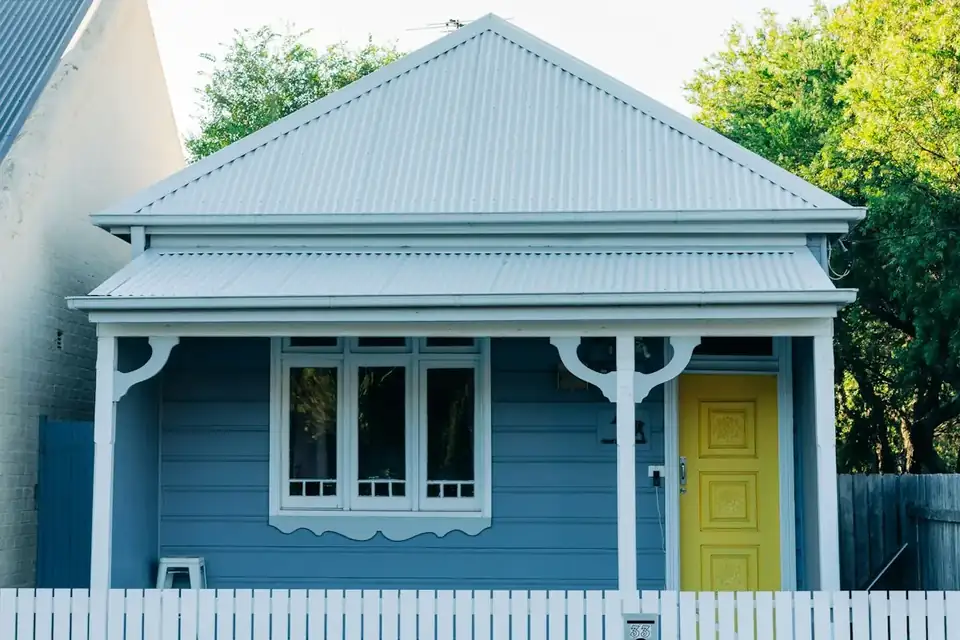
A blue weatherboard cottage

Family houses in Mount Lewis

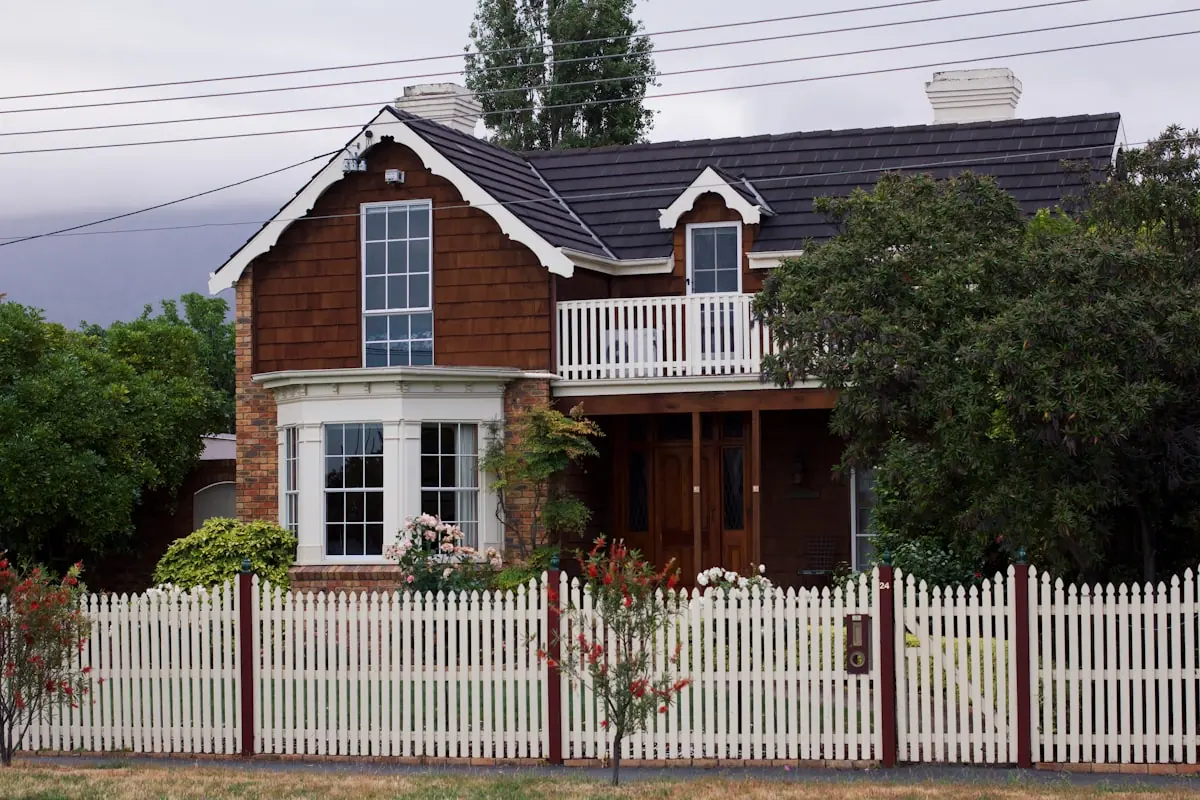
A Sydney house with a picket fence
  • Links Property Finance is based in Enfield, about ten minutes from Mount Lewis, with conversations by phone, video or in person.The first one is about your loan today and what you want from it.
  • More than eight in ten Mount Lewis homes are separate houses, and about a third are owned with a mortgage.For many owners here, the goal is paying the family home off sooner.

Offset or extra repayments

A first home buyer working through their numbers at the kitchen table
  • Offset keeps savings available.The balance reduces interest, and the money stays in your account.
  • Extra repayments reduce the loan.The balance falls directly, with access through redraw on many variable loans.

Wattle Street, the reserve and Mount Lewis housing

Mount Lewis lies about eighteen kilometres south-west of the city by its official measure, in the City of Canterbury-Bankstown, and shares postcode 2190 with Greenacre and Chullora.

It is a mostly residential suburb with a few shops and commercial buildings on Wattle Street, and Mount Lewis Bowling Club on Waterloo Road.

  • The suburb takes its name from the highest point in the district, at Mount Lewis Reserve on Wattle Street.
  • When a Mount Lewis owner is reviewing a loan, Links compares a panel that includes ANZ, Westpac, ING, Macquarie and Resimac.
Read the full detail

The suburb takes its name from the highest point in the district, at Mount Lewis Reserve on Wattle Street. The origin of the name is unclear, but the height gives views west towards Bankstown, south towards Canterbury Road and east to the city skyline.

Thomas Collins acquired fifty acres of land here in the 1830s. Today fewer than four hundred private dwellings make up the suburb, almost all of them separate houses.

When a Mount Lewis owner is reviewing a loan, Links compares a panel that includes ANZ, Westpac, ING, Macquarie and Resimac.

Example scenario (illustrative, not a real client): a Mount Lewis couple have savings sitting in an everyday account and a variable home loan without an offset.

They compare moving to a loan with an offset account against making extra repayments, check what redraw their current lender allows, and choose an offset so the savings reduce interest while staying available.


How does an offset account work?

Every dollar in a linked offset account reduces the balance the lender charges interest on. Your repayments stay the same, but more of each one goes to the principal, so the loan is repaid sooner.

Some loans with offset carry a higher rate or a package fee, so compare the whole cost rather than the feature alone. Estimate your offset savings.

A house with a wide front verandah

Extra repayments and redraw

Paying more than the minimum reduces the loan directly. On many variable loans the extra can be taken back through redraw, although lenders set their own rules, including minimum amounts and whether access can be limited.

Fixed rate loans usually cap extra repayments during the fixed period, and some charge fees above the cap. See what extra repayments save.

What if the home may become an investment?

If you might move out and rent the house later, how you have used the loan can affect what interest is deductible. Money redrawn from a loan and money withdrawn from an offset are treated differently for tax.

This is a question for your accountant, and it is worth asking before you decide how to structure the loan. Managing your home loan.

From first conversation to a better setup

Stage one. Your loan today. Your rate, balance, features and savings. No documents are needed for this part.

  • Stage two. The options. An offset, extra repayments, or a different loan, compared on your figures.
  • Stage three. Your lender first. Sometimes the existing lender can add an offset or sharpen the rate.
  • Stage four. A switch, if it helps. If moving is better, the new loan is arranged and the old one paid out. Book a call or call 0423 952 184.

Offset, extra repayments or both?

Three ways to get ahead on the loan, and what each means.

  • Offset. Savings reduce interest and stay available. Check any higher rate or package fee.
  • Extra repayments. The loan balance falls directly. Redraw rules are set by the lender.
  • Both. Extra repayments plus an offset for savings. Common on variable loans with good features.
A terrace with an iron-lace balcony

What should I check before changing how you repay?

The details that decide which option suits.

  • Your loan typeFixed, variable or split, and any limits.
  • Your savingsHow much you keep and how often you use it.
  • FeesPackage fees, offset fees and redraw fees.
  • Your rateWhether it is still competitive.
  • Future plansWhether the home may one day be rented.
  • Accountant adviceOn tax, if the home could become an investment.

Common questions about paying off a Mount Lewis home

Is an offset account better than extra repayments?

Neither is better in general: both save interest in a similar way. An offset keeps your money available and separate; extra repayments reduce the loan directly and rely on redraw for access.

Can I make extra repayments on a fixed rate loan?

Usually only up to a limit during the fixed period, and some lenders charge fees above it. A split loan can give you a variable portion for extra repayments.

Does an offset account reduce my repayments?

Not usually. Your repayment stays the same, but more of it goes to the principal, so the loan is paid off sooner.

What is redraw?

Redraw lets you take back extra repayments you have made on a variable loan. Lenders set the rules, including minimum amounts, and can change them.

Can my existing lender add an offset account?

Sometimes, by switching you to a different product. Asking your lender is a sensible first step before refinancing.

Does it matter for tax if I rent the house out later?

It can. Redrawn money and offset withdrawals are treated differently for tax, so ask your accountant before deciding how to structure the loan.

Talk to a broker about your Mount Lewis home loan

Thirty minutes with Charles: what you could borrow, which lenders suit Mount Lewis property and what to do next. Free, with no credit check.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.