Call Charles Book a meeting
Mortgage Broker Bardwell Valley

Links Property Finance · Home loans in Bardwell Valley and across Sydney: Mortgage Broker in Bardwell Valley

Bardwell Valley is a small residential suburb where two in three homes are houses, more than a quarter are semis, and fewer than one in five is rented.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Buying in Bardwell Valley with a past credit problem: what will lenders accept?

More than most people expect. A small, paid default or a few late payments, a couple of years old and explained, passes with some mainstream lenders; larger or recent issues move the file to specialist lenders at a higher rate.

Read more

Reading your credit report first decides which group to apply to.

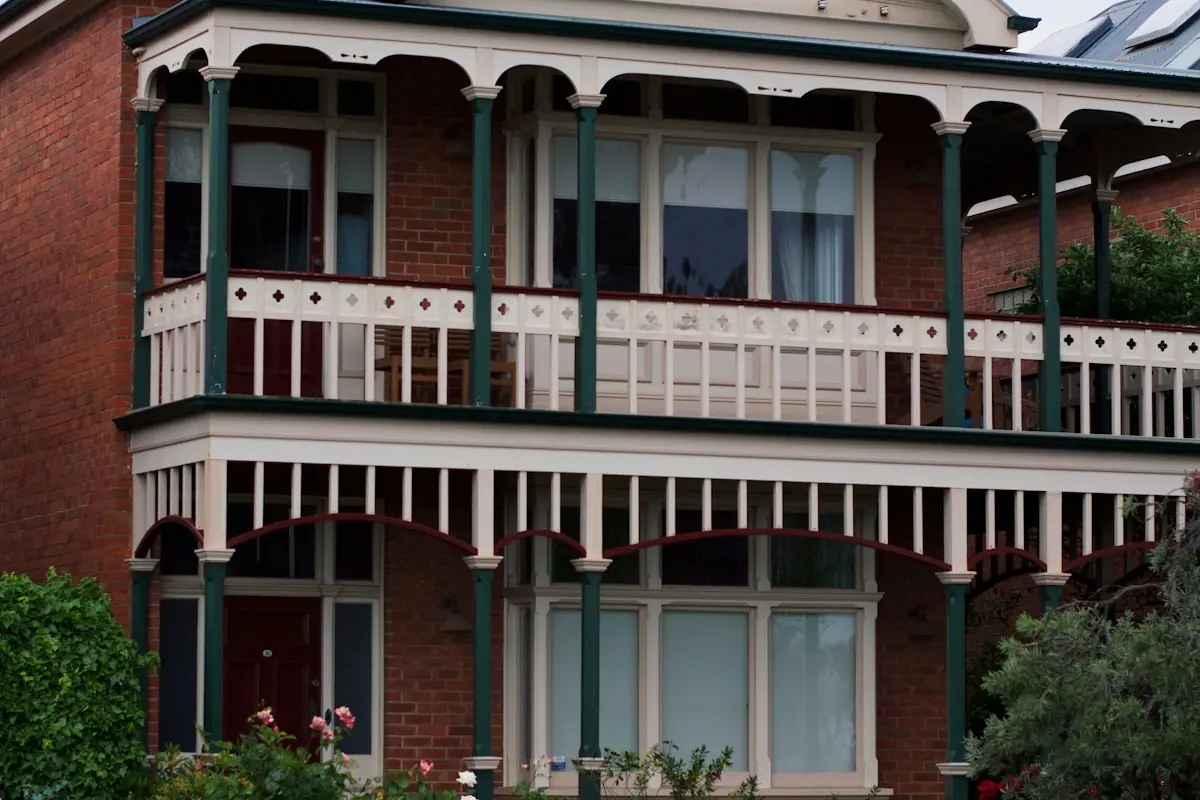
Terrace houses along a tree-lined street
In Bardwell Valley, houses make up 65.6% of homes, terraces and semis 27.0% and apartments 6.4% (ABS Census 2021).

How a lender reads an address in Bardwell Valley

27.0% of dwellings here are attached houses, the terrace and semi stock that defines these streets. Heritage controls on some streets limit what can be changed, which matters if the plan is to renovate with the loan. Only one in six homes in Bardwell Valley are rented, well under the NSW share of 32.6%.

Households tend to stay put, so listings are fewer and being pre-approved before you look matters more than usual. Two thirds of the homes in Bardwell Valley are separate houses on their own block.

With little strata to assess, the lending questions tend to be about the buyer and the block, not the building.

  • Postcode2207
  • CouncilBayside Council
  • From the Sydney CBD12 km south west
6.4%

apartments NSW 21.7%

65.6%

separate houses NSW 65.6%

27.0%

terraces and semis NSW 11.7%

17.3%

rented NSW 32.6%

35.7%

with a mortgage NSW 32.5%

855

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL10197).

A corner cottage with a hedge

How much equity could you use in Bardwell Valley?

Home equity calculator

Home equity calculator

For upgraders and investors, how much of your home could work as a deposit.

$1,100,000
$600,000
  • Total equity$500,000
  • Usable equity (to 80% LVR)$280,000

That usable equity could work as a deposit on an investment property or renovation, structured so your properties aren’t tied together unnecessarily.

Usable equity assumes lending to 80% of your home’s value against your current loan. Lender policy and serviceability decide the real figure.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
I honestly couldn’t recommend Links Property Finance and Charles highly enough. After speaking with others who weren’t able to help me, Charles went above and beyond to understand my situation…
Evangelos Google review
★★★★★
Charles at Links Property Finance made buying our first home so much easier than we expected. As first home buyers, we had a lot of questions around borrowing capacity, our deposit and the different government schemes available to us. Charles explained everything clearly, compared different lenders and kept us updated throughout the whole process. He was always easy to reach and made sure we understood what was happening from pre approval right through to getting our home loan approved. We would definitely recommend Links Property Finance to anyone looking for a mortgage broker, especially first home buyers who want someone to guide them through the process.
Michael Google review
★★★★★
Charles is an absolute star at what he does. He was straight-up, highly professional, and worked hard to secure a fantastic rate for our home loan. Communication was prompt and clear the entire way through. I would trust him with any future financial needs
Alan Google review

Past credit problems and borrowing in Bardwell Valley

Your credit file shows your credit applications, the accounts you hold, recent repayment history and any defaults or court judgments.

Lenders read all of it, and they also look at the reason behind a problem and what has happened since. A paid default from years ago with a clean record afterwards is viewed very differently from recent missed payments.

Mainstream lenders may decline some credit issues that a specialist lender will consider, usually with a higher rate or a larger deposit. Resimac is one lender on our panel that considers some borrowers outside mainstream policy.

Checking your own file before applying, and explaining any issue, avoids a string of declined applications. Credit issues and home loans in detail

A brick house with a gabled roof

Houses and semis in Bardwell Valley

A Sydney terrace with a lace balcony
  • Links Property Finance is based in Enfield, about fifteen minutes from Bardwell Valley, with conversations by phone, video or in person.The first one is private, and starts with what happened and where things stand now.
  • Two in three Bardwell Valley homes are separate houses, and more than a quarter are semis.Fewer than one in five homes is rented, so many buyers here are joining a settled street.

What do lenders look at?

A first home buyer working through their numbers at the kitchen table
  • What happened and when.The type of issue, how long ago it was and whether it has been paid.
  • What has happened since.A clean repayment record afterwards makes a real difference.

Bardwell Creek, the golf course and Bardwell Valley housing

Bardwell Valley lies about eleven kilometres south-west of the city in the Bayside Council area and is part of the St George district. Bardwell Creek runs through the middle of the valley and empties into Wolli Creek.

Bardwell Valley Golf Course sits beside the creek, alongside Silver Jubilee Park, where an olive grove was planted to honour the Greek community’s contribution to the area, and Coolibah Reserve, Shepherd Reserve and Favell Picnic Area line the creek.

  • The name first described the land beside Bardwell Creek in neighbouring Bardwell Park, named after Thomas Hill Bardwell, who bought land here in 1853.
  • When a Bardwell Valley buyer has a past credit issue, Links compares a panel that includes Resimac, ANZ, Westpac, ING and Macquarie.
Read the full detail

The name first described the land beside Bardwell Creek in neighbouring Bardwell Park, named after Thomas Hill Bardwell, who bought land here in 1853. The suburb itself was formed in 1996 from parts of Arncliffe bordering the valley.

Some sandstone cottages from the early twentieth century still stand in East Street and The Glen Road. Today houses make up two in three homes, and semis more than a quarter.

When a Bardwell Valley buyer has a past credit issue, Links compares a panel that includes Resimac, ANZ, Westpac, ING and Macquarie.

Example scenario (illustrative, not a real client): a buyer has a paid default from several years ago, with a clean repayment record since.

Before applying, they obtain their credit reports, gather evidence that the debt was paid, and apply with a lender whose policy accepts paid defaults of that age, rather than applying to several lenders at once.

What stays on your credit file

Defaults generally stay on your credit file for five years, and some court judgments and insolvency records for longer. Repayment history information covers the most recent two years.

You can get a free copy of your credit report from each of the credit reporting bodies, and it is worth checking all of them before you apply. Credit issues and home loans.

A row of red-brick terraces

Why is fewer applications better?

Each application for credit is recorded on your file. Several applications in a short period can look like financial stress, and a decline elsewhere can make the next lender more cautious.

Choosing a lender whose policy fits your situation first time protects your file. Declined by the bank.

Improving your position

Paying any outstanding defaults, keeping every account up to date, reducing credit card limits and avoiding new applications all help over time. If a listing is wrong, you can ask the credit reporting body to correct it.

A plan to move to a mainstream lender later, once your record has improved, is often part of the strategy. Check your loan ready score.

Default, late payments or a judgment?

Three kinds of credit issue, and how lenders tend to see them.

  • Default. An unpaid debt listed by a creditor. Paid and older defaults are viewed more kindly.
  • Late payments. Shown in your recent repayment history. A clean record since helps.
  • Court judgment. Viewed seriously by most lenders. Specialist lenders may consider it once resolved.

What should I check before applying with a credit issue?

The groundwork that improves your chances.

  • Your credit reportsFrom each credit reporting body.
  • Any errorsCorrected before you apply.
  • Outstanding defaultsPaid, with evidence.
  • An explanationWhat happened, in a few plain sentences.
  • Your repayment recordEvery account up to date.
  • One applicationTo a lender whose policy fits.

Common questions about buying in Bardwell Valley with a credit issue

Can I get a home loan with a default on my credit file?

Often, yes, depending on the default, its age, whether it is paid and your record since. Some mainstream lenders accept older paid defaults, and specialist lenders consider more.

How long does a default stay on my file?

Generally five years from when it was listed. Some court judgments and insolvency records remain for longer.

Do late payments affect my application?

They can. Lenders see your recent repayment history, and a pattern of missed payments weighs more than a single late one.

Will I pay a higher rate?

With a specialist lender, usually yes, and a larger deposit may be needed. Many borrowers plan to refinance to a mainstream lender once their record improves.

What if my credit file is wrong?

You can ask the credit reporting body to correct it. Fixing errors before you apply can make a real difference.

Does applying to several lenders hurt my file?

It can: several applications in a short period look like financial stress, so choose the right lender first time.

Talk to a broker about your Bardwell Valley home loan

One free call covers what you could borrow in Bardwell Valley, the lenders that suit the property you want and the order to do things in.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.