



Call Charles Book a meeting
Business lending

Links Property Finance · Investment property mortgage broker, Sydney: Commercial Property Loans in Sydney

Shops, warehouses and mixed-use buildings are financed on different rules from home loans.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Buying commercial property? What finance fits the deal?

A commercial loan, usually at a lower loan-to-value ratio, often 60 to 70 per cent, with the lease, the tenant and the property’s income weighed as heavily as yours. Owner-occupiers buying their business premises are assessed on the business; investors on the lease.

Read more

Pricing is negotiated rather than advertised.

Part of the investment property loans guide.

A couple sitting among moving boxes

Recent Links clients

  • A family in front of the sold sign at the home they bought together Family buy · Inner West
    The whole family turned up. A parents’ guarantee, done properly.
  • Three Links Property Finance clients in front of the agent’s board at the home they bought Family buy · South West Sydney
    Bought, and all smiles. A family purchase in Sydney’s south-west.
  • Next one

    Your sold sign could be next.

    A free 30-minute call shows where you stand.

    Book my free call
Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles Touma from Links Property Finance was a great help with buying my first home. I had plenty of questions and he took the time to explain things clearly without making me feel rushed. He kept me updated throughout and made the process much less stressful. Really appreciated his patience and would happily recommend him to other first home buyers.
Catherine Google review
★★★★★
Highly recommend Charles! Professional, knowledgeable and very easy to work with. He helped us navigate the home loan process and found a great solution that suited our needs. Excellent service from start to finish.
Daniel Google review
★★★★★
I honestly couldn’t recommend Links Property Finance and Charles highly enough. After speaking with others who weren’t able to help me, Charles went above and beyond to understand my situation…
Evangelos Google review

How does commercial differ from a home loan?

A family on the porch of their home
  • Deposits are bigger: lenders commonly go to around 70–80% of value on standard commercial security, less for specialised property, so the equity contribution is materially larger than residential.
  • Terms are shorter: fifteen to twenty-five years rather than thirty, sometimes with periodic reviews.
  • Pricing is negotiated: commercial rates depend on the security, the lease, the borrower's strength and the lender's appetite that quarter, the "rate card" is a starting position, not an answer.
  • And the consumer protections differ: business-purpose lending generally sits outside the consumer credit protections that cover home loans, which makes independent advice and careful document review more important, not less.

Owner-occupier or investor

A family together in their backyard
  • Lenders read the two differently.
  • A business buying its own premises is assessed on the business's financials, the property swaps a rent bill for a loan repayment, and the file leans on trading performance, often through a trust or company structure. An investor buying a tenanted commercial property is assessed substantially on the lease: who the tenant is, how long the term runs, and what happens to the loan if the property falls vacant.

What do lenders look at hardest?

The security itself: a suburban shopfront with broad reuse potential is easier lending than a purpose-built premises with one possible tenant. The lease, on investment purchases: length, options, tenant quality and rent reviews, a long lease to a strong tenant improves the terms available.

Two common examples are childcare centres and storage units. The financials: usually two years, with the same add-back logic as self-employed home lending. And the exit: how the debt retires over the term, particularly where interest-only periods are involved.

Sydney and Inner West angles

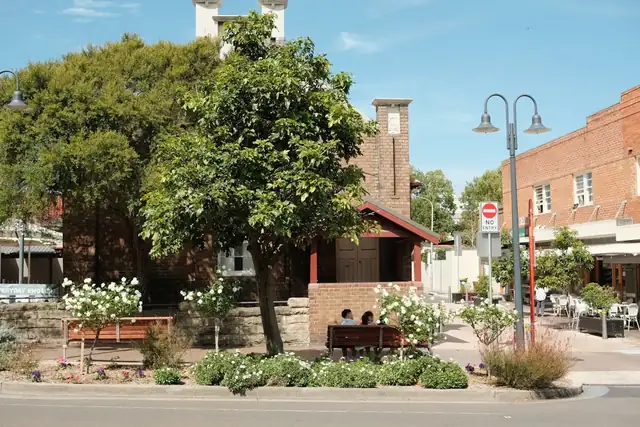
The Inner West's commercial stock is exactly the tricky-but-good kind: mixed-use shopfronts with residences above along the main roads, small warehouses converting between trade and creative uses, and strata offices and food premises where lender appetite swings on the fit-out and the use.

Mixed-use in particular sits in a policy seam, some lenders treat it as commercial, some as residential with conditions, and the difference moves both the deposit and the rate. Knowing which lender reads a property which way is half the value of the advice.

Common questions about commercial lending

How much deposit do I need for a commercial property?

Plan around 20–35% of the purchase price plus costs, depending on the property type and the strength of the file, standard suburban commercial sits at the friendlier end, specialised premises at the tougher end.

Existing equity in other property can sometimes stand in for cash, which is a structuring conversation worth having early.

Can my SMSF buy a commercial property?

Yes. Since 10 August 2026, business real property such as commercial premises is the only property an SMSF can buy with a new limited recourse borrowing arrangement. SMSF lending is specialised and regulated, so start with your financial adviser and accountant.

If an SMSF purchase is on your mind, the sequence starts with your financial adviser and accountant; we can then speak to the lending side of what they design.

Is GST payable on a commercial purchase?

Often, though going-concern and other treatments can change the answer, it's an accountant's question with a big cash-flow consequence, because the lending needs to be sized for the GST position from the start, not discovered at settlement.

We flag it in every commercial file precisely so it lands on the right desk early.

Why is the advertised commercial rate meaningless?

Because commercial pricing is built per deal: security quality, lease strength, loan size, borrower financials and lender appetite all move it.

Two borrowers buying similar buildings can receive noticeably different terms, which is why commercial files reward a broker who prices the deal across multiple lenders rather than accepting the first indication.

Can I live in the flat above the shop I buy?

Yes, but the loan depends on the floor-area split: some lenders assess mixed-use property residentially with conditions, others as commercial, which changes the deposit, the rate and the term.

The answer changes the deposit, the rate and the term, so the property should be matched to the lender before the contract, not after.

Get advice on commercial property loans

Thirty minutes with Charles: what the property type means for deposit and term, how your financials will read, and the deal priced across lenders, not taken from a rate card.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit, tax, legal or financial advice. Business-purpose lending generally sits outside consumer credit protections; seek independent advice on contracts and structures. Lending ranges and terms are indicative, vary by lender and security, and are subject to assessment and approval.