
Call Charles Book a meeting
Mortgage Broker Ashbury

Links Property Finance · Home loans in Ashbury and across Sydney: Mortgage Broker in Ashbury

Nine in ten Ashbury homes are separate houses, against about two in three across NSW, and almost half are owned outright.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Buying in Ashbury with family money: gift, inheritance or guarantee?

A gift, an inheritance and a family guarantee each work differently. A gift needs a signed letter and a clean transfer trail, and some lenders still want genuine savings beside it. Inheritance counts once it is in your account with the estate papers.

Read more

A guarantee uses your parents’ equity instead of cash, usually with no mortgage insurance, and keeps their money where it is.

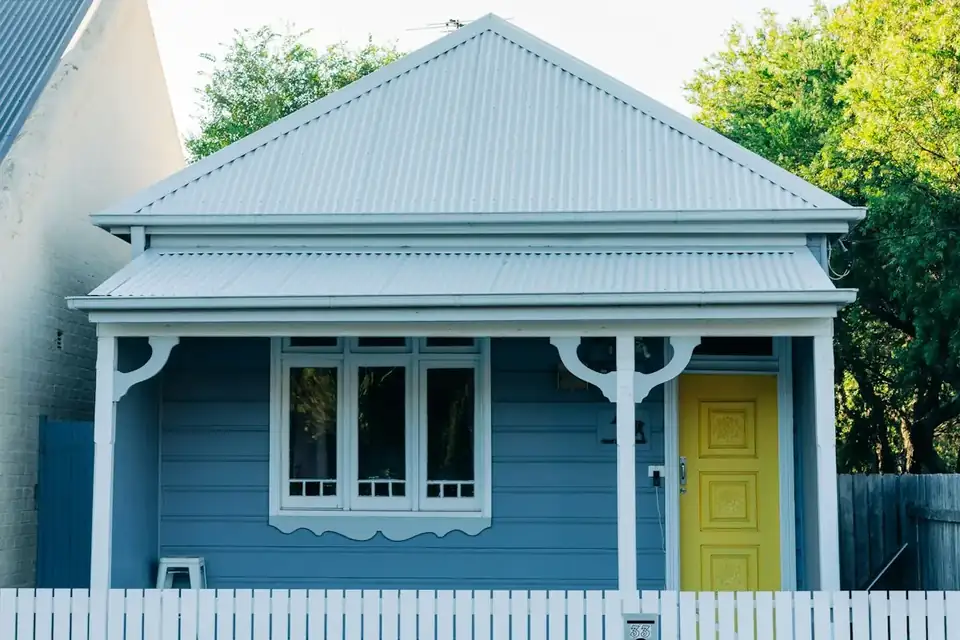
A blue weatherboard cottage
Ashbury housing mix: 90.2% houses, 7.1% terraces and semis, 1.5% apartments (ABS Census 2021).

Ashbury by its homes

Ashbury is house country: 90.2% of dwellings are freestanding, against 65.6% for NSW. With little strata to assess, the lending questions tend to be about the buyer and the block, not the building. Most of Ashbury owns rather than rents, with only 12.3% of homes leased.

Households tend to stay put, so listings are fewer and being pre-approved before you look matters more than usual. At 1,167 homes, Ashbury is one of the smaller suburbs nearby, which can make a valuation the slowest part of the loan.

  • Postcode2193
  • CouncilCity of Canterbury-Bankstown
  • From the Sydney CBD9 km south west
1.5%

apartments NSW 21.7%

90.2%

separate houses NSW 65.6%

7.1%

terraces and semis NSW 11.7%

12.3%

rented NSW 32.6%

37.2%

with a mortgage NSW 32.5%

1,167

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL10094).

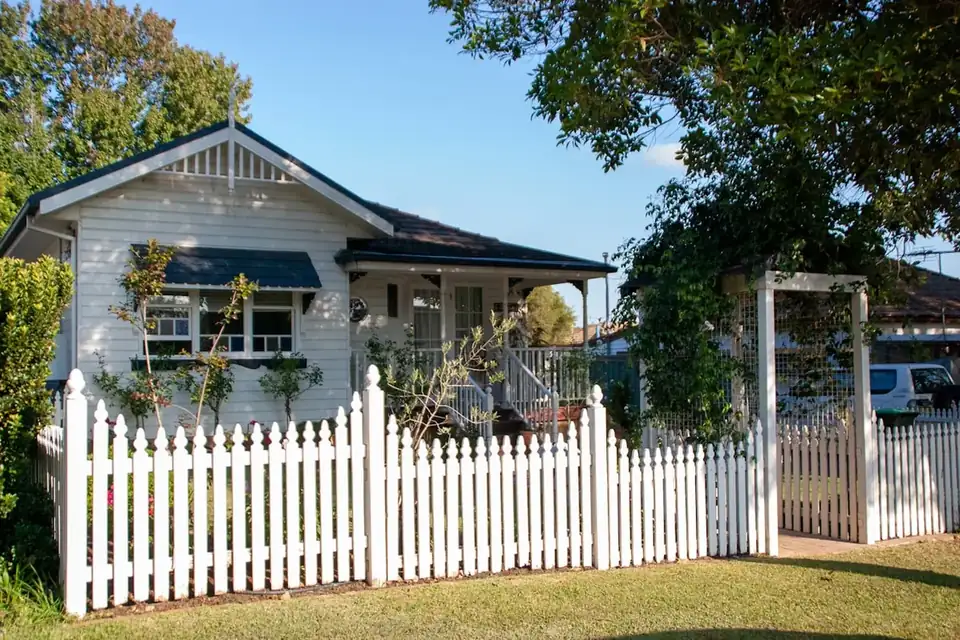
A corner cottage with a hedge

What your Ashbury home could fund

Home equity calculator

Home equity calculator

For upgraders and investors, how much of your home could work as a deposit.

$1,100,000
$600,000
  • Total equity$500,000
  • Usable equity (to 80% LVR)$280,000

That usable equity could work as a deposit on an investment property or renovation, structured so your properties aren’t tied together unnecessarily.

Usable equity assumes lending to 80% of your home’s value against your current loan. Lender policy and serviceability decide the real figure.
Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
A huge thank you to Charlie for his exceptional support and expertise throughout the process of securing finance for my first home.
Julian Google review
★★★★★
Charles looked after us really well and his knowledge gave us the confidence to purchase our property. He wasn’t pushy and always ensured we felt comfortable with the repayments.
Sandra Google review
★★★★★
Charles and the team recently assisted us with a refinance of our investment property. Recommend Charles and the team to all
Tony Google review

Buying in Ashbury with family money

A lender will accept a gift towards your deposit, but it wants to know three things: who it came from, that it is a gift rather than a loan, and that it is in your account.

A signed gift letter or statutory declaration from the giver usually covers the first two, and a bank statement showing the funds covers the third.

Where the gift makes up much of the deposit, some lenders also want to see savings you built yourself, or a steady rental history, before they will lend at a higher loan-to-value ratio.

Settling who is giving what, and when, early keeps the application straightforward. See a gift letter template

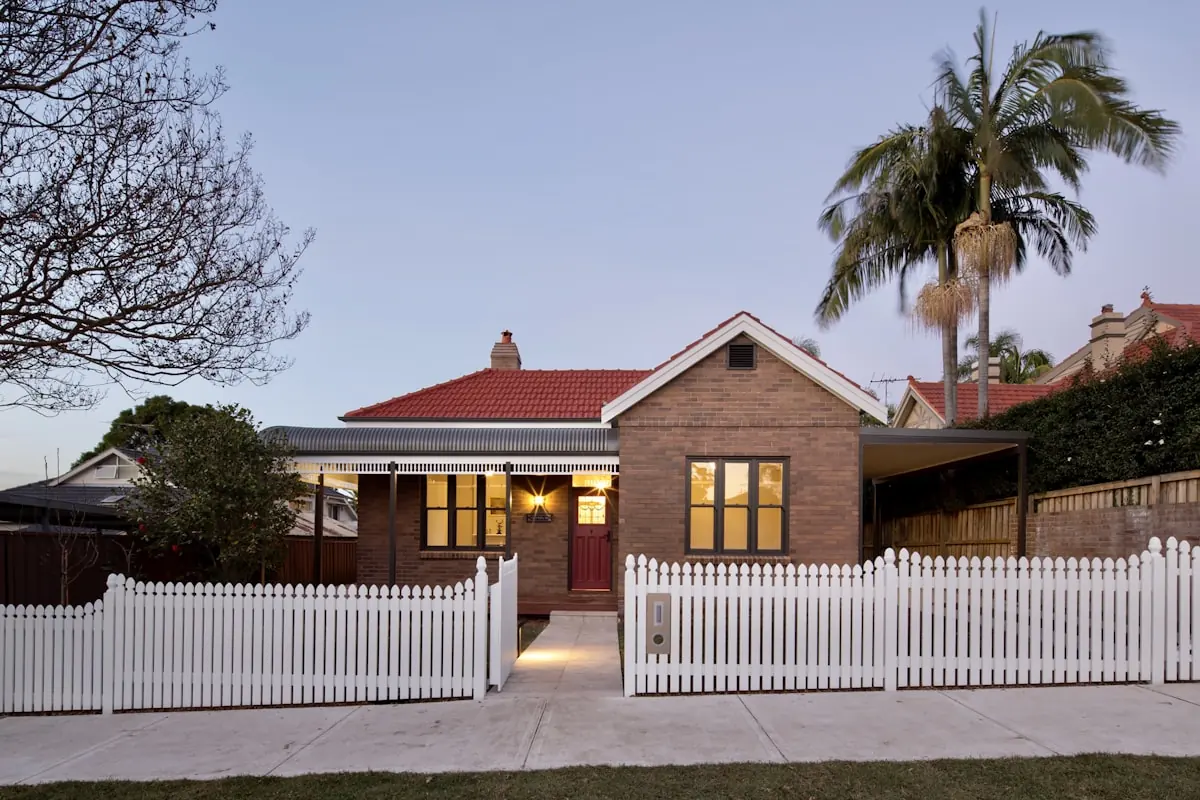
A Federation-era house with a tiled roof and front garden

Houses and family help in Ashbury

A brick bungalow behind a white picket fence
  • Links Property Finance is based in Enfield, a short drive north-west of Ashbury.Conversations run by phone and video, and family members can join when a gift or guarantee is part of the plan.
  • Nine in ten Ashbury homes are separate houses, compared with about two in three across New South Wales.A house on its own title is straightforward security, so the question here is usually the size of the deposit rather than the property.

What does a lender need to see for a gift?

A family on the porch of their home
  • A gift letter or statutory declaration from the person giving the money.It confirms the amount, that it is a gift, and that nothing has to be repaid or returned.
  • Evidence the money has reached you.Most lenders want the funds in your account before settlement, with statements showing where they came from.

King Street, Peace Park and Ashbury houses

Ashbury lies about ten kilometres south-west of the city, mostly in the City of Canterbury-Bankstown with some streets in Inner West Council. It shares postcode 2193 with Canterbury and Hurlstone Park, and its name joins those of its neighbours, Ashfield and Canterbury.

There is no shopping centre, only a few shops on King Street, and its best-known open space is Peace Park, the highest point in the former Canterbury local government area.

Gift, loan or guarantee?

Money from family can reach a purchase in three ways. A gift is yours outright, and the lender treats it as part of your deposit once documented. A guarantee uses a parent’s property as extra security without any money changing hands.

A loan from family is a debt, and the repayments count against your borrowing power even if the terms are relaxed.

A brick house with a gabled roof

Genuine savings and gifted money

Genuine savings are funds you have saved or held yourself over a period, often around three months, and some lenders want to see them when the deposit is small.

A recent gift usually does not count on its own, though rent paid on time over the past year or so can sometimes stand in for part of it.

Using an inheritance

An inheritance only becomes usable once the estate pays out, and that can take many months after a death, particularly if a property has to be sold first.

Lenders generally will not count an expected inheritance until the money has been received or the executor has confirmed the amount and timing in writing.

If you want to buy in the meantime, it is simpler to line up the purchase with the payout where you can than to rely on money that has not arrived. Buying with an inheritance.

Gift, guarantee or family loan?

Three ways family can help an Ashbury purchase, and what each means for the application.

  • A gift. The simplest for the lender once documented. The money is yours and counts towards the deposit.
  • A guarantee. No cash changes hands. Part of a parent’s equity secures the loan, often avoiding lenders mortgage insurance.
  • A family loan. The money has to be repaid, so the lender counts the repayments, even informal ones.
Read the full detail
  • A gift. The simplest for the lender once documented. The money is yours and counts towards the deposit. The giver cannot reclaim it later, so the decision should suit their own finances first.
  • A guarantee. No cash changes hands. Part of a parent’s equity secures the loan, often avoiding lenders mortgage insurance. The guarantor carries real risk, and independent legal advice comes before signing.
  • A family loan. The money has to be repaid, so the lender counts the repayments, even informal ones. Declaring it is essential. A loan presented as a gift is a serious problem for everyone involved.
Terrace houses along a tree-lined street

What should I check before using family money in Ashbury?

The groundwork that lets a lender count the help.

  • Agree the form of helpGift, guarantee or loan. Decide before you start looking, because each is assessed differently.
  • A signed gift letterFrom the giver, stating the amount and that it is not repayable.
  • The money in your accountTransfer the funds early and leave them there, so statements show a clear trail.
  • Your own savings historyKeep regular savings going, even if the gift is larger. Some lenders want to see both.
  • Advice for the giverA gift or guarantee affects the family member too. Independent advice protects everyone.
  • The heritage positionIf you plan to extend a bungalow, check the planning certificate for conservation controls.

Common questions about buying in Ashbury

Can my parents give me my whole deposit?

Often, yes. Many lenders accept a fully gifted deposit, but some want savings of your own as well, particularly when the loan-to-value ratio is high.

The gift needs to be documented with a gift letter or statutory declaration and be in your account before settlement. Which lender you apply to matters a great deal, because policies on fully gifted deposits vary.

What does a gift letter need to say?

Generally the giver’s name, their relationship to you, the amount, and a clear statement that the money is a gift that does not have to be repaid and gives them no interest in the property.

Lenders have their own forms, and some want a statutory declaration instead. A template is a good starting point, but check the lender’s requirements before anyone signs.

Does gifted money count as genuine savings?

Usually not on its own. Genuine savings are funds you have built or held yourself over a period, and a recent gift is not that.

Some lenders accept a strong rental history instead, and some do not ask for genuine savings at all once the deposit reaches a certain size. If your deposit is mostly gifted, apply to a lender comfortable with that.

Can I count an inheritance I have not received yet?

Generally not. Lenders want the money in hand, or at least written confirmation from the executor of the amount and when it will be paid. Estates can take many months to finalise, especially where property has to be sold. If timing is tight, talk it through before signing any contract.

Is a family guarantee better than a gift?

Neither is better in general. A guarantee lets family help without handing over cash and can mean avoiding lenders mortgage insurance, but the guarantor takes on real risk.

A gift is simpler for the lender and final for the giver. The right choice depends on the family’s own finances and appetite for risk, and independent advice is wise either way.

Does the lender check the family member giving the money?

Not their income, for a gift: the lender mainly checks the paperwork and that the funds have arrived. For a guarantee, the guarantor’s property and circumstances are assessed, and they need independent legal advice before signing.

Talk to a broker about your Ashbury home loan

Bring your Ashbury plans to a free 30-minute call: your borrowing range, the lenders that fit the property and your next step.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.