Call Charles Book a meeting
Mortgage Broker Fairfield

Links Property Finance · Home loans in Fairfield and across Sydney: Mortgage Broker in Fairfield

Fairfield buys as families.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Buying in Fairfield as a family: how do lenders treat pooled deposits?

Lenders need to know whether pooled money is a gift, a loan or a share of ownership. A gift needs a signed letter and a clear transfer trail; family members on the title and the loan add their income but also share the debt.

Read more

Putting the arrangement in writing before contracts keeps the application clean.

An aerial view of a Sydney suburb
Of Fairfield's homes, 40.0% are houses, 13.4% terraces and semis and 46.0% apartments (ABS Census 2021).

What Fairfield is built of

57.5% of homes here are rented, against 32.6% across NSW. High rental demand here helps an investment loan, because lenders count part of the expected rent toward servicing. Units account for 46.0% of homes in Fairfield, about twice the state figure. Small studios and older blocks with thin sinking funds narrow the lender list, which is worth knowing before you bid.

  • Postcode2165
  • CouncilCity of Fairfield
  • From the Sydney CBD30 km west
46.0%

apartments NSW 21.7%

40.0%

separate houses NSW 65.6%

13.4%

terraces and semis NSW 11.7%

57.5%

rented NSW 32.6%

17.9%

with a mortgage NSW 32.5%

6,917

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL11480).

A terrace with an iron-lace balcony

Stamp duty on a Fairfield purchase

NSW first home buyer stamp duty

NSW first home buyer stamp duty

$750,000
Transfer (stamp) duty$0Exempt under the First Home Buyers Assistance Scheme, saving $27,937

Assumes an eligible NSW first home buyer purchasing an existing home under the First Home Buyers Assistance Scheme (exempt to $800k, concession to $1m). Indicative only, check Revenue NSW for your exact position.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
As a first home buyer, I was pretty overwhelmed at the start, but Charles made everything much easier. He explained the process step by step and helped me understand my borrowing options. His professionalism and responsiveness were excellent.
Ric Google review
★★★★★
I have had a number of dealings with Charles from Links Property Finance. He is very knowledgeable, thorough, and detailed with his advice. Importantly, he is very approachable and easy to deal with. His advice has been beneficial to myself and my acquaintances. I highly recommend him.
Joseph Google review
★★★★★
Paperwork and finances were never my strong suit. He has made this process as simple and dummy proof for me as humanly possible. This is not the first time I use a mortgage broker, however it was the easiest and most pleasant.
Mikhail Google review

Helping families buy in Fairfield

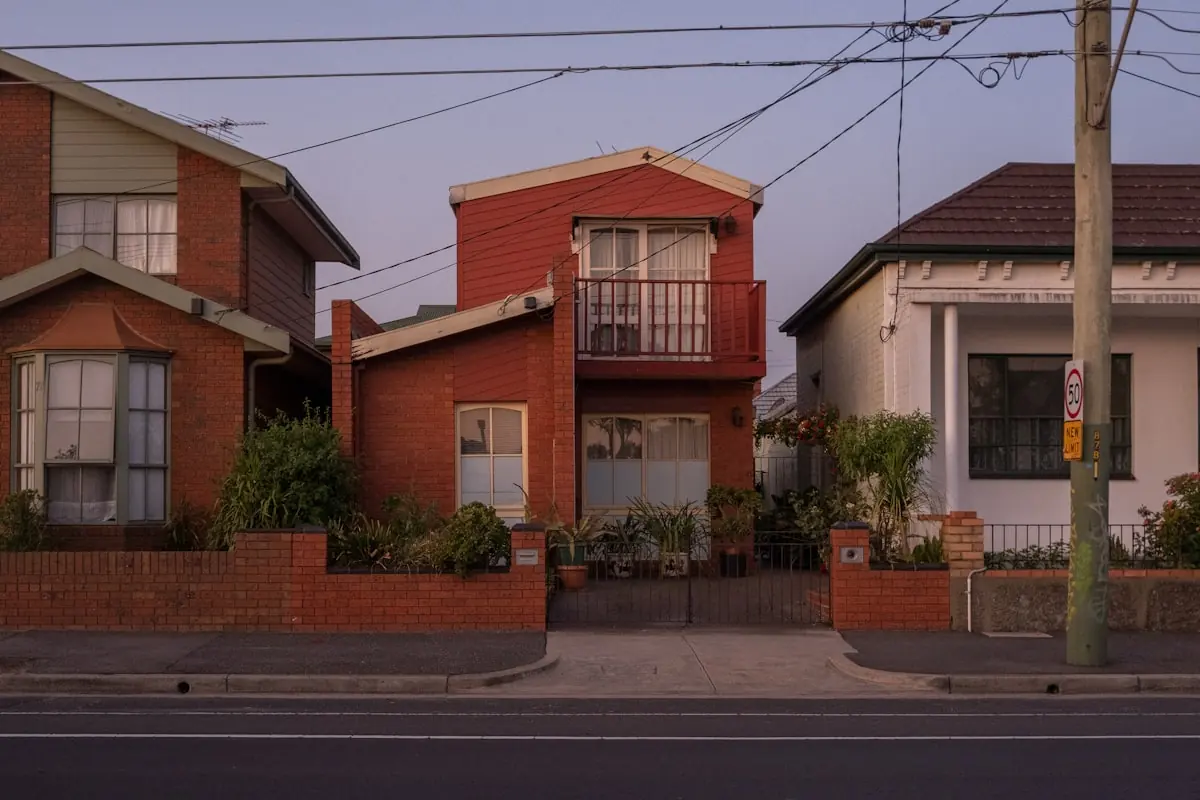
A row of red-brick terraces in Sydney
  • Links Property Finance works across Western Sydney by phone, video and in person when it helps.Fairfield files are family files: parents and adult children buying together, gifts moving between households, guarantees launching first purchases, and houses bought with the intention of never moving again.
  • It is also one of Sydney's reachable house markets, where the $800,000 duty exemption still catches family homes rather than just studios, and where the 5% scheme's cap is nowhere near binding.

Deposits assembled properly

A family together in their backyard
  • Family money is the west's deposit engine, and lenders accept it readily when it arrives with the right paperwork: a signed letter stating the gift is non-repayable, a clean transfer trail, and where low-deposit rules apply, evidence of savings history alongside it.
  • The delays we see are almost never eligibility, they are evidence.Gifts assembled the week before an application stall it; the same gift documented a month earlier does not. The gifted deposit guide has the checklist, and the genuine savings guide covers the rules it has to satisfy.

Fairfield station, the town centre flats and the family blocks

Fairfield station sits on The Crescent, with a bus interchange beside it and the Ware Street shopping strip a short walk away. Low-rise walk-up flats ring the town centre, with some newer apartment buildings closer in.

A unit near the station and interchange usually brings steady rental demand, which matters in a suburb where renting is common, and a good supply of comparable sales for the valuer.

With the older blocks, the strata report, the sinking fund and any planned repairs decide whether a flat is straightforward security.

  • The streets beyond the flats are mostly family houses on generous blocks, many bought by households who intend to stay, and some with room for a granny flat.
  • Links can put a Fairfield family application to lenders such as ANZ, Westpac, Macquarie, ING and Resimac, and chooses the one whose policy reads the household’s income and deposit most accurately.
Read the full detail

The streets beyond the flats are mostly family houses on generous blocks, many bought by households who intend to stay, and some with room for a granny flat.

There the property is rarely the hard part of the file. What decides the lender is how the deposit was put together, whose names go on the title, and how income from a local business is read.

Links can put a Fairfield family application to lenders such as ANZ, Westpac, Macquarie, ING and Resimac, and chooses the one whose policy reads the household’s income and deposit most accurately.

Example scenario (illustrative, not a real client): two siblings and a parent plan to buy a Fairfield house together, close enough to the station for the siblings to commute, while one sibling runs a small shop in the town centre.

The issues are a joint application across three incomes, business income that looks different depending on which year and add-backs a lender uses, and a deposit that includes family gifts. Comparing how lenders assess business financials and multi-party applications shows which lender reads this household best.


Terrace houses along a tree-lined street

The family file

Four instruments Fairfield purchases use constantly, each done properly.

First home buyers in Fairfield

One of the few Sydney markets where a family house sits inside every support.

  • The 5% Deposit SchemeThe $1.5 million cap covers the whole local market, houses very much included. Five per cent down, no lender's insurance. Check eligibility.
  • Stamp duty at zeroThe $800,000 exemption catches genuine Fairfield family homes, thousands kept in your deposit. Run your price.
  • Help to Buy, liveShared equity from a 2% deposit inside income and price caps, well matched to local prices. Settings checked against your file.
  • Self-employed householdsFairfield runs on small business. The right lender reads those accounts properly, here is how they differ.

Common questions about buying in Fairfield

My parents are giving us the deposit. What paperwork do lenders want?

A signed gift letter stating the amount is non-repayable, the bank trail showing it arrive, and at some lenders a holding period or savings history alongside it. Documented properly it is routine; documented casually it stalls approvals for weeks. Start the paperwork before you start inspecting.

What should I check before buying a flat near Fairfield station?

Start with the building. Many units around the Fairfield town centre are in older walk-up blocks, so the strata report, the sinking fund balance and any special levies say a lot about future costs, and valuers take notice of them too.

Confirm the internal size of the unit, whether a car space comes with it, and how many units the block holds. If you are investing, a rental appraisal helps, because lenders count only part of the rent.

Can several family members buy one property together?

Yes, and Fairfield does it constantly: a joint application assessed on combined position, title held as tenants in common in shares matching real contributions, and a co-ownership agreement your solicitor drafts. The lending side is well-trodden; the paperwork is what protects everyone later.

Can we buy a house here on ordinary incomes?

Yes, more than in most of Sydney: prices sit inside the 5% scheme’s cap with room to spare, and a real share of houses fall under the $800,000 duty exemption. Add family support and the deposit maths that fails closer in works here.

Is a granny flat worth building?

It can be, where the block and zoning allow it. Lenders count part of approved granny flat rent, and the build is funded against its value once complete. Whether it pays depends on the cost against the rent and value it adds.

We run a small business. Will that make approval harder?

Not with the right lender. The difficulty is that lenders read business accounts very differently, on which year, on add-backs, on retained profits, and the spread on the same figures can exceed a hundred thousand dollars of borrowing power. Placement is the strategy, and the income calculator shows your likely readings in two minutes.

Talk to a broker about your Fairfield home loan

Bring your Fairfield plans to a free 30-minute call: your borrowing range, the lenders that fit the property and your next step.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.