




Call Charles Book a meeting
Mortgage Broker Miranda

Links Property Finance · Home loans in Miranda and across Sydney: Mortgage Broker in Miranda

Miranda is the Shire’s everyday centre, ringed by its deepest belt of townhouses and units.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Which lender says yes to a Miranda home?

Most lenders, for a standard townhouse or unit with a clean strata record. Miranda is the Shire’s entry point, so first home buyers often use the 5% Deposit Scheme and the NSW stamp duty exemption here.

Read more

Family help, a gift or a guarantee, and downsizers buying with equity are the other common files.

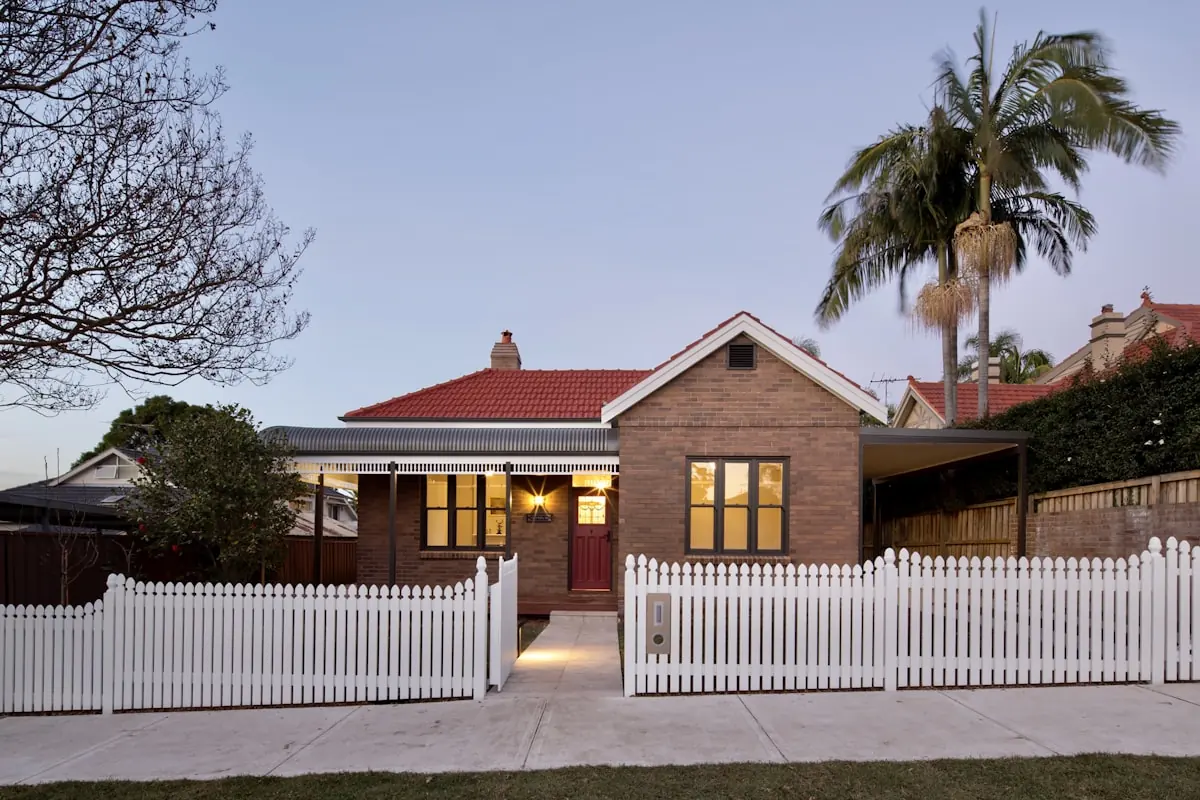
A brick house with a gabled roof
Of Miranda's homes, 40.2% are houses, 17.4% terraces and semis and 41.3% apartments (ABS Census 2021).

Miranda’s housing, in numbers

Four in ten homes in Miranda are apartments, about twice the share across NSW. Here the building is assessed almost as closely as the borrower, from the strata report to the size of the complex.

  • Postcode2228
  • CouncilSutherland Shire
  • From the Sydney CBD24 km south
41.3%

apartments NSW 21.7%

40.2%

separate houses NSW 65.6%

17.4%

terraces and semis NSW 11.7%

34.7%

rented NSW 32.6%

32.8%

with a mortgage NSW 32.5%

7,766

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL12656).

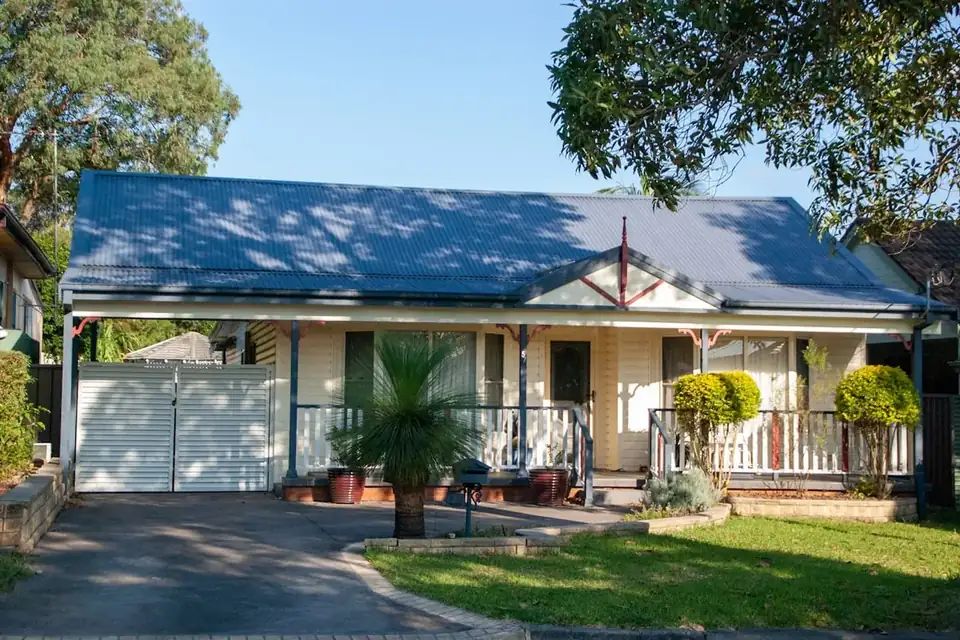
A blue-roofed house with a front path

How much could you borrow for Miranda?

How much could you borrow?

$140,000
None

What moves the number

Choose any that apply. Each shows roughly how much it changes the figure, the way a lender’s assessment would.

$635,000

is an indicative borrowing figure at today’s typical rates. Lenders typically count around 80% of rental income, which is why an investment purchase can lift your number, your real figure comes from a proper assessment.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
A huge thank you to Charlie for his exceptional support and expertise throughout the process of securing finance for my first home.
Julian Google review
★★★★★
Charles at Links Property Finance made buying our first home so much easier than we expected. As first home buyers, we had a lot of questions around borrowing capacity, our deposit and the different government schemes available to us. Charles explained everything clearly, compared different lenders and kept us updated throughout the whole process. He was always easy to reach and made sure we understood what was happening from pre approval right through to getting our home loan approved. We would definitely recommend Links Property Finance to anyone looking for a mortgage broker, especially first home buyers who want someone to guide them through the process.
Michael Google review
★★★★★
Charles Touma from Links Property Finance was a great help with buying my first home. I had plenty of questions and he took the time to explain things clearly without making me feel rushed. He kept me updated throughout and made the process much less stressful. Really appreciated his patience and would happily recommend him to other first home buyers.
Catherine Google review

Helping buyers and families in Miranda

A brick bungalow in Sydney
  • Links Property Finance works across the Shire by phone, video and in person when it helps.Miranda files are gateway files: first purchases in the townhouse belts, unit buys near the centre, and the family instruments, gifts, guarantees, that Shire deposits are traditionally built with.
  • The suburb's role is structural: it holds the price points the schemes cover, in a region where houses quickly leave them behind, which makes it the natural first move in the Shire's suburb-by-suburb progression.

Townhouses, the Shire's middle answer

A family together in their backyard
  • Between unit and house sits Miranda's specialty: townhouse living with a courtyard and a garage, priced inside the supports' reach, on strata that behaves more simply than tower schemes.
  • The lending is conventional; the comparison is where the work is, townhouse against unit against stretching for a house, run across deposit, duty, repayments and the five-year plan.The full-cost calculator does the arithmetic side.

Miranda station, Westfield and the townhouse streets

Miranda station is on Kiora Road, a short walk from Westfield Miranda, on the Cronulla branch with Gymea on one side and Caringbah on the other.

The units within walking distance of the station and the centre draw steady tenant interest, which gives an investor’s valuer and lender recent rents and sales to work from.

In those blocks a lender looks closely at the strata records, how many units share the building and how much internal space the unit has.

  • Miranda has a far higher share of apartments than New South Wales as a whole, and a large share of townhouses and villas too, so freestanding houses are the minority.
  • The panel Links works with includes ANZ, Westpac, Macquarie, ING and Resimac, and the point of comparing them is to match a Miranda townhouse or unit to a lender comfortable with that particular scheme.
Read the full detail

Miranda has a far higher share of apartments than New South Wales as a whole, and a large share of townhouses and villas too, so freestanding houses are the minority.

Units and townhouses are both strata, but townhouse schemes are usually smaller, which tends to mean a shorter strata report and simpler levies. Houses, in turn, are where the NSW duty relief for first home buyers usually stops doing its full job.

The panel Links works with includes ANZ, Westpac, Macquarie, ING and Resimac, and the point of comparing them is to match a Miranda townhouse or unit to a lender comfortable with that particular scheme.

Example scenario (illustrative, not a real client): A first home buyer renting in the Shire has shortlisted a two-bedroom unit near Miranda station and a townhouse a few streets away. The unit is in a larger building with a thin sinking fund; the townhouse is in a small scheme with modest levies.

One lender may be cautious about the larger building while another is comfortable with both. Comparing policies before the offer shows which purchase can proceed under the 5% deposit scheme with the least friction.
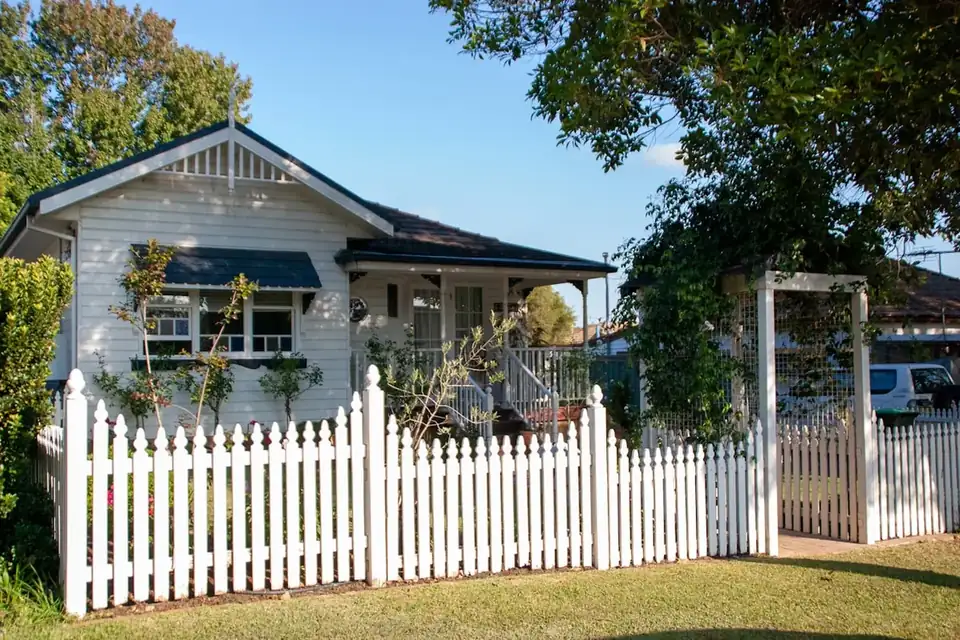

A Federation-era house with a tiled roof and front garden

The Shire entry, stacked properly

Miranda price points let the supports do their complete job. The sequence:

The supports at Miranda prices

Each scheme, doing its full job in this market.

  • The 5% Deposit SchemeThe $1.5 million cap covers Miranda's townhouses and units comfortably. Five per cent down, no lender's insurance, no income caps. Check eligibility.
  • Stamp duty reliefExemption to $800,000 catches real Miranda stock; the concession runs to $1 million. Run your price.
  • Help to Buy, liveShared equity from a 2% deposit inside income and price caps, well matched to the gateway belt. Settings verified against your file.
  • The townhouse questionStrata, but simpler: smaller schemes, lower levies, records still worth reading before the offer.

Common questions about buying in Miranda

Is Miranda the right first step into the Shire?

It is the step most Shire first-timers take: the townhouse and unit belts hold prices inside the schemes' reach, stock trades steadily, and the suburb's amenity does the lifestyle work while equity builds for the next move. The Shire progression usually starts here or in Sutherland, by design, not accident.

Are units near Westfield Miranda easier to finance?

Not automatically. Being close to Miranda station and Westfield Miranda supports tenant demand and gives a valuer plenty of comparable sales, but the lender still assesses the building itself: how large it is, what the strata report shows, how much internal space the unit has and any defect history.

A well-kept unit in a smaller block near the centre is usually uncomplicated. A small unit in a large complex may suit some lenders and not others, which is worth checking before you offer.

Townhouse or unit, what's the real difference for my loan?

The loan treats both as strata purchases; the economics differ. Townhouses carry smaller schemes, simpler levies and land-ish character; units near the centre buy location and lower entry prices. Compare across deposit, duty, levies and the five-year plan with the calculator, and let your numbers pick.

My parents want to guarantee our loan. What does that involve?

Their property secures a defined slice of yours, closing the deposit gap and typically removing lender's insurance, and the guarantee releases when repayments and value bring your ratio inside the threshold.

It needs their independent advice, a planned exit, and frank conversations, all standard, all worth doing properly. The mechanics.

How much do I need saved for a Miranda townhouse?

Under the schemes: five per cent plus costs, with duty gone or reduced below the thresholds, a figure most Shire renters can reach. Without: the standard ladder toward twenty per cent. Documented family gifts count with the right paperwork. The deposit calculator gives your number.

Is Miranda worth considering for an investment unit?

It can be: the centre’s amenity and transport anchor steady tenant demand, and entry prices keep yields readable, though lenders assess the rent conservatively. Investment structure differs from owner-occupier lending, so design it before contracts.

Talk to a broker about your Miranda home loan

Thirty minutes with Charles: what you could borrow, which lenders suit Miranda property and what to do next. Free, with no credit check.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.



