Call Charles Book a meeting
Mortgage Broker Russell Lea

Links Property Finance · Home loans in Russell Lea and across Sydney: Mortgage Broker in Russell Lea

Russell Lea’s wide blocks have made it duplex country: one cottage down, two homes up.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Building a duplex in Russell Lea: how is the project financed?

As a construction loan valued on the finished pair. The lender funds the build in stages and assesses the end debt against whether you keep both homes, sell one, or live in one and rent the other.

Read more

Approvals, a fixed-price contract and the end plan come first, before the first quote is signed.

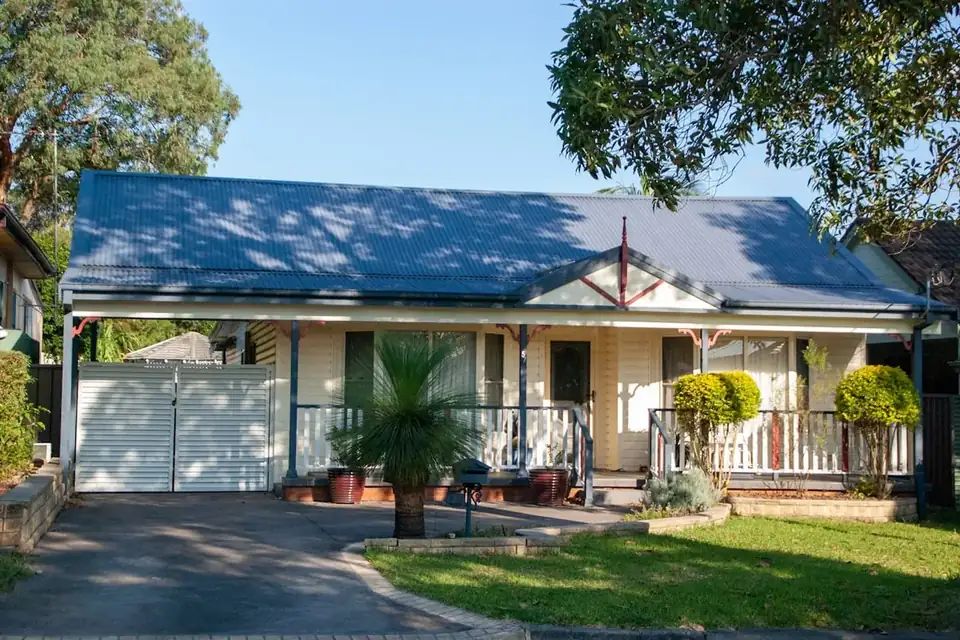
A corner cottage with a hedge
In Russell Lea, houses make up 68.3% of homes, terraces and semis 7.8% and apartments 23.4% (ABS Census 2021).

How a lender reads an address in Russell Lea

Russell Lea is house country: 68.3% of dwellings are freestanding, against 65.6% for NSW. A house on its own title is the simplest security a lender takes, and the land carries most of the value. Russell Lea is small, at 1,966 private dwellings, so comparable sales are thin and a valuation can be harder to predict.

  • Postcode2046
  • CouncilCity of Canada Bay
  • From the Sydney CBD8 km west
23.4%

apartments NSW 21.7%

68.3%

separate houses NSW 65.6%

7.8%

terraces and semis NSW 11.7%

25.6%

rented NSW 32.6%

35.1%

with a mortgage NSW 32.5%

1,966

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL13462).

A blue-roofed house with a front path

What your Russell Lea home could fund

Home equity calculator

Home equity calculator

For upgraders and investors, how much of your home could work as a deposit.

$1,100,000
$600,000
  • Total equity$500,000
  • Usable equity (to 80% LVR)$280,000

That usable equity could work as a deposit on an investment property or renovation, structured so your properties aren’t tied together unnecessarily.

Usable equity assumes lending to 80% of your home’s value against your current loan. Lender policy and serviceability decide the real figure.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles at Links Property Finance made buying our first home so much easier than we expected. As first home buyers, we had a lot of questions around borrowing capacity, our deposit and the different government schemes available to us. Charles explained everything clearly, compared different lenders and kept us updated throughout the whole process. He was always easy to reach and made sure we understood what was happening from pre approval right through to getting our home loan approved. We would definitely recommend Links Property Finance to anyone looking for a mortgage broker, especially first home buyers who want someone to guide them through the process.
Michael Google review
★★★★★
Charles and the team at links property finance recently assisted me with my purchase of my first property in Burwood. As a first home buyer, Charles made the process simple and easy. I would recommend Charles to all first home buyers
Elijah Google review
★★★★★
Paperwork and finances were never my strong suit. He has made this process as simple and dummy proof for me as humanly possible. This is not the first time I use a mortgage broker, however it was the easiest and most pleasant.
Mikhail Google review

Talk to a broker about your Russell Lea home loan

Bring the Russell Lea plan, the purchase, the build, the switch, and leave with the lending mapped: which lenders fit, what it costs monthly and what to do first. Free, no obligation.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A Links Property Finance client in front of the sold sign at the first home she bought

Family streets with project potential

A family on the porch of their home
  • Links Property Finance serves Russell Lea within the Inner West service area, by phone, video and in person when useful, and upfront that this is coverage, not a shopfront.
  • The suburb’s stock is classic between-the-wars: solid cottages and semis on blocks generous enough to interest builders.Some owners renovate and stay; a growing number rebuild as dual occupancy. Both paths run through the same first question, what will a lender fund, and how.

Dual occupancy is three decisions, not one

A family together in their backyard
  • A duplex project stacks a demolition, a construction loan and an exit strategy: keep both, sell one, sell both.Each exit changes the right structure, and the tax and subdivision treatment, which belong with your accountant and conveyancer from the start.
  • Lenders fund these routinely on fixed-price contracts with staged drawdowns.What they price carefully is the end value of two dwellings against the debt, and your capacity to carry the project if the sale side runs slow.

Russell Lea between Lyons Road and Iron Cove

Russell Lea has no railway station. Lyons Road and Hampden Road are its main roads, and the Bay Run follows Henley Marine Drive along the Iron Cove shore. Homes facing Iron Cove have fewer direct comparisons, which the valuer has to allow for.

Demand here leans toward families who want a house and a yard, and valuers work mainly from sales of comparable houses on nearby streets.

  • Most of the suburb is houses, many of them interwar cottages and Federation homes on generous blocks, with semis and some unit blocks in the mix.
  • For a Russell Lea knock-down and rebuild, Links sets lenders such as ANZ, Westpac, Macquarie, ING and Resimac side by side and recommends the one whose construction policy suits the builder’s contract and the chosen exit.
Read the full detail

Most of the suburb is houses, many of them interwar cottages and Federation homes on generous blocks, with semis and some unit blocks in the mix. That block size is why dual occupancy keeps coming up.

A lender funds a duplex on a fixed-price contract with staged drawdowns and sizes the loan off the valuer’s end value for the completed pair, so the existing cottage matters less than what the two new homes will be worth and whether your income can carry the build.

For a Russell Lea knock-down and rebuild, Links sets lenders such as ANZ, Westpac, Macquarie, ING and Resimac side by side and recommends the one whose construction policy suits the builder’s contract and the chosen exit.

Example scenario (illustrative, not a real client): long-term owners of an interwar cottage near Lyons Road plan to demolish, build a duplex, live in one side and sell the other. Their existing mortgage has to be restructured into a construction facility before demolition, and selling one side adds a partial release to the plan.

Comparing policies finds a lender comfortable with the keep-one, sell-one exit and clear on how much debt the sale of that side must repay, so the loan is set up once, before the builder is booked.

A house with a wide front verandah

Financing a Russell Lea duplex build

The structure, from settlement to strata plan.

Read the full detail

Simply buying the house

Common questions about buying in Russell Lea

How much can I borrow for a duplex project?

It’s sized on two things: your capacity to service the debt through the build, and the valuer’s end value for the completed pair. The build cost sits between them.

Strong end values in a proven duplex market like Russell Lea help, but income carries the application, the project’s paper profit doesn’t service a loan.

Is a home facing Iron Cove harder to value?

It can take more work. Homes facing the water along Henley Marine Drive have fewer direct comparisons than the cottages further back toward Lyons Road, so the valuer has less recent evidence to lean on and the result can land further from the contract price.

It is worth allowing a buffer, keeping the contract conditional where you can, and being ready to take the file to another lender if the first valuation lands short.

Can I sell one side before the build finishes?

You can exchange off the plan on one dwelling, but settlement waits for completion and subdivision, and your lender’s consent and partial-release terms are part of the path. Presales can strengthen the application; they don’t shortcut the sequence.

Do I need a development approval before talking finance?

No, talk early: a useful finance conversation can start from concept and feasibility. A lender assessment needs the fixed-price contract, and drawdowns need certified stages, so early structuring stops you designing a project the finance cannot follow.

Is a duplex assessed differently if I keep both sides?

Yes, in the end state: the construction phase looks the same, but keeping both means servicing the full debt across two dwellings, with rent from the second usually counted at a discount.

Sell-one retires debt at settlement of the sale. Lenders assess the version you declare, changing exit mid-project is possible but is a re-assessment, not a formality.

What deposit do first home buyers need around Russell Lea?

On the entry stock, semis, the occasional villa, the ordinary pathways apply: 5% under the government scheme where price and eligibility fit, insurance-backed loans under 20%, or a family guarantee replacing cash deposit. The calculator compares all three at your price.

Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.