




Call Charles Book a meeting
Mortgage Broker Seven Hills

Links Property Finance · Home loans in Seven Hills and across Sydney: Mortgage Broker in Seven Hills

Seven Hills is a family suburb on the rail line, and its full blocks are its biggest asset.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Buying a house in Seven Hills: how much can you borrow?

As much as your income supports after living costs and debts, tested at a rate about 3 per cent above the one you would pay.

Read more

The block matters for what comes next: a full Seven Hills block can carry an extension or a granny flat, and lenders can count part of a granny flat’s rent toward future borrowing.

A Federation-era house with a tiled roof and front garden
In Seven Hills, houses make up 84.1% of homes, terraces and semis 9.9% and apartments 5.6% (ABS Census 2021).

How a lender reads an address in Seven Hills

Houses are 84.1% of the stock in Seven Hills. Owners here often build equity faster than they expect, which opens a top-up, a renovation or help for family later.

  • Postcode2147
  • CouncilCity of Blacktown
  • From the Sydney CBD33 km north west
5.6%

apartments NSW 21.7%

84.1%

separate houses NSW 65.6%

9.9%

terraces and semis NSW 11.7%

35.3%

rented NSW 32.6%

34.6%

with a mortgage NSW 32.5%

7,539

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL13533).

Terrace houses along a tree-lined street

Borrowing power for a Seven Hills purchase

How much could you borrow?

$140,000
None

What moves the number

Choose any that apply. Each shows roughly how much it changes the figure, the way a lender’s assessment would.

$635,000

is an indicative borrowing figure at today’s typical rates. Lenders typically count around 80% of rental income, which is why an investment purchase can lift your number, your real figure comes from a proper assessment.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
A huge thank you to Charlie for his exceptional support and expertise throughout the process of securing finance for my first home.
Julian Google review
★★★★★
Highly recommend Charles! Professional, knowledgeable and very easy to work with. He helped us navigate the home loan process and found a great solution that suited our needs. Excellent service from start to finish.
Daniel Google review
★★★★★
Had a great experience with Charles at Links Property Finance. He made the whole home loan process straightforward and easy to understand, kept me updated throughout and was always quick to answer any questions.
Louie Google review

Helping buyers and owners in Seven Hills

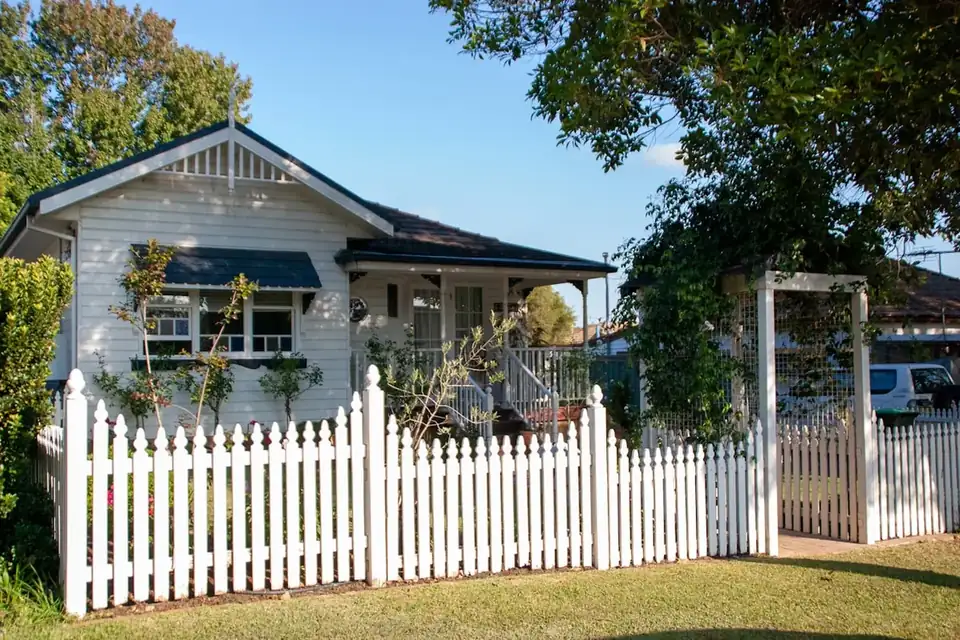
A weatherboard house in Sydney
  • Links Property Finance works across Western Sydney by phone, video and in person when it helps.Seven Hills files skew practical: first buyers stretching from a unit to a house, families upgrading within the suburb, and long-term owners deciding what to do with equity and a large backyard.
  • The station does real work for values, and the housing stock, mostly established brick homes on generous lots, finances conventionally, which keeps most files refreshingly straightforward.

Blocks with a second act

A family together in their backyard
  • A granny flat is the west's quiet wealth-builder and Seven Hills blocks were made for it: an approved secondary dwelling funded through equity release with staged builder payments, whose rent then counts toward serviceability at many lenders.
  • Extensions follow the same logic at smaller scale, and where zoning supports it, a knock-down duplex is a construction finance question assessed on the completed pair's end value.Each needs the ownership and structure settled before builders are booked.

Seven Hills station and the full blocks around it

Seven Hills station sits on the main western rail line between Toongabbie and Blacktown, with a large commuter car park and bus routes running from the station, and trains through Parramatta to the city.

For lending, that rail access feeds two things: steady demand from families, which gives valuers plenty of comparable house sales nearby, and tenant interest in approved granny flats, whose rent needs evidence before a lender will count it toward servicing.

  • Seven Hills is overwhelmingly freestanding houses, many of them mid-century single-storey homes on large blocks and some already replaced by newer two-storey brick homes, with townhouses and villas as the lower-priced entry and very few apartments.
  • Links compares lenders including ANZ, Westpac, Macquarie, ING and Resimac, so a Seven Hills purchase, extension or granny flat build can go to one whose policy suits the plan for the block.
Read the full detail

Seven Hills is overwhelmingly freestanding houses, many of them mid-century single-storey homes on large blocks and some already replaced by newer two-storey brick homes, with townhouses and villas as the lower-priced entry and very few apartments.

That makes most purchases a house on its own title, and the lending question shifts to the block: whether the valuer finds condition issues, whether unapproved works are on the site, and how a granny flat or extension would later be funded.

Links compares lenders including ANZ, Westpac, Macquarie, ING and Resimac, so a Seven Hills purchase, extension or granny flat build can go to one whose policy suits the plan for the block.

Example scenario (illustrative, not a real client): a couple with young children buy a single-storey brick home on a full block a short walk from Seven Hills station, planning to add an approved granny flat and rent it out.

They need to know now whether the build can be funded from equity later and how much of the eventual rent a lender will count.

Comparing policies before settlement shows which lenders suit that two-step plan, so the purchase loan is structured with the build in mind rather than refinanced a year later.


A brick house with a gabled roof

Buy the house, plan the block

Seven Hills lending questions are usually about the next five years, not just the purchase.

First home buyers in Seven Hills

A freestanding first home, still realistic, with the supports applied.

  • The 5% Deposit SchemeThe $1.5 million cap clears the local market comfortably, houses included. Five per cent down, no lender's insurance. Check eligibility.
  • Stamp duty reliefThe $800,000 exemption catches a real share of Seven Hills houses; the concession runs to $1 million. Run your price.
  • Family supportGuarantees and documented gifts close deposit gaps here every month, papered properly.
  • Townhouse alternativesWhere the freestanding stretch does not close yet, local townhouses buy the suburb at a lower entry price.

Common questions about buying in Seven Hills

Does granny flat rent count toward my loan?

At many lenders, yes: an approved secondary dwelling with rental evidence contributes to serviceability, discounted at each lender's own rate. That discount varies enough between lenders to change an approval, which makes it another placement question. The build itself typically funds through equity release with staged payments.

How is a Seven Hills townhouse financed compared with a house?

Townhouses are usually strata or community title, so the lender looks at the scheme as well as the home: levies, the sinking fund and any shared driveway or building issues.

A house on its own title skips that step and is judged on land, condition and comparable sales. Both can work with the 5% Deposit Scheme where you are eligible and the price fits the cap, and a townhouse often brings the suburb within reach sooner.

Should we extend or move?

It comes down to build cost plus contingency against purchase price plus stamp duty: extending avoids duty and keeps the street you chose, while moving buys someone else’s finished work at a completed-home price. We price both, and the construction guide covers how staged funding works.

Can a first home buyer get a house here?

Yes. Seven Hills prices sit inside the 5% scheme's cap with room, and a meaningful share of the housing stock falls under the $800,000 duty exemption. Add family support, which is common locally, and the deposit maths closes more often than people expect.

What should the building report tell me?

On a Seven Hills house, look for roof and structural condition, termite history and any additions built without approval, because a valuer may discount unapproved work and it can affect insurance.

Is the block size worth paying more for?

It is the local asset. A full block supports a granny flat, an extension or, where zoning allows, a duplex, and those options are what turn a house into a plan.

Whether it is worth the premium depends on whether you will use it, which is worth deciding before you bid rather than after.

Talk to a broker about your Seven Hills home loan

Bring your Seven Hills plans to a free 30-minute call: your borrowing range, the lenders that fit the property and your next step.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.



