



Call Charles Book a meeting
Mortgage Broker Baulkham Hills

Links Property Finance · Home loans in Baulkham Hills and across Sydney: Mortgage Broker in Baulkham Hills

Baulkham Hills is the Hills' established core: family homes on generous blocks, held long and renovated often.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Family property in Baulkham Hills: equity, a guarantee or a granny flat?

Equity, a guarantee and a granny flat each suit a different family plan. Baulkham Hills blocks are large, so the block often shapes the loan as much as the borrower.

Read more

Equity in a parent’s home can fund a child’s deposit or a guarantee, usually with no mortgage insurance; a granny flat adds a home on the same block, financed as a construction loan.

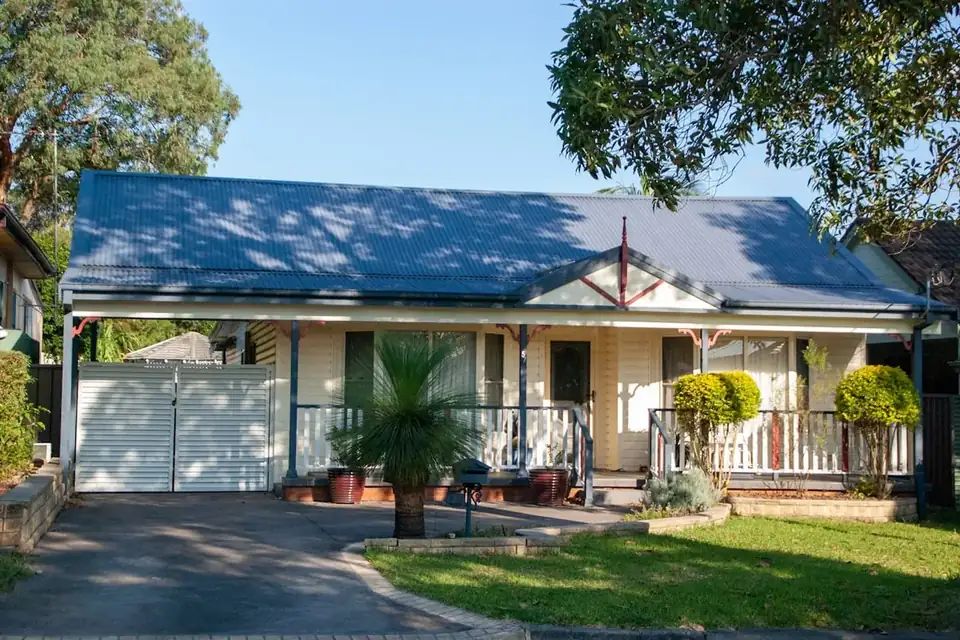
A blue-roofed house with a front path
Baulkham Hills housing mix: 75.4% houses, 13.3% terraces and semis, 11.3% apartments (ABS Census 2021).

How a lender reads an address in Baulkham Hills

Houses are 75.4% of the stock in Baulkham Hills. With little strata to assess, the lending questions tend to be about the buyer and the block, not the building. Just over four in ten homes are owned with a mortgage, above the 32.5% across NSW. Plenty of those owners are now upgrading, refinancing or helping the next generation in.

Baulkham Hills is an owner-occupier suburb: just 22.3% of homes are rented. Households tend to stay put, so listings are fewer and being pre-approved before you look matters more than usual.

  • Postcode2153
  • CouncilThe Hills Shire
  • From the Sydney CBD28 km north west
11.3%

apartments NSW 21.7%

75.4%

separate houses NSW 65.6%

13.3%

terraces and semis NSW 11.7%

22.3%

rented NSW 32.6%

43.0%

with a mortgage NSW 32.5%

13,155

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL10233).

A corner cottage with a hedge

Usable equity on a Baulkham Hills home

Home equity calculator

Home equity calculator

For upgraders and investors, how much of your home could work as a deposit.

$1,100,000
$600,000
  • Total equity$500,000
  • Usable equity (to 80% LVR)$280,000

That usable equity could work as a deposit on an investment property or renovation, structured so your properties aren’t tied together unnecessarily.

Usable equity assumes lending to 80% of your home’s value against your current loan. Lender policy and serviceability decide the real figure.


Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Had a really good experience with Charles at Links Property Finance. He was easy to deal with, always quick to respond and kept everything simple and clear throughout the whole process. You can tell he genuinely cares about getting the best outcome for his clients rather than just getting things done quickly. Really happy with the experience and would happily recommend Charles and Links Property Finance to anyone.
Christian Google review
★★★★★
Charles is an absolute star at what he does. He was straight-up, highly professional, and worked hard to secure a fantastic rate for our home loan. Communication was prompt and clear the entire way through. I would trust him with any future financial needs
Alan Google review
★★★★★
Had a great experience with Charles. He made the home loan process straightforward, was always easy to communicate with, and really knew his stuff. Would definitely recommend Charles and the team!
Jacob Google review

Helping buyers, owners and families in Baulkham Hills

A family on the porch of their home
  • Links Property Finance works across the Hills by phone, video and in person when it helps.Baulkham Hills files often involve more than one generation: parents guaranteeing first purchases, grandparents' homes gaining granny flats, blocks big enough to raise the duplex question when the family outgrows the house.
  • It is also a strong family-home market, upgraders arriving from closer in, locals trading up within the suburb, and the ordinary lending those moves need, done well.

Blocks that can do more

A family together in their backyard
  • Baulkham Hills blocks routinely support secondary dwellings, and increasingly host them: granny flats for parents or renters, studios for adult children, and the occasional knock-down duplex where zoning allows.
  • The lending is standard once structured: equity release funds most granny flats, construction finance handles bigger builds, and approved secondary-dwelling rent counts toward serviceability at many lenders.The structure conversation, ownership, guarantees, exits, is the part families skip and shouldn't.

Baulkham Hills, the Hills Motorway and the family block

Baulkham Hills has no railway station of its own. Transport matters less to a lender here than in a station suburb, because most homes are houses valued on land.

  • The stock is mostly established family homes on generous blocks, with townhouses and fewer apartments.
  • Links weighs lenders such as ANZ, Westpac, Macquarie, ING and Resimac against each other, so a guarantee, a granny flat build or an upgrade in Baulkham Hills goes where the policy suits the family and the block.
A brick bungalow with a tidy front lawn

Refinancing and releasing equity in Baulkham Hills

More than four in ten Baulkham Hills homes are owned with a mortgage, above the state figure, and many families have held their homes long enough to build real equity. That equity is often what supports a child’s purchase through a guarantee.

Releasing equity is assessed on its purpose: renovating, building a granny flat, helping family or investing each bring different questions. A reprice request to your current lender is the first step. Start with a loan health check.

A terrace with an iron-lace balcony

How does investment lending work in Baulkham Hills?

With no station of its own, a Baulkham Hills investment is valued mostly on the house and land, and rent is appraised against comparable local homes rather than distance to a platform.

A granny flat can add rental income, which lenders count at a discount that varies between them. Townhouses bring levies into the numbers as well. Investment lending.

Valuations in Baulkham Hills: what moves the number

On a Baulkham Hills house the valuer responds to the land, the condition of the home and any approved extensions. A larger block can occasionally bring a lender’s rural-residential policy into play.

Unapproved works, such as an enclosed patio or a converted garage, can pull a valuation down or be left out of it. Having approvals on hand helps. What to do about a low valuation.

Self-employed and professional borrowers in Baulkham Hills

Many Hills families run their own businesses, and lenders read the financials rather than payslips. Add-backs can lift the figure used, and a current year of strong trading helps with some lenders.

Parents who are self-employed and acting as guarantors are assessed on their own financials too. Self-employed lending.

A brick house with a gabled roof

Family lending, structured

The suburb's signature files, and how each one is built properly.

First home buyers in Baulkham Hills

Townhouses and units keep the entry open, and family equity does local heavy lifting.

  • The 5% Deposit SchemeThe $1.5 million Sydney cap covers Baulkham Hills townhouses and units, and touches houses. Five per cent down, no lender's insurance. Check eligibility.
  • Stamp duty reliefExemption to $800,000, concession to $1 million, working bands for the townhouse market. Run your figure.
  • The guarantor patternThe suburb's most-used first-home tool: family equity closing the deposit gap, with insurance skipped entirely. How it works.
  • Gifted depositsDocumented properly, family gifts satisfy lenders readily, the paperwork that makes them count.

Common questions about buying in Baulkham Hills

How does a parent guarantee work?

The parents' property secures a defined slice of the child's loan, closing the deposit gap and usually eliminating lender's insurance, and the guarantee releases once repayments and value bring the loan-to-value ratio inside the lender's threshold.

The exit is the design point: a guarantee without a planned release is a liability, not a favour. The full mechanics.

Do lenders treat a Baulkham Hills townhouse differently from a house?

They can. A house on its own block is the simplest security a lender takes. A townhouse may sit in a strata or community scheme, which brings that scheme’s records, levies and building insurance into the assessment, and some lenders apply different rules to it.

In Baulkham Hills, where townhouses are often the entry point for first home buyers, checking the title type before you offer tells you which lenders to approach.

Can we put a granny flat in the backyard for my parents?

Commonly, yes, subject to approval, and the finance is usually a straightforward equity release with staged payments to the builder. Two design questions deserve answers first: whose name holds what, and what happens if circumstances change. Ten minutes of structure now prevents years of mess later.

What's involved in building a duplex on our block?

Zoning first, council or complying development approval, then construction finance shaped by end value: the lender assesses the completed pair, funds the build in stages, and expects a contingency.

Whether you keep both, sell one or sell both changes the structure and the tax posture, decided before the application, not at completion. The construction guide.

Is Baulkham Hills still upgrade territory or is it priced out?

Still upgrade territory: it remains the Hills’ most liquid family-home market, with stock turning over more than in the premium pockets and constant trade-ups within the suburb. Loans reach modern Sydney sizes, so lender placement matters.

We're buying with my parents, one big house for everyone. How does that work?

Better than most people fear, if structured deliberately: joint borrowing with contributions formalised, title held as tenants in common in defined shares, and wills aligned with the arrangement.

Lenders handle multigenerational applications routinely; the risk is families who leave the paperwork to goodwill. We design the lending; your solicitor papers the rest.

Talk to a broker about your Baulkham Hills home loan

Thirty minutes with Charles: what you could borrow, which lenders suit Baulkham Hills property and what to do next. Free, with no credit check.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.







