Call Charles Book a meeting
Mortgage Broker Castle Hill

Links Property Finance · Home loans in Castle Hill and across Sydney: Mortgage Broker in Castle Hill

Castle Hill is the Hills at its most established: substantial family homes on real blocks, decades of equity in their walls.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Upgrading to a Castle Hill family home: how do you use the equity you have?

Release equity from your current home as a separate loan for the deposit and costs, then decide whether to sell first, buy first with a bridging loan, or keep the old home as an investment.

Read more

Castle Hill upgrades often reach large loan sizes, so the lender’s debt-to-income limits matter as much as the rate.

A red-roofed house on a quiet street
Castle Hill housing mix: 73.7% houses, 10.9% terraces and semis, 15.3% apartments (ABS Census 2021).

Castle Hill by its homes

Castle Hill is house country: 73.7% of dwellings are freestanding, against 65.6% for NSW. Owners here often build equity faster than they expect, which opens a top-up, a renovation or help for family later. Most of Castle Hill owns rather than rents, with only 22.9% of homes leased.

Long tenures mean plenty of equity in the street, which is often what funds the next purchase or a family guarantee. 14,345 homes means plenty of comparable sales for a valuer to work from in Castle Hill.

  • Postcode2154
  • CouncilThe Hills Shire
  • From the Sydney CBD31.9 km north west
15.3%

apartments NSW 21.7%

73.7%

separate houses NSW 65.6%

10.9%

terraces and semis NSW 11.7%

22.9%

rented NSW 32.6%

37.4%

with a mortgage NSW 32.5%

14,345

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL10846).

A brick bungalow with a tidy front lawn

How much equity could you use in Castle Hill?

Home equity calculator

Home equity calculator

For upgraders and investors, how much of your home could work as a deposit.

$1,100,000
$600,000
  • Total equity$500,000
  • Usable equity (to 80% LVR)$280,000

That usable equity could work as a deposit on an investment property or renovation, structured so your properties aren’t tied together unnecessarily.

Usable equity assumes lending to 80% of your home’s value against your current loan. Lender policy and serviceability decide the real figure.


Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
I found Charles and Links Property Finance very prompt and professional to deal with. Made it all so easy.
Marg Google review
★★★★★
Charles and the team recently assisted me with the refinance of my investment property.
Max Google review
★★★★★
Had a great experience with Charles. He made the home loan process straightforward, was always easy to communicate with, and really knew his stuff. Would definitely recommend Charles and the team!
Jacob Google review

Talk to a broker about your Castle Hill home loan

Thirty minutes with Charles: your equity, your sequence, what the next Castle Hill move costs and how to structure it. Free, no credit check.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A Links Property Finance client in front of the sold sign at the first home she bought

Helping buyers, owners and upgraders in Castle Hill

A family on the porch of their home
  • Links Property Finance works across the Hills by phone, video and in person when it helps.Castle Hill files skew established: families trading up within the suburb, owners renovating rather than leaving, and long-term holders whose homes now carry equity that deserves a plan.
  • The new line changed the suburb's edges, apartments near the station created an entry price point and an investor market, while the family-home heartland kept doing what it always did: turning over slowly and selling well.

Equity with decades behind it

A family together in their backyard
  • A Castle Hill home held since the 2000s carries equity that can fund the next purchase, a major renovation, an investment property or a child's first deposit, if it is structured deliberately.Released badly, it just makes the bank more secure.
  • The instruments are standard, refinance, supplementary loans, family guarantees, and the choice between them is strategy.Start with the equity calculator, then plan against your actual goals.

Castle Hill and Hills Showground stations

Castle Hill has two stations inside the suburb: Castle Hill, opposite Castle Towers, and Hills Showground, the next stop towards Norwest. Much of the suburb’s newer apartment and townhouse supply sits around them, and lenders read those buildings very differently from the family-home heartland.

A valuer compares a station-side unit with recent sales in the same and nearby complexes, and a lender looks at the size of the building, how much lending it already holds there and the internal floor area. For investors, units near the stations make rental evidence easier to show.

Refinancing and releasing equity in Castle Hill

Many Castle Hill houses have been owned for decades, and the equity in them usually funds the next step: a bigger home, a renovation or help for children.

Lenders ask what the equity is for, and a large release may bring the lender’s larger-loan rules into play. Asking your current lender to reprice comes first. Start with a loan health check.

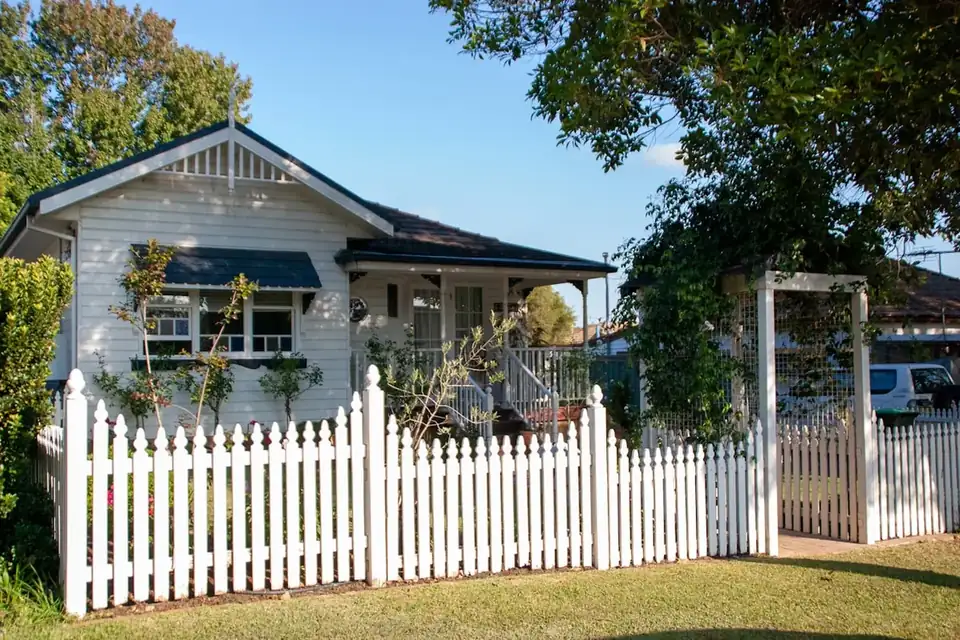
A Federation-era house with a tiled roof and front garden

How does investment lending work in Castle Hill?

Units and townhouses near Castle Hill and Hills Showground stations give investors easier rental evidence than the house streets.

Lenders count only part of the rent and look at how much they already lend in each complex. Townhouses bring levies into the numbers. Investment lending.

Valuations in Castle Hill: what moves the number

A Castle Hill house on a substantial block is valued mostly on land and condition, plus approved extensions. Alterations built without approval can pull a figure down.

Station-side units are compared with recent sales in the same and nearby complexes, and building size matters. What to do about a low valuation.

Self-employed and professional borrowers in Castle Hill

Castle Hill has many business owners and professionals, often upgrading with larger loans. Lenders read business financials, and several professions qualify for concessions.

Timing matters: a strong current year can help with some lenders, while others use the lower of the last two. Self-employed lending.

The Castle Hill upgrade

Bigger house, same suburb: the district's signature move, with the sequencing that decides how it feels.

A house with a wide front verandah

First home buyers in Castle Hill

The new apartments near the stations created an entry the suburb never had. The supports cover it.

  • The 5% Deposit SchemeThe $1.5 million Sydney cap covers the station-side apartments and townhouses comfortably. Five per cent down, no lender's insurance. Check eligibility.
  • Stamp duty reliefExemption to $800,000, concession to $1 million, live bands for Castle Hill units. Your figure.
  • Young buildingsRail-corridor blocks carry short strata records, read for levy adequacy and defects handling before you offer.
  • Family equity nearbyCastle Hill parents guaranteeing Castle Hill children is the local pattern, structured with an exit, it collapses the deposit timeline.

Common questions about buying in Castle Hill

We want a bigger house in Castle Hill. Sell ours first or buy first?

Start from two numbers: usable equity and what you can service carrying both properties briefly. Strong on both, and buy-first with bridging lets you move when the right home lists; tighter, and sell-first with a negotiated long settlement is the sound route.

We model both against your actual figures, the answer is rarely a coin flip once the numbers are on paper.

Is a townhouse near Castle towers assessed like a house or a unit?

It depends on the title more than the look. A townhouse on its own Torrens title is generally assessed much like a house, while one in a strata or community scheme adds its levies to your commitments and has its records checked as part of the application.

Townhouses around Castle Hill and Hills Showground stations can be either, so confirm the title type in the contract before you set your budget.

What can the equity in our home do?

Fund the next deposit, a renovation, an investment purchase or a child's first home through a guarantee, sometimes several of those, sequenced. The calculator gives the usable figure; the plan for it depends on your goals, which is a conversation, not a formula.

Are the new apartments near the stations a sensible first buy?

They can be: they created Castle Hill’s first real entry price point, with young-building considerations such as short strata records, settling levies and off-the-plan tranches with the usual valuation questions. Read the record, keep a buffer and choose the lender for the building.

Do Castle Hill trade-up loans hit large-loan rules?

Increasingly, yes, family homes here reach the tiers where loan-to-value bands step down and debt-to-income gets scrutinised, with each lender drawing lines differently. On these files, placing the loan is worth more than negotiating the rate. How we work them.

Is renovating smarter than moving here?

Frequently, same street, better house, no stamp duty on the upgrade. It prices as staged construction finance or a straightforward equity release depending on scale, and the comparison against buying is just arithmetic: build cost plus contingency versus purchase price plus duty. We run it, the construction guide covers the funding side.

Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.