
Links Property Finance · Refinance mortgage broker, Sydney: Refinance Checklist
Refinancing is worth doing when the numbers support it and a waste of effort when they do not.


Refinancing soon? What does the checklist that saves weeks cover?
Whether the saving beats the costs, what the switch costs in discharge, registration and lender fees, any fixed rate break cost, and the documents the new lender needs.
Read more
It also covers asking your current lender to reprice first, which costs nothing, and the order of steps from application to settlement.
Part of the refinancing guide.
From a real Links file: a refinance planned to remove a family guarantee, with the new pricing and costs checked first.

Recent Links clients
-

Sold. Her first home. Deposit, scheme and lender, sorted. -
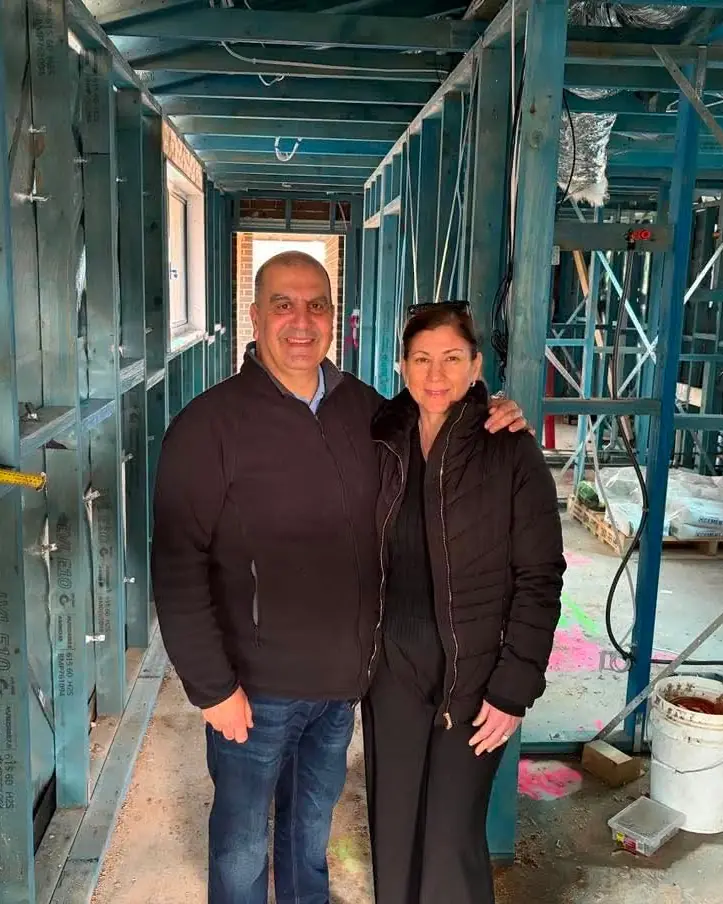
Their new home, at frame stage. Walls next. The frame is up. -
Next one
The next sold sign could be yours.
A free 30-minute call shows where you stand.
Book my free call


Charles and the team recently assisted me with the refinance of my investment property.
Had a great experience with Charles. He made the home loan process straightforward, was always easy to communicate with, and really knew his stuff. Would definitely recommend Charles and the team!
Charles is an absolute star at what he does. He was straight-up, highly professional, and worked hard to secure a fantastic rate for our home loan. Communication was prompt and clear the entire way through. I would trust him with any future financial needs
- Work out whether it is worth doing
- Find your current rate and balanceBoth are on your latest statement or in online banking. You cannot compare anything without them.
- Ask your current lender firstSometimes they will reprice to keep you, which is faster and cheaper than switching. Refinancing to a new lender should be a choice, not a reflex.
- Calculate the real savingCompare repayments at your rate against a realistic alternative, then subtract switching costs. The loan health check does the arithmetic.
- Check whether you are on a fixed rateBreaking a fixed loan can attract a break cost that outweighs the saving. Ask your lender for the figure before assuming anything.
- Count the costs of switchingDischarge fees, new lender application or valuation fees, and mortgage registration and deregistration. Modest individually, worth counting together.
- Check where you stand
- Estimate your equityThe lower your loan against the property's value, the better the pricing available. Under eighty per cent avoids mortgage insurance. The equity calculator gives a first read.
- Confirm your income is evidencedA refinance is a fresh application. If your income has changed since the original loan, particularly to self-employment or contract work, the assessment changes with it.
- Review your credit conductMissed payments in the last two years matter. So do recent applications for other credit.
- List every debt and limitThe new lender assesses all of it, including cards you no longer use and buy-now-pay-later accounts.
- Decide what you want from it
- A lower rateThe most common reason and the easiest to measure.
- Access to equityFor a renovation, an investment deposit or consolidating expensive debt. This changes the loan size and the assessment. How equity release works.
- Better structureAn offset account, splits between fixed and variable, or a shorter term. Sometimes structure is worth more than a small rate difference.
- Consolidating other debtsGenuinely useful when structured with a shorter term, quietly expensive when absorbed into thirty years. The debt consolidation guide shows both outcomes.
- Through the process
- Keep repayments currentEvery one of them, on time, throughout. A missed payment mid-application is avoidable damage.
- Expect a valuationThe new lender values the property, and that figure decides the pricing tier and how much equity is available.
- Do not close accounts earlyWait until the new loan settles and the old one is formally discharged.
- Redirect the saving deliberatelyIf the repayment drops and the money disappears into spending, the refinance achieved very little. Keeping repayments at the old level is where the benefit compounds.
Refinancing is not automatically worthwhile. Where the saving is small, the break costs are high or the loan is nearly paid off, staying put is frequently the better answer, and a good broker will tell you so.
Common questions about refinancing
How much do I need to save to make refinancing worthwhile?
Enough that the saving over your holding period clearly beats the switching costs, with a margin: a small rate difference adds up fast on a large balance but may never cover the costs on a small one.
How often can I refinance?
As often as you like, legally, but each refinance costs money and leaves a credit enquiry, and lenders notice frequent switching. For most people, a review every couple of years beats chasing every advertised rate.
Will refinancing hurt my credit score?
Only slightly: the application creates an enquiry, which is normal on its own. Repeated applications in a short period read poorly, so choose the lender before applying.
Can I refinance if my property has fallen in value?
It depends on how much equity remains. If the loan is now a high proportion of the value, options narrow and mortgage insurance may apply again. A valuation is what settles the question, and it is worth knowing before committing to a switch.
Should I refinance to consolidate debt?
Sometimes, and it needs structuring. Rolling short-term debt into a thirty-year mortgage lowers the monthly payment while potentially increasing total interest substantially. Done with a separate shorter split, it works well. Done carelessly, it is expensive comfort.
Have your file checked before you apply
Charles will tell you whether switching is worth it, including when the answer is no. Free, no credit check.
Prefer a callback? Charles calls back within one business day. No documents needed yet.





General information only, not credit or financial advice. Lender requirements and government scheme criteria differ and change over time; your position is confirmed in a full assessment.