Call Charles Book a meeting
Mortgage Broker Wareemba

Links Property Finance · Home loans in Wareemba and across Sydney: Mortgage Broker in Wareemba

Wareemba is a pocket of Federation cottages and a village strip most of Sydney has never driven through, which is exactly why people who find it stay.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Buying a Wareemba cottage to renovate: how is the work financed?

In stages. The cottage is valued as it stands, so the deposit is set on today’s condition. Cosmetic work can come from savings or redraw; structural work needs plans, quotes and either a loan top-up valued on the finished home or a construction loan.

Read more

On small lots the valuer leans on nearby sales of similar cottages.

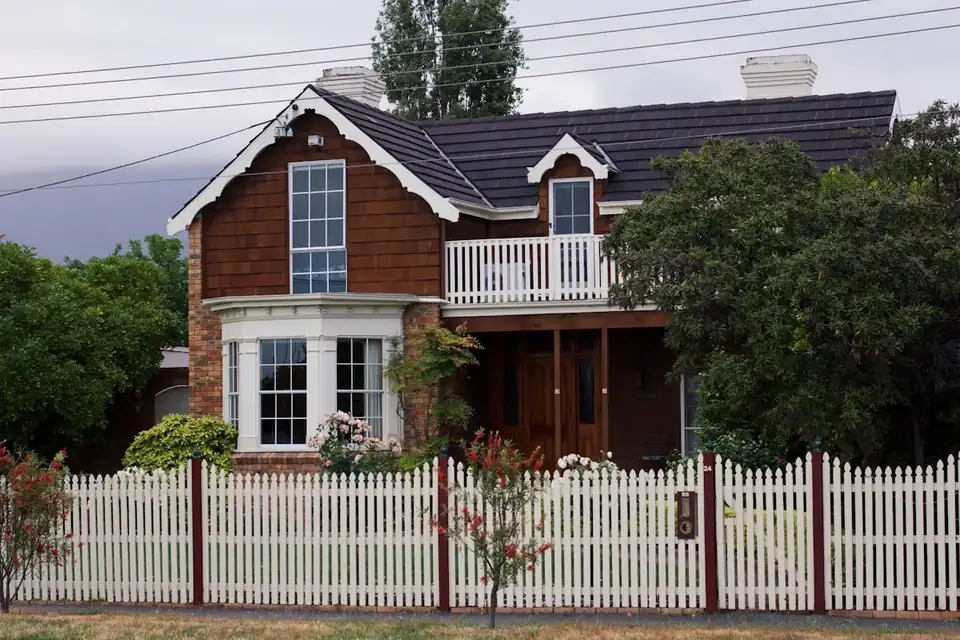
A cottage behind a picket fence
In Wareemba, houses make up 55.4% of homes, terraces and semis 9.3% and apartments 31.8% (ABS Census 2021).

How a lender reads an address in Wareemba

At 635 homes, Wareemba is one of the smaller suburbs nearby, which can make a valuation the slowest part of the loan.

  • Postcode2046
  • CouncilCity of Canada Bay
  • From the Sydney CBD10 km west
31.8%

apartments NSW 21.7%

55.4%

separate houses NSW 65.6%

9.3%

terraces and semis NSW 11.7%

27.9%

rented NSW 32.6%

27.7%

with a mortgage NSW 32.5%

635

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL14166).

A terrace with an iron-lace balcony

How much would your parents need to guarantee in Wareemba?

Quick guarantor check

Two sliders. See what your parents would need to guarantee.

Guarantor calculator

How a parent’s equity can stand in for the deposit, often with no LMI.

$800,000
$30,000
  • 20% deposit + costs target$163,500
  • Guarantee needed from family$133,500

With a family guarantee covering that portion, you could potentially buy with your $30,000 and no LMI. Costs assume NSW first home buyer duty.

Limited to this portion, secured against the guarantor’s property, released once you reach 20% equity, subject to lender approval. Indicative only, not credit advice.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Had a great experience with Charles at Links Property Finance. He made the whole home loan process straightforward and easy to understand, kept me updated throughout and was always quick to answer any questions.
Louie Google review
★★★★★
Paperwork and finances were never my strong suit. He has made this process as simple and dummy proof for me as humanly possible. This is not the first time I use a mortgage broker, however it was the easiest and most pleasant.
Mikhail Google review
★★★★★
Charles and the team recently assisted me with the refinance of my investment property.
Max Google review

The pocket between the parks

A brick house with a gabled roof in Sydney
  • Links Property Finance covers Wareemba as part of the Inner West service area, phone and video first, in person when it helps, no shopfront implied.
  • The suburb’s charm is its consistency: modest Federation and inter-war homes on compact lots, a strip of shops, water at the end of the ridge.Stock this uniform makes valuations reliable and renovations the main way owners add space and value.

Buy-then-renovate, financed properly

A family together in their backyard
  • The Wareemba pattern is buying the worst-kept cottage on a good street and improving it over years.Finance follows the same rhythm: purchase loan first, then equity release or a construction facility as the works graduate from cosmetic to structural.
  • The mistake to avoid is exhausting every dollar of capacity on the purchase, leaving nothing to fund the renovation that justified the price.Buffer is strategy here, not caution.

Great North Road, Hen and Chicken Bay and the cottage streets

Wareemba is one of Sydney’s smallest suburbs and has no railway station. Its public transport is the bus along Great North Road, past the village shops, running between Abbotsford wharf, where Parramatta River ferries call, and the city via Five Dock and Leichhardt.

Buyers come for the shops, the quiet streets and the Hen and Chicken Bay foreshore rather than a train commute. With so few homes, a valuer often draws comparable sales from Abbotsford and Five Dock too, so a close match on land, condition and street keeps the figure predictable.

  • Houses make up most of the stock, largely Federation and inter-war cottages on compact lots, with apartments accounting for most of the rest and a small share of semis.
  • Links looks across lenders such as ANZ, Westpac, Macquarie, ING and Resimac, so a Wareemba cottage and the renovation that follows can sit with a lender whose valuation and construction settings suit both.
Read the full detail

Houses make up most of the stock, largely Federation and inter-war cottages on compact lots, with apartments accounting for most of the rest and a small share of semis.

For the cottages, the lending turns on condition, any past works done without approval, and how a renovation will be funded, because the price and the works budget have to fit one plan. The apartments bring the familiar strata checks: sinking fund, levies and internal size.

Links looks across lenders such as ANZ, Westpac, Macquarie, ING and Resimac, so a Wareemba cottage and the renovation that follows can sit with a lender whose valuation and construction settings suit both.

Example scenario (illustrative, not a real client): a couple renting in Five Dock find a dated two-bedroom cottage in Wareemba near the Great North Road shops, with a working kitchen but a rear addition that was never approved.

They want to buy now and add a bedroom later. Comparing lender policies on unapproved works, older homes and staged construction lending shows how much to borrow at purchase and how much capacity to keep for the build.


A red-roofed house on a quiet street

Renovating a Wareemba cottage: the finance mechanics

Matching money to the way old-house projects run.

Read the full detail
A house with a wide front verandah

First home buyers in Wareemba

The compromise pick that isn’t one, a cottage suburb still priced where first buyers can reach.

  • Cottage entry pointsUnrenovated homes here remain among the Inner West’s accessible house buys. The 5% Deposit Scheme’s Sydney cap covers much of this market for eligible buyers. Check the scheme.
  • Duty positionAround the $800,000 exemption and $1 million concession lines, small price differences change the cash-to-complete meaningfully. Price your duty.
  • Condition and the valuerLenders finance “livable but tired” happily. Genuine disrepair, no working kitchen or bathroom, can push a property outside standard policy, so the worst fixer-uppers need the lender chosen accordingly.
  • Reno headroomBorrow for the house, plan for the works: a purchase structured with future equity release in mind beats maxing out day one.

The move-up within the pocket

Common questions about buying in Wareemba

Will a lender finance a run-down cottage?

Usually, if it is livable: most lenders fund dated homes, but a missing kitchen, an unusable bathroom or structural failure pushes it toward specialist or renovation-conditioned lending. The building report tells you which side of the line you are on before the application does.

Does having no railway station affect a Wareemba loan?

Not in itself. Lenders look at the home, its title and your own finances, and none of those depends on having a station nearby.

Transport shows up in the evidence instead: buyers here value the Great North Road buses and the ferry at nearby Abbotsford wharf, and a valuer compares a Wareemba home with recent sales of similar homes close by, often including Abbotsford and Five Dock. For an investor, the rental appraisal should reflect those local options rather than a train commute.

Should I borrow extra upfront for renovations?

Sometimes, if the works are immediate and quoted, a purchase-plus-renovation structure funds both from day one. If the renovation is a someday plan, buying with headroom and releasing equity when you’re ready usually beats borrowing early and paying interest on intentions.

How do I avoid over-capitalising on a small block?

Let the street set the ceiling: look at what fully renovated equivalents sell for nearby, subtract your purchase price, and treat the gap as the sensible works budget. Wareemba’s consistent stock makes this arithmetic unusually reliable, the data is three doors away.

Can first home buyers use the 5% scheme on an older house?

Yes: established houses are eligible, subject to the price cap and your eligibility. Condition matters only as far as the lender’s ordinary security standards; the scheme itself does not mind the avocado bathroom.

What’s the right order: inspection, offer, finance?

Finance groundwork first, pre-approval sets your ceiling. Then building and pest on the serious candidate, then the offer with the report’s findings priced in. At auction, all of it happens before the day, because the hammer removes your conditions.

Talk to a broker about your Wareemba home loan

One free call covers what you could borrow in Wareemba, the lenders that suit the property you want and the order to do things in.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.