





Call Charles Book a meeting
Mortgage Broker Tempe

Links Property Finance · Home loans in Tempe and across Sydney: Mortgage Broker in Tempe

Two in three Tempe homes are separate houses, and more than four in ten are owned with a mortgage, well above the NSW figure.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Buying near the Cooks River in Tempe: what do lenders ask about flooding?

Whether the property is flood affected under council planning, and whether it can be insured at a reasonable cost. Lenders require building insurance from settlement, so getting a quote before you exchange avoids a surprise. Flood planning certificates come through the contract and council.

A row of red-brick terraces
Of Tempe's homes, 67.5% are houses, 26.6% terraces and semis and 5.0% apartments (ABS Census 2021).

The housing mix in Tempe

Two thirds of the homes in Tempe are separate houses on their own block. Valuers have plenty of comparable house sales to lean on, which tends to make valuations predictable. Terraces and semis are a familiar sight in Tempe, at 26.6% of the housing.

Shared walls and older building fabric are where a building report earns its fee. Mortgaged homes are 42.2% of the stock, well above the state figure. Plenty of those owners are now upgrading, refinancing or helping the next generation in.

  • Postcode2044
  • CouncilInner West Council
  • From the Sydney CBD9 km south
5.0%

apartments NSW 21.7%

67.5%

separate houses NSW 65.6%

26.6%

terraces and semis NSW 11.7%

25.5%

rented NSW 32.6%

42.2%

with a mortgage NSW 32.5%

1,410

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL13800).

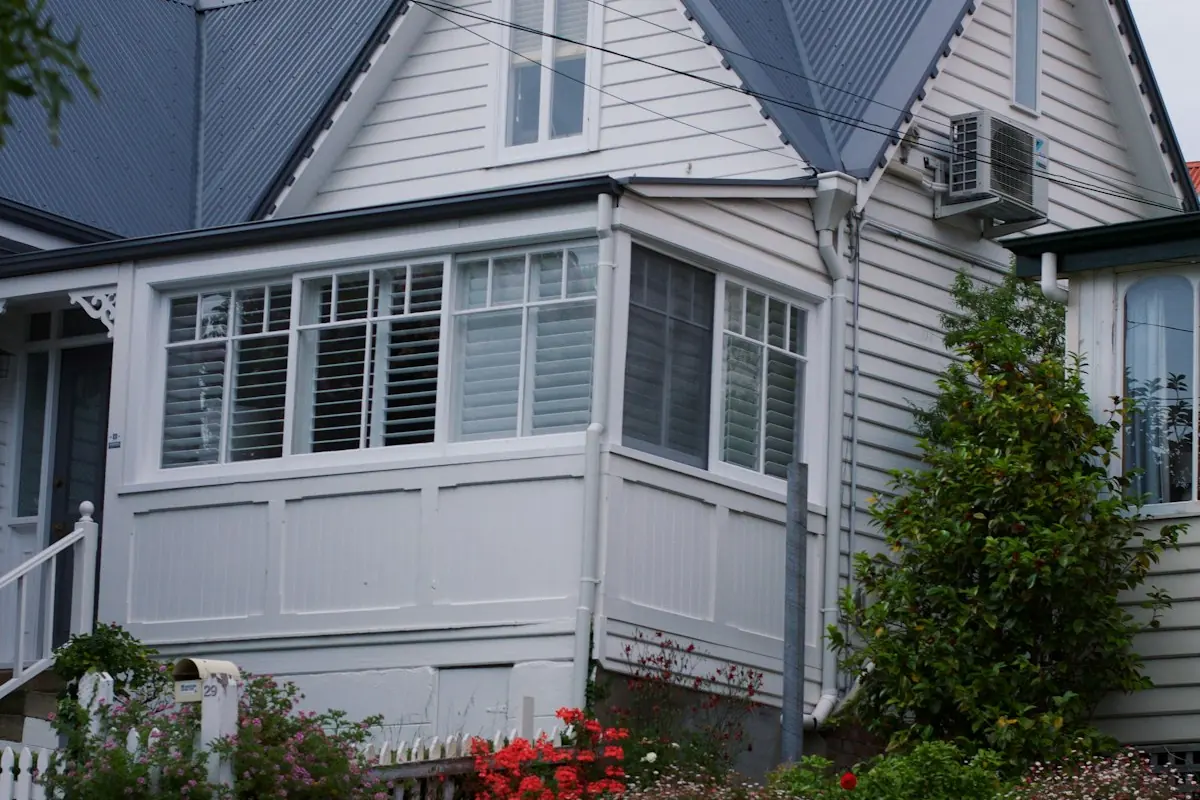
A corner cottage with a hedge

Can I get a better rate on a Tempe home loan?

Calculate your savings

$550,000
6.40%
25
6.00%

Example rates only, not current advertised rates. Set both sliders to your own figures.

Interest at 6.40%Interest at 6.00%
You could save$40,706≈ $1,628 a year in repayments
Current repayments$3,679/month
New repayments$3,544/month

Over the remaining term, before switching costs and fees, we model those before recommending a move. Estimates only, not credit advice.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles at Links Property Finance made buying our first home so much easier than we expected. As first home buyers, we had a lot of questions around borrowing capacity, our deposit and the different government schemes available to us. Charles explained everything clearly, compared different lenders and kept us updated throughout the whole process. He was always easy to reach and made sure we understood what was happening from pre approval right through to getting our home loan approved. We would definitely recommend Links Property Finance to anyone looking for a mortgage broker, especially first home buyers who want someone to guide them through the process.
Michael Google review
★★★★★
Highly recommend Charles! Professional, knowledgeable and very easy to work with. He helped us navigate the home loan process and found a great solution that suited our needs. Excellent service from start to finish.
Daniel Google review
★★★★★
Charles looked after us really well and his knowledge gave us the confidence to purchase our property. He wasn’t pushy and always ensured we felt comfortable with the repayments.
Sandra Google review

Flood planning and insurance in Tempe

A lender needs the property insured from settlement, usually with the lender noted on the policy, and it will not settle without it.

For homes near a river, the cost and availability of cover can depend on flood risk, so it is worth getting an insurance quote before you commit rather than after. Our guide to flood and bushfire prone property explains how lenders treat it.

The planning certificate attached to the contract states whether flood-related development controls apply to the land. That information matters for renovations and for your own reassurance, and in some cases it can affect the valuation.

Reading it early, and asking your conveyancer about anything unclear, avoids surprises. Questions to ask before you offer

A brick house with a gabled roof

Houses and the river in Tempe

A Sydney house with a front verandah
  • Links Property Finance is based in Enfield, with conversations by phone and video.The first one is about the home you are considering and the checks worth doing before you commit.
  • More than four in ten Tempe homes are owned with a mortgage, against about a third across New South Wales.Many owners here are mid-loan, so a review of an older loan is often worthwhile too.

Insurance before settlement

Keys being handed over
  • Lenders require building insurance from settlement.The policy must be in place, usually with the lender noted, before the loan will settle.
  • Get a quote before you commit.For homes near the river, flood cover can affect the premium, and a quote shows the real ongoing cost.

The Cooks River, the Alexandra Canal and Tempe housing

Tempe lies about nine kilometres south of the city in Inner West Council, on the northern bank of the Cooks River, where the Wolli Creek waterway also meets the river. The Alexandra Canal separates it from Sydney Airport. Tempe station is on the Illawarra line.

Its commercial strip runs along the Princes Highway, including the Tempe Hotel and the Riverview Hotel, first built in 1922, and Unwins Bridge Road is its other main road.


Reading the flood information

In New South Wales the planning certificate from the council is attached to the contract for sale, and it states whether the land is subject to flood-related development controls, among other planning matters.

Councils also publish flood studies and maps for areas along rivers and creeks.

If flood controls apply, they mainly shape what you can build or change, such as floor levels for new work. Your conveyancer can explain what applies to a particular property. Questions before you offer.

Terrace houses along a tree-lined street

Insurance and affordability

Insurance is an ongoing cost of owning, and lenders include it in your living expenses. Where flood cover lifts the premium, it affects how much you can comfortably borrow as well as your monthly budget.

Getting a quote for the specific address before you commit is the simplest way to know the real cost. Estimate the cost of owning.

Renovating in a flood planning area

Where flood-related controls apply, extensions and new buildings may need to meet requirements such as minimum floor levels, which can affect the design and cost. Lenders funding renovation work want the approvals in place, and the approval will reflect those controls.

Allowing for them in the budget from the start keeps a construction loan on track. Renovation lending.

House, semi or apartment?

Three kinds of Tempe home, and what each means for the loan.

  • House. Two in three homes here, usually on their own title and straightforward security. Check flood information and insurance for the specific address.
  • Semi. About a quarter of homes, sharing a wall and often a smaller lot. Insurance and repairs may involve your neighbour as well as you.
  • Apartment. A small share of homes here, with building insurance held by the strata scheme. Read the strata report and check the levies.

What should I check before buying in Tempe?

The checks that matter in a riverside suburb.

  • The planning certificateCheck for flood-related development controls.
  • An insurance quoteFor the specific address, before you commit.
  • The building reportIncluding any signs of past water damage.
  • Council flood informationFlood studies and maps for the area, where published.
  • Your full budgetInsurance, rates and upkeep alongside the loan.
  • Your current loanIf you already own, check whether it is still competitive.

Common questions about buying in Tempe

Do I need insurance before my loan settles?

Yes. Lenders require building insurance from settlement, usually with the lender noted on the policy, and will not settle without it. For an apartment, the strata scheme holds the building insurance, and you insure your contents.

How do I find out if a Tempe property is in a flood area?

The planning certificate attached to the contract states whether flood-related development controls apply to the land. Councils also publish flood studies and maps, and your conveyancer can explain what applies to a particular property.

Will flood risk stop a lender approving my loan?

Not usually by itself. Lenders need the property to be insurable and acceptable as security. Flood risk can affect insurance cost and, in some cases, the valuation, so checking both before you commit is sensible.

Does insurance cost affect how much I can borrow?

It can. Lenders include insurance in your living expenses, so a higher premium reduces the income available for repayments. Getting a quote for the specific address shows the real figure.

Can I renovate a house with flood controls?

Usually, but the work may need to meet requirements such as minimum floor levels, which affect the design and cost. The approval will reflect those controls, and a lender funding the work wants the approval in place.

I bought in Tempe a few years ago. Should I review my loan?

It is often worthwhile. More than four in ten Tempe homes are owned with a mortgage, and a loan taken out a few years ago may no longer be priced competitively. Asking your lender to review the rate, then comparing the answer, is a simple first step.

Talk to a broker about your Tempe home loan

Bring your Tempe plans to a free 30-minute call: your borrowing range, the lenders that fit the property and your next step.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.



