Call Charles Book a meeting
Mortgage Broker The Ponds

Links Property Finance · Home loans in The Ponds and across Sydney: Mortgage Broker in The Ponds

The Ponds is a young estate suburb where most homes are separate houses and more than six in ten are owned with a mortgage.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

A permanent resident buying in The Ponds: what do lenders and the schemes allow?

Much the same as a citizen. A permanent resident needs no foreign investment approval, usually pays no NSW surcharge purchaser duty and can use the 5% Deposit Scheme, provided every applicant on the loan is a citizen or permanent resident.

Read more

Recent time overseas can bring the surcharge into play, so check your status first.

A row of red-brick terraces
Of The Ponds' homes, 83.7% are houses, 15.7% terraces and semis and 0.0% apartments (ABS Census 2021).

What The Ponds is built of

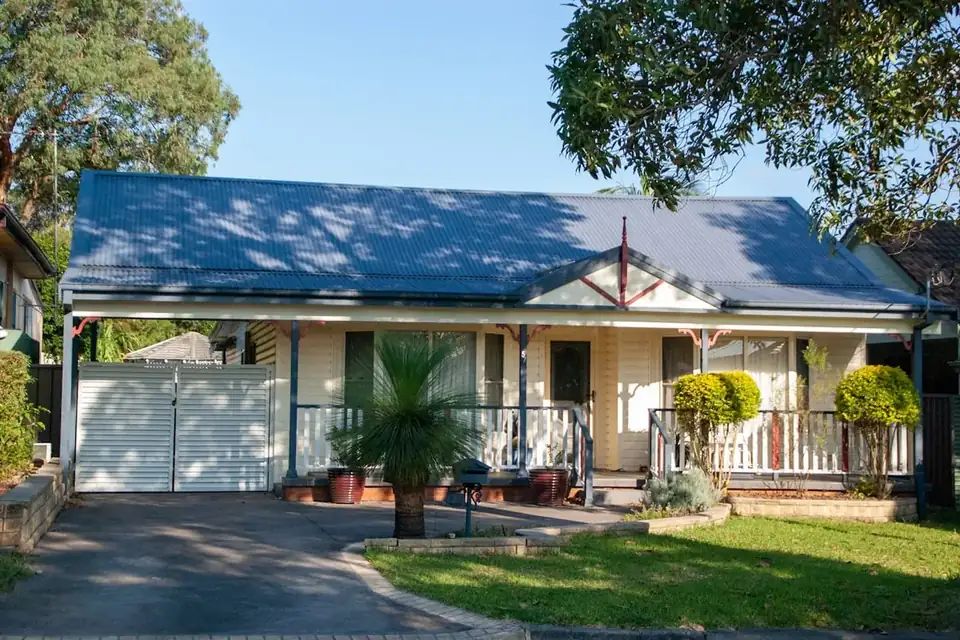
The Ponds is house country: 83.7% of dwellings are freestanding, against 65.6% for NSW. A house on its own title is the simplest security a lender takes, and the land carries most of the value.

Just over six in ten homes are owned with a mortgage, above the 32.5% across NSW. Lenders compete hard for borrowers like these, which is leverage worth using when the fixed term ends.

Most of The Ponds owns rather than rents, with only 21.9% of homes leased. Fewer rentals also means less investor competition at auction than in apartment suburbs nearby.

  • Postcode2769
  • CouncilCity of Blacktown
  • From the Sydney CBD40 km north west
0.0%

apartments NSW 21.7%

83.7%

separate houses NSW 65.6%

15.7%

terraces and semis NSW 11.7%

21.9%

rented NSW 32.6%

62.3%

with a mortgage NSW 32.5%

4,770

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL13851).

A brick bungalow with a tidy front lawn

What could a 5% deposit get you in The Ponds?

What could a 5% deposit get you?

$800,000
$40,000 A 20% deposit would be $160,000

No LMI: an estimated $22,800 premium avoided (a broad guide; real premiums vary by lender and loan).

Stamp duty: $0 for eligible NSW first home buyers (saves $30,187).

Indicative only. The deposit excludes stamp duty, legal and inspection costs, and a participating lender, not this calculator, confirms 5% Deposit Scheme eligibility.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
I found Charles and Links Property Finance very prompt and professional to deal with. Made it all so easy.
Marg Google review
★★★★★
Paperwork and finances were never my strong suit. He has made this process as simple and dummy proof for me as humanly possible. This is not the first time I use a mortgage broker, however it was the easiest and most pleasant.
Mikhail Google review
★★★★★
Charles went above and beyond to help us secure our home loan. He worked hard to find the best option for us and kept us updated throughout the whole process. His knowledge of the lending market was impressive and he made everything straightforward.
Anthony Google review

Permanent residents buying in The Ponds

Permanent residents do not need foreign investment approval to buy a home, wherever they live. NSW surcharge purchaser duty is a separate test: it does not apply if you were in Australia for at least 200 days in the 12 months before the purchase, or if you move in and live in the home continuously for 200 days within 12 months.

Housing Australia’s guarantees, including the 5% Deposit Scheme, are open to permanent residents, provided every applicant on the loan is a citizen or permanent resident.

Most lenders treat permanent residents much like citizens, though a few restrict particular visa classes or want a minimum time in your current job. Home loans for permanent residents in detail

A weatherboard house with a white picket fence

Families and first buyers in The Ponds

A Sydney house with a red tiled roof
  • Links Property Finance is based in Enfield, and clients in The Ponds usually talk with Charles by phone or video, or in person when it suits.The first conversation is about your visa, your work and the home you want.
  • More than eight in ten homes in The Ponds are separate houses, and more than six in ten are owned with a mortgage.That is nearly twice the NSW share with a mortgage, which reflects how recently the suburb was built.

What do lenders check for permanent residents?

Keys in the lock of a front door
  • Your visa grant.Lenders confirm permanent residency, often with a VEVO check, and a few restrict certain visa classes.
  • Your time in your job.Most lenders want you past probation, and some accept overseas experience in the same field.

Second Ponds Creek, the estate and housing in The Ponds

The Ponds lies about forty kilometres north-west of the city by its official measure, in the City of Blacktown.

It was part of Kellyville and Kellyville Ridge until it was declared a separate suburb in January 2007, and its name reflects the local geography, coming from Second Ponds Creek.

The first lots of land were released in March 2007, and in 2012 the development won the Residential Development and Sustainable Development categories at the UDIA NSW awards.

  • The suburb has two public primary schools, John Palmer Public School, opened in 2008, and Riverbank Public School, opened in 2015, along with The Ponds High School and The Ponds School, a specialist school, which both opened in 2015.
  • When a permanent resident in The Ponds is buying, Links compares a panel that includes ING, Macquarie, Westpac, ANZ and Resimac.
Read the full detail

The suburb has two public primary schools, John Palmer Public School, opened in 2008, and Riverbank Public School, opened in 2015, along with The Ponds High School and The Ponds School, a specialist school, which both opened in 2015.

Separate houses make up most of the housing, townhouses and semis most of the rest, and apartments are almost absent.

When a permanent resident in The Ponds is buying, Links compares a panel that includes ING, Macquarie, Westpac, ANZ and Resimac.

Example scenario (illustrative, not a real client): a couple in The Ponds became permanent residents two years ago and have rented since arriving. One partner has been in a permanent role for eighteen months, and the other started a new job recently after years in the same field overseas.

They check that both are past probation, confirm they qualify for the 5% Deposit Scheme as permanent residents, and apply with a lender that accepts their visa subclass and work history.

What if you have recently been overseas?

Time overseas never brings in foreign investment approval for a permanent resident. It can bring in the NSW surcharge: under 200 days here in the past year, you are exempt only by moving in and living there continuously for 200 days.

Checking your status before you sign avoids a costly surprise at settlement. Home loans for permanent residents.

A blue-roofed house with a front path

A short credit history here

Credit history from another country does not usually carry across to Australian credit reporting, so new arrivals often have a thin file. Lenders then rely more on bank statements, rent payments and how you manage any local cards or loans.

Keeping limits low and repayments on time builds the record quickly. Credit score for a home loan.

One partner not yet a permanent resident

A couple where one partner holds a temporary visa can still borrow with some lenders, but the 5% Deposit Scheme requires every applicant to be a citizen or permanent resident.

Foreign investment and duty exemptions for spouses have conditions, so check them first. Home loans for temporary residents.

Citizen, permanent or temporary visa?

What each status means when you buy.

  • Citizen. No foreign investment approval or surcharge. All schemes open if you are eligible.
  • Permanent resident. Treated much like a citizen while living here. Schemes open when every applicant qualifies.
  • Temporary visa. Approval needed and the surcharge applies. New homes or land only until mid-2029.

What should I check before buying in The Ponds as a permanent resident?

What to have ready before you make an offer.

  • Your visa grantWith passport identification.
  • Recent payslipsPast probation where possible.
  • Bank statementsShowing savings and rent.
  • A scheme checkFor the 5% Deposit Scheme.
  • Days in AustraliaIf you have travelled recently.
  • Pre-approvalBefore an auction or offer.

Common questions about buying in The Ponds as a permanent resident

Can permanent residents buy in The Ponds without FIRB approval?

Yes. Holders of an Australian permanent visa do not need foreign investment approval to buy residential property, even after time overseas. Time away matters for NSW surcharge purchaser duty instead, so check that before you exchange.

Do permanent residents pay the NSW foreign buyer surcharge?

Not if they meet the same residence test. Revenue NSW has an online tool to check your status before you sign.

Can I use the 5% Deposit Scheme as a permanent resident?

Yes. Housing Australia’s guarantees are open to permanent residents, provided every applicant on the loan is a citizen or permanent resident and the other conditions are met.

Do lenders accept all permanent visa types?

Most do, but a few restrict certain visa classes. Your visa grant notice shows the subclass, which narrows the lender list quickly.

I have only just started my job. Can I still borrow?

Often, if the role is permanent and you have experience in the same field. Some lenders want you past probation, so timing the application can matter.

Does my overseas credit history count?

Usually not directly. Australian lenders use Australian credit reports, so they look more closely at bank statements and how you manage any local credit.

Talk to a broker about your The Ponds home loan

One free call covers what you could borrow in The Ponds, the lenders that suit the property you want and the order to do things in.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.