

Call Charles Book a meeting
Business lending

Links Property Finance · Investment property mortgage broker, Sydney: Office Property Loans in Sydney

An office purchase is commercial lending: lenders look at the building, the strata scheme, any lease in place and how long the space could sit empty between tenants.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

What do lenders look at when you buy an office?

Lenders look at the location and building quality, the lease and the tenant behind it, and vacancy; for an office your business will occupy, they read the business’s financial statements and tax returns instead.

Read more

A well-located strata suite with a solid tenant, or with your own business in it, still finances well.

Part of the investment property loans guide.

An empty room with a view, ready to move into

Recent Links clients

  • Three Links Property Finance clients in front of the agent’s board at the home they bought Family buy · South West Sydney
    Bought, and all smiles. A family purchase in Sydney’s south-west.
  • A family in front of the sold sign at the home they bought together Family buy · Inner West
    The whole family turned up. A parents’ guarantee, done properly.
  • Next one

    The next sold sign could be yours.

    A free 30-minute call shows where you stand.

    Book my free call

What would the property return?

Gross and net yield

Gross and net rental yield

Move the sliders to match the property. The yearly costs are everything you pay to own it, before the loan.

$950,000
$750
$9,000
  • Rent, per year$39,000/yr
  • Gross rental yield4.11%
  • Net rental yield3.16%

Compare the net yield with the interest rate on the loan: below it, the property costs you money each year, which is negative gearing.

Estimates only, before loan repayments and tax. Vacancy, rent changes and costs change the real return. Not financial or tax advice.
Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles and the team recently assisted me with the refinance of my investment property.
Max Google review
★★★★★
As a first home buyer, I was pretty overwhelmed at the start, but Charles made everything much easier. He explained the process step by step and helped me understand my borrowing options. His professionalism and responsiveness were excellent.
Ric Google review
★★★★★
A huge thank you to Charlie for his exceptional support and expertise throughout the process of securing finance for my first home.
Julian Google review

What do lenders look at on an office?

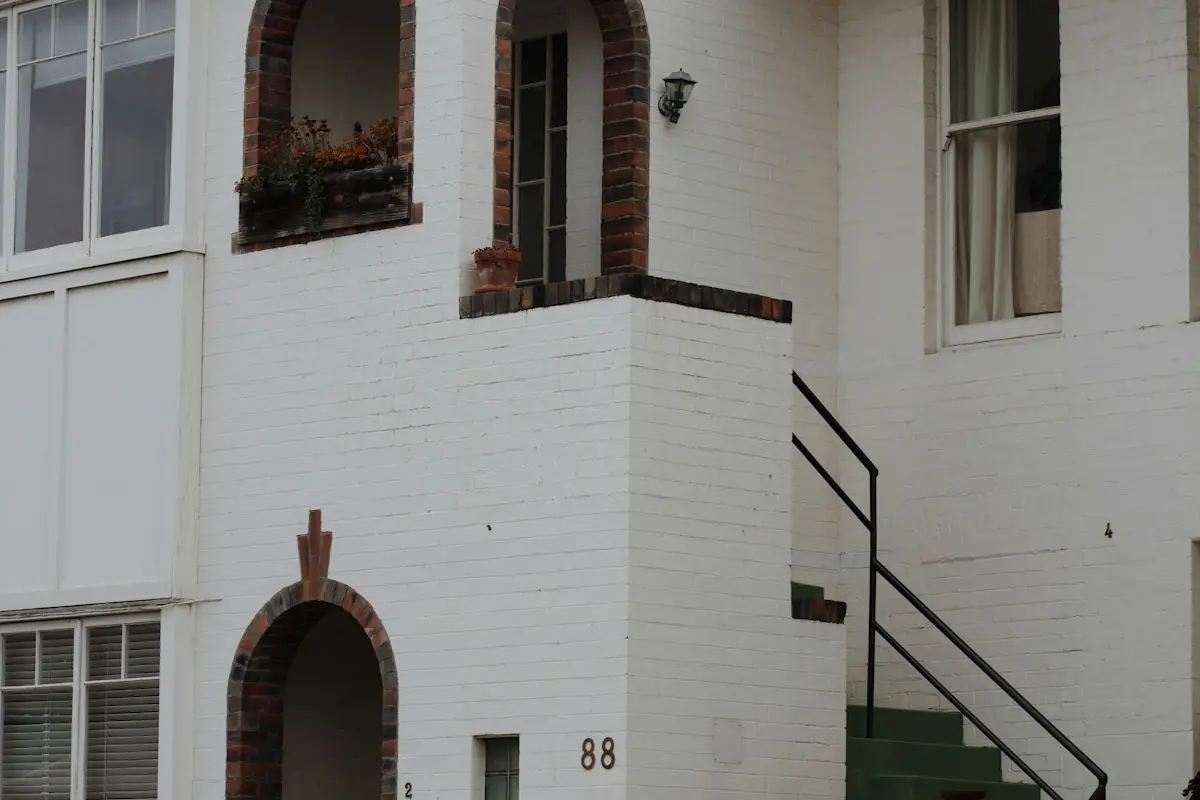
A white apartment block in Sydney
  • Location and building quality.Offices near transport and services in established centres are easier to lend against than space in a weak or oversupplied area.
  • The strata scheme.For a suite, the strata records, levies, building defects and any major works planned all matter.
  • Size and layout.Very small suites, or space only one kind of business could use, can mean a lower lending ratio.

How do lenders read the lease on an investment office?

Keys being handed over at a front door
  • Who the tenant is.An established business with a track record supports the loan better than a new one.
  • How long the lease runs.Lenders look at the remaining term and any options, and a lease ending soon carries vacancy risk.
  • Whether the rent covers the interest.Many lenders test the rent against the interest with a margin, known as interest cover.

Buying an office for your own business

When your business will occupy the office, the lender assesses the business’s financial statements and tax returns, and the repayments replace the rent you pay now.

Some owners buy through a trust, a company or a self-managed super fund and lease the space to the business, which needs advice from your accountant and a licensed financial adviser first.

Offices in mixed-use buildings

Many suburban offices sit above shops or in buildings with apartments. Lenders treat the office suite as commercial security even when the rest of the building is residential, and the mix of uses in the strata scheme can affect the valuation.

See mixed-use property loans.

Common questions about office property loans

How much deposit do I need to buy an office?

Usually more than for a home loan, because lenders lend a smaller share of the value against commercial property. The amount depends on the location, the building, any lease and your finances.

Is a strata office suite easier to finance than a whole building?

Often, because suites are smaller and appeal to more buyers and tenants. A whole building can still be financed well, but the loan is larger and the lender looks more closely at leasing and vacancy.

Will a lender count the rent from a tenanted office?

Yes. For an investment purchase the rent is central to the assessment. Lenders look at the lease terms and the tenant, and often test whether the rent covers the interest with a margin.

Can I buy an office through my super fund?

Generally yes: a self-managed super fund can buy business real property such as an office and lease it to a related business at market rent, using a limited recourse borrowing arrangement. The rules are strict, so get advice from your accountant and a licensed financial adviser first.

Is GST payable on an office purchase?

Often, unless the sale is a going concern with a lease continuing or the vendor is not registered for GST. The contract should say how GST is treated, and your accountant can confirm before you sign.

Looking at industrial space instead? See warehouse and industrial property loans.

Get advice on office property loans

Charles can check how lenders would treat the building and any lease, the deposit the purchase needs, and how the repayments compare with the rent you pay now.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · Commercial property loans · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit, tax or legal advice. Commercial lending policies, lending ratios and lease requirements for office property vary between lenders and change over time.