
Cross-Collateralisation vs Standalone Loans: What to Know
What cross-collateralisation is, why lenders like it, how it can trap you when you sell or refinance, and how to set up standalone loans instead.
 Charles Touma
3 min read
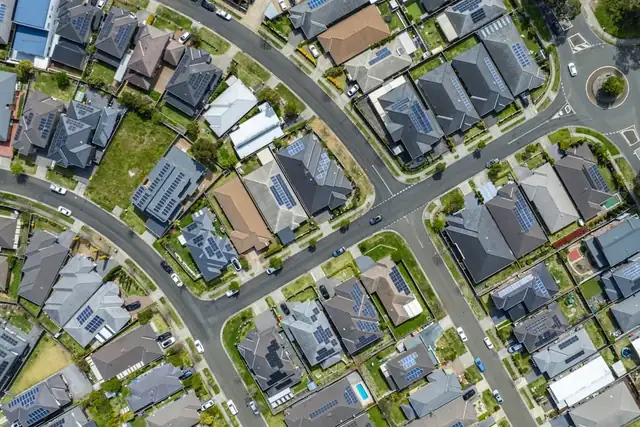
Cross-collateralisation is when one loan, or a group of loans, is secured by more than one property. Lenders like it because they hold all the security. It can help you buy without a cash deposit, but it ties the properties together: selling, refinancing or borrowing more on one means the lender revalues and controls both. Standalone loans keep each property separate.
| Item | Cross-collateralised | Standalone |
|---|---|---|
| Security | Both properties secure the loans | Each property secures its own loan |
| Selling one property | Lender decides how much of the sale must repay debt | Repay that property’s loan; keep the rest |
| Refinancing one loan | Usually need to move or restructure everything | Move one loan alone |
| Valuations | Both properties can be revalued | Only the one involved |
| Setting up | Simple, often the lender’s default | Needs a separate equity loan for the deposit |
How does cross-collateralisation happen?
Usually when you buy a second property with the same lender and use equity in the first as the deposit. The simplest set-up for the lender is to take a mortgage over both properties for the new loan. Many borrowers do not notice until they try to sell or refinance.
What can go wrong when you sell?
Take a real Links client file: a couple with a home worth $1,400,000 and $620,000 owing, buying a $650,000 investment using equity. Had both properties secured the loans, here is what a later sale of the investment would have meant. Because the lender holds both, it can revalue your home and decide how much of the sale proceeds must go to reducing debt to keep its overall LVR where it wants it. If values have fallen, it can keep more than you expected, and you lose control of the cash.
How do standalone loans work instead?
You borrow the deposit and costs as a separate split secured only by your home, then take the investment loan secured only by the investment property. For that couple, the structure proposed is a $165,000 split on the home that covers the $130,000 deposit and $35,000 in costs, and a $520,000 loan, 80% of the price, secured by the investment. The home then secures $785,000, about 56% of its value, and each property can be sold or refinanced on its own. The full file is on the real client cases page. Tax deductibility depends on the purpose of each split, which is easier to track this way; see split home loans.
Is cross-collateralisation ever useful?
Occasionally: when a lender needs the extra security to approve a deal, for some construction or development loans, or when the properties will be sold together. Even then, it is worth asking whether a standalone structure with a different lender would work.
How do you uncross loans you already have?
Usually by refinancing one or both loans so each is secured by one property, which needs fresh valuations and an assessment. The guide to refinancing an investment property covers the process, and using equity to buy explains the standalone set-up for your next purchase.
Questions people ask
What does cross-collateralisation mean?
That a loan is secured by more than one property, so the lender can rely on all of them.
Is cross-collateralisation bad?
Not always, but it reduces your control when you sell or refinance. Standalone loans are usually the better default.
Can I use equity without cross-collateralising?
Yes: borrow the deposit as a separate split against your home, and secure the new loan on the new property alone. The home equity calculator shows how much you can release.
Charles Touma sets up investment purchases with standalone loans as the default, so each property can be sold or refinanced on its own. A free 30-minute call covers your current structure and how to unwind it if needed. General information only, not credit advice; lender policies change, and your own circumstances decide what suits you.
Sources: Moneysmart, home loans; ATO, interest expenses on rental property, checked 20 October 2026.
General information only, not credit, legal or tax advice. Your situation is assessed properly before any recommendation. Government scheme details change; figures are current at the time of writing.
Keep reading
Refinancing an Investment Property or Interest-Only Loan
How to refinance an investment property: how lenders count rent, what happens when interest-only ends, tax on cash out and the 2027 gearing change.
Using Equity to Buy
Second Home and Holiday Home Loans: How Lenders Assess Them
Talk it through with Charles
A free 30-minute call: your borrowing power, deposit options and the next step.