




Quick repayment estimate
If things change
Principal and interest, constant rate, monthly repayments. An estimate only, not credit advice or an offer.
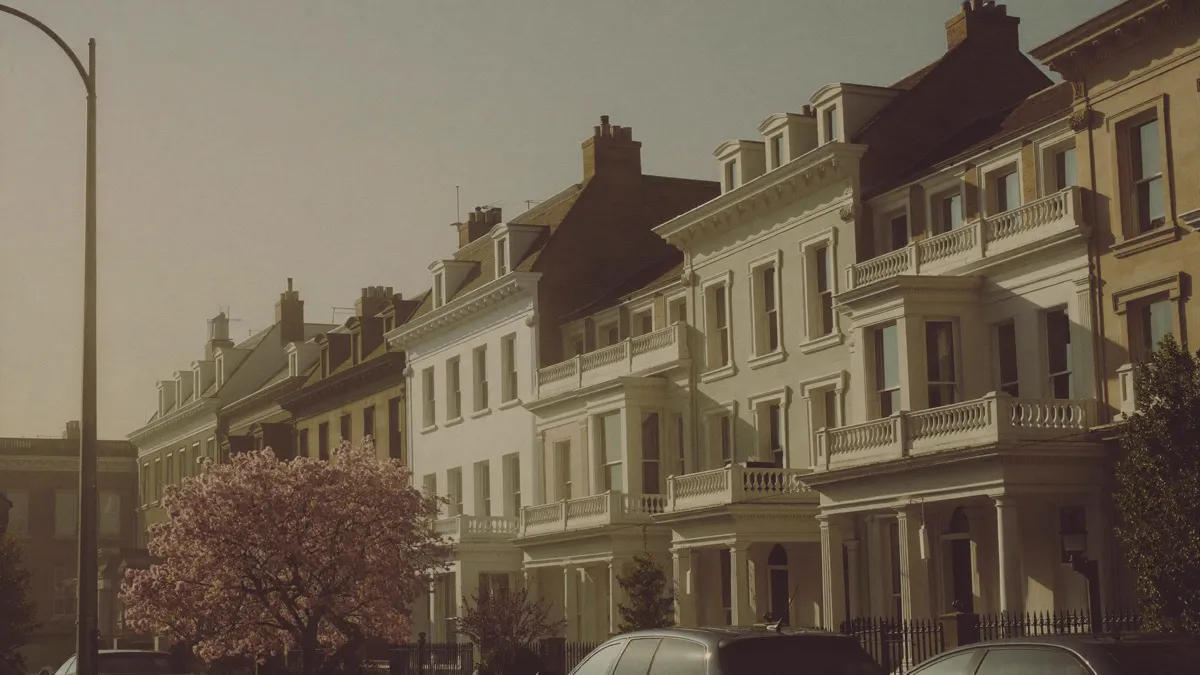
Nearly half of Annandale’s homes are semis, terraces or townhouses, about four times the NSW share, and an auction leaves no room for a finance clause.
A valuation in line with recent terrace sales, and a pre-approval that will hold on auction day, because the contract is unconditional when the hammer falls. Lenders also look at condition, parking and shared walls.
With no cooling-off at auction, the deposit and the finance have to be settled before you bid.

Attached homes are a big part of Annandale, at 47.2% against 11.7% statewide. Shared walls and older building fabric are where a building report earns its fee.
Separate housesTownhouses and semisApartments
apartments NSW 21.7%
separate houses NSW 65.6%
terraces and semis NSW 11.7%
rented NSW 32.6%
with a mortgage NSW 32.5%
private dwellings
Source: ABS Census 2021, Suburbs and Localities (SAL10062).

Quick repayment estimate
If things change
Principal and interest, constant rate, monthly repayments. An estimate only, not credit advice or an offer.
Confirm your numbers.
Charles Touma from Links Property Finance was a great help with buying my first home. I had plenty of questions and he took the time to explain things clearly without making me feel rushed. He kept me updated throughout and made the process much less stressful. Really appreciated his patience and would happily recommend him to other first home buyers.
Charles at Links Property Finance made buying our first home so much easier than we expected. As first home buyers, we had a lot of questions around borrowing capacity, our deposit and the different government schemes available to us. Charles explained everything clearly, compared different lenders and kept us updated throughout the whole process. He was always easy to reach and made sure we understood what was happening from pre approval right through to getting our home loan approved. We would definitely recommend Links Property Finance to anyone looking for a mortgage broker, especially first home buyers who want someone to guide them through the process.
I honestly couldn’t recommend Links Property Finance and Charles highly enough. After speaking with others who weren’t able to help me, Charles went above and beyond to understand my situation…
At an auction in New South Wales there is no cooling-off period, and the contract is unconditional once it is signed. The deposit, usually ten per cent unless the vendor agrees otherwise, is due on the day. If your finance is not approved afterwards, you are still bound to settle.
That is why the work happens before auction day: a pre-approval with a lender whose policy suits the property type, a bidding limit set from your borrowing power rather than the price guide, and a plan for the deposit, whether cash, a deposit bond or equity. Check your buying position


Annandale runs south from Rozelle Bay on Sydney Harbour, with Glebe to the east, Leichhardt and Lilyfield to the west, and Stanmore and Camperdown to the south. Johnstons Creek marks its eastern edge and Whites Creek its western one.
Johnston Street is the main road through the suburb and carries many of its older civic buildings, including the former Annandale Council Chambers, built in 1899.
A pre-approval, sometimes called conditional approval, is the lender’s assessment of you: income, expenses, debts and deposit. It generally does not cover a specific property, which is assessed once you have a contract. At auction you sign that contract before the second step has happened.
Two things narrow the gap. Choose a lender whose policy suits terraces, older buildings and smaller lots, and check how long the pre-approval lasts, refreshing it if your circumstances change. An expired or outdated pre-approval gives little comfort on the day. Pre-approval in detail.

The deposit is paid when the contract is signed, usually straight after the auction. That money has to be accessible: savings, an offset account or funds released from equity in another property.
If the deposit is tied up in a term deposit or a sale that has not settled, a deposit bond may be an option, though it costs a fee and has conditions of its own.
Your limit should come from what you can borrow and afford, not from the price guide. Start with your borrowing power, add your deposit, then take off stamp duty, conveyancing and moving costs.
What remains is the most you can pay without stretching the loan beyond what was assessed.
Know that figure precisely before the day, and consider having someone bid for you if auctions make you anxious. Coming home without the property is a better outcome than winning with a loan that does not fit. Check your borrowing power.

Stage one. Your budget. What you can borrow, what deposit you have and what costs to allow for. No documents are needed for this part.
Yes, many buyers do, but it is not a guarantee. A pre-approval assesses you rather than the particular property, and the lender still values the terrace after the auction.
No. A property bought at auction in New South Wales has no cooling-off period, and once the contract is signed you are committed to settle.
The usual deposit is ten per cent of the price, paid when the contract is signed. A smaller deposit is sometimes possible if the vendor agrees, but that must be arranged before the auction.
The lender lends against the lower of the price and its valuation. If the valuation is lower, you cover the difference yourself, either with more deposit or by accepting a higher loan-to-value ratio, which may bring lenders mortgage insurance.
Some lenders can, if you apply early enough, though not all do and it can take a few days. It shows whether the price you expect to pay is likely to be supported.
Bring your Annandale plans to a free 30-minute call: your borrowing range, the lenders that fit the property and your next step.
Prefer a callback?
Charles calls back within one business day. No documents needed yet.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.






