


Offset savings
Interest saved$168,306and roughly 3y 10m off the loan
Assumes the offset balance stays steady and repayments stay the same. Estimates only.

Bexley is the St George area's house market: established brick homes on blocks large enough to matter, bought by families who intend to stay.
Family money comes in as a documented gift, a guarantee or shared ownership, each changing whose income and names are on the loan.
The block matters too: a large Bexley block can carry a granny flat or extension later, which lenders value with approvals and a contract in place.

Terraces, semis and townhouses make up 25.5% of homes in Bexley, about twice the NSW share. Shared walls and older building fabric are where a building report earns its fee.
Separate housesTownhouses and semisApartments
apartments NSW 21.7%
separate houses NSW 65.6%
terraces and semis NSW 11.7%
rented NSW 32.6%
with a mortgage NSW 32.5%
private dwellings
Source: ABS Census 2021, Suburbs and Localities (SAL10333).

Offset savings
Assumes the offset balance stays steady and repayments stay the same. Estimates only.
Confirm your numbers.
Paperwork and finances were never my strong suit. He has made this process as simple and dummy proof for me as humanly possible. This is not the first time I use a mortgage broker, however it was the easiest and most pleasant.
Charles and the team recently assisted us with a refinance of our investment property. Recommend Charles and the team to all
I have had a number of dealings with Charles from Links Property Finance. He is very knowledgeable, thorough, and detailed with his advice. Importantly, he is very approachable and easy to deal with. His advice has been beneficial to myself and my acquaintances. I highly recommend him.
 Charles Touma, Mortgage Broker.

Bexley has no railway station of its own. Stations in the neighbouring suburbs ring it instead: Rockdale to the east, Kogarah to the south-east, Carlton to the south and Bexley North to the north.
The streets closest to those stations draw commuters, while the rest of the suburb relies on buses and the car. That shows up at valuation, where the walk to a station is one of the differences a valuer weighs between comparable sales.
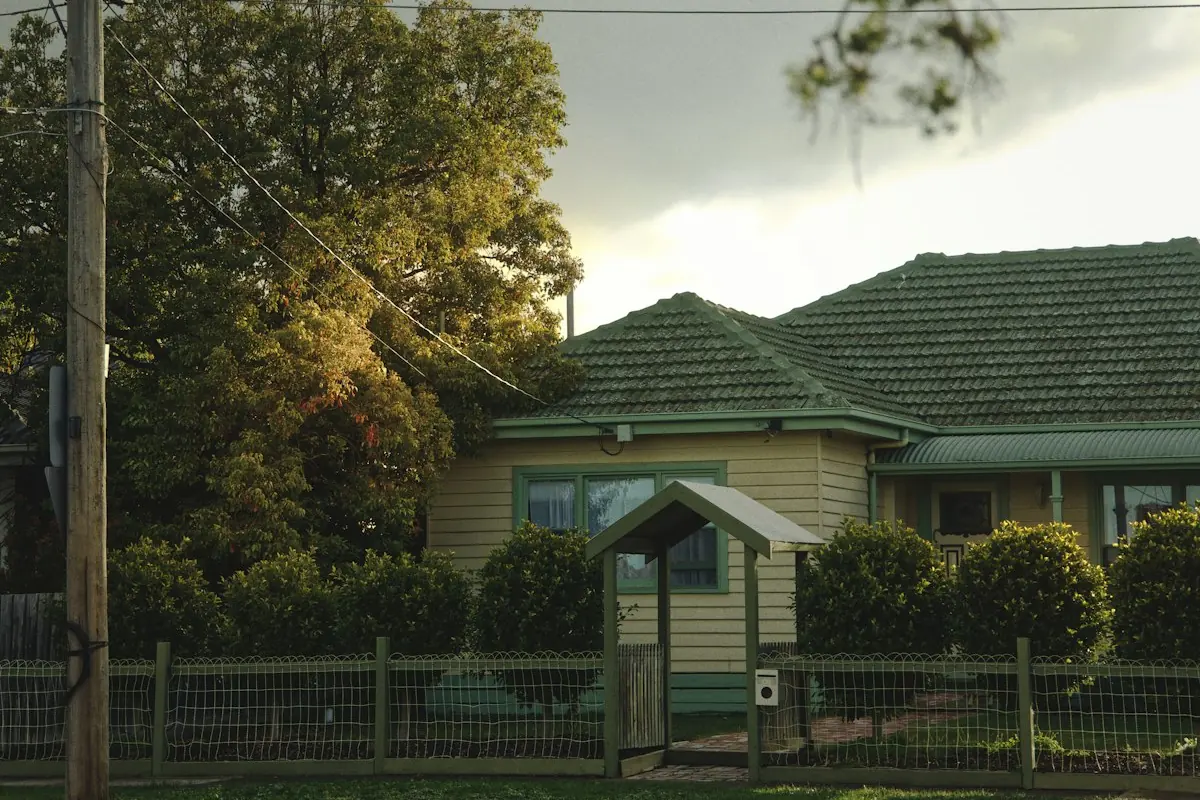
The stock is mainly established houses, from Federation and other period cottages on streets such as Gladstone Street and Harrow Road to later brick homes, with semis, townhouses and a smaller share of unit blocks around them.
A house on its own title keeps the security simple. The questions come from the block and the building: whether a granny flat or duplex is realistic, whether past additions were approved, and what the building report says about an older home.
Bexley files are compared across lenders such as ANZ, Westpac, Macquarie, ING and Resimac for rules that suit the household and the block.
Example scenario (illustrative, not a real client): a couple renting in Rockdale want a Federation cottage in Bexley, with a parent contributing part of the deposit and a granny flat in mind for later.
The gift has to be documented to the chosen lender’s standard, and the cottage has an enclosed rear verandah with no approval on record.
Lenders differ on gifted funds and on how a valuer’s note about unapproved work affects the loan, so weighing policy up front points to a lender that suits the cottage now and the granny flat later.

What tends to decide a Bexley purchase.
Savings, documented gifts and where rules apply savings history, built to the specific lender's requirements. The checklist.
Established houses carry findings. They become a price adjustment or a first-year budget, and skipping the report to compete is a poor trade.
Where the deposit gap is the obstacle, family equity can close it without cash moving, usually removing mortgage insurance. With a planned exit.
Granny flat or, where zoning allows, a duplex. Worth pricing at purchase rather than discovering later.
A freestanding first home is still reachable here with the supports applied.
It is one of the St George pockets where that remains realistic, particularly with family support. The 5% scheme's cap reaches the housing stock and part of the market falls under the duty exemption, which is what makes the deposit maths close where it would not further north.
It can play a part. A valuer compares your house with recent sales of similar homes nearby, and walking distance to a station is one of the differences they weigh. It rarely decides a Bexley valuation on its own, though.
Land size, condition and any unapproved additions usually matter more. Where comparable sales are thin, two valuations of the same house can differ, which is worth planning for before an unconditional purchase.
Often, on these block sizes. A granny flat houses family or earns rent, and at many lenders an approved secondary dwelling’s rent counts towards serviceability; funding usually runs through an equity release with staged builder payments.
The negotiation and the first-year budget. Established brick homes carry findings, which is normal. The mistake is skipping the report to compete on a busy Saturday, because the lender's valuer will notice what you chose not to look at.
Where zoning allows it, yes, and it is a construction finance question rather than an ordinary purchase: the lender assesses the completed pair's end value and funds the build in stages, with contingency expected.
Your exit, keep both or sell one, shapes the structure and should be decided before the application.
Different markets entirely. Bexley buys land, space and optionality at a higher price point; Hurstville buys density, amenity and a lower entry price with building-level lending questions attached. Which suits depends on your household rather than on which is better.
Thirty minutes with Charles: what you could borrow, which lenders suit Bexley property and what to do next. Free, with no credit check.
Prefer a callback?Charles calls back within one business day. No documents needed yet.


General information only, not credit or financial advice. Property types and lender policies differ and change over time; your position is confirmed in a full assessment. Links Property Finance works across Sydney and Australia-wide.
Official sources for the figures on this page: Housing Australia, 5% Deposit Scheme · Revenue NSW, First Home Buyers Assistance Scheme. Scheme rules change; the official pages are the final word. Checked against these sources on 12 October 2026.


