


Call Charles Book a meeting
Mortgage Broker Newington

Links Property Finance · Home loans in Newington and across Sydney: Mortgage Broker in Newington

Newington’s homes are a mix of houses, semis and apartments, and about four in ten are owned with a mortgage, well above the NSW figure.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Fixed, variable or split in Newington: which loan suits your plans?

Fix if certain repayments matter most; stay variable for an offset, unlimited extra repayments or a planned sale; split for some of each.

Read more

Fixed loans can carry break costs if you leave early, so the choice rests on your plans for the next few years, not on a rate forecast.

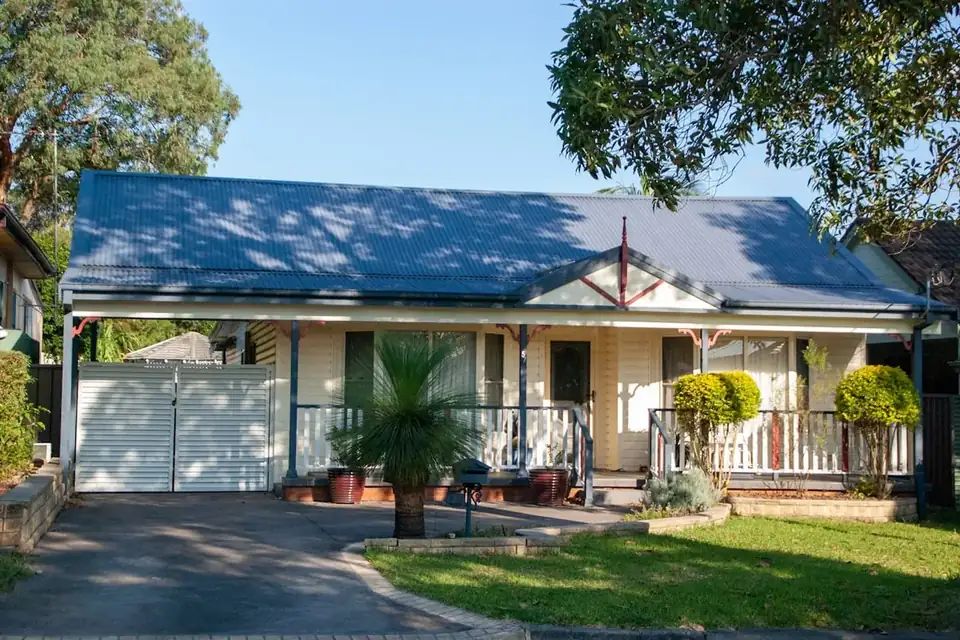
A blue-roofed house with a front path
In Newington, houses make up 38.9% of homes, terraces and semis 17.1% and apartments 43.9% (ABS Census 2021).

How a lender reads an address in Newington

With 43.9% of dwellings in apartment buildings, strata is a big part of buying in Newington. Here the building is assessed almost as closely as the borrower, from the strata report to the size of the complex. Mortgaged homes are 40.9% of the stock, well above the state figure. Plenty of those owners are now upgrading, refinancing or helping the next generation in.

  • Postcode2127
  • CouncilCity of Parramatta
  • From the Sydney CBD18 km west
43.9%

apartments NSW 21.7%

38.9%

separate houses NSW 65.6%

17.1%

terraces and semis NSW 11.7%

31.5%

rented NSW 32.6%

40.9%

with a mortgage NSW 32.5%

2,065

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL12962).

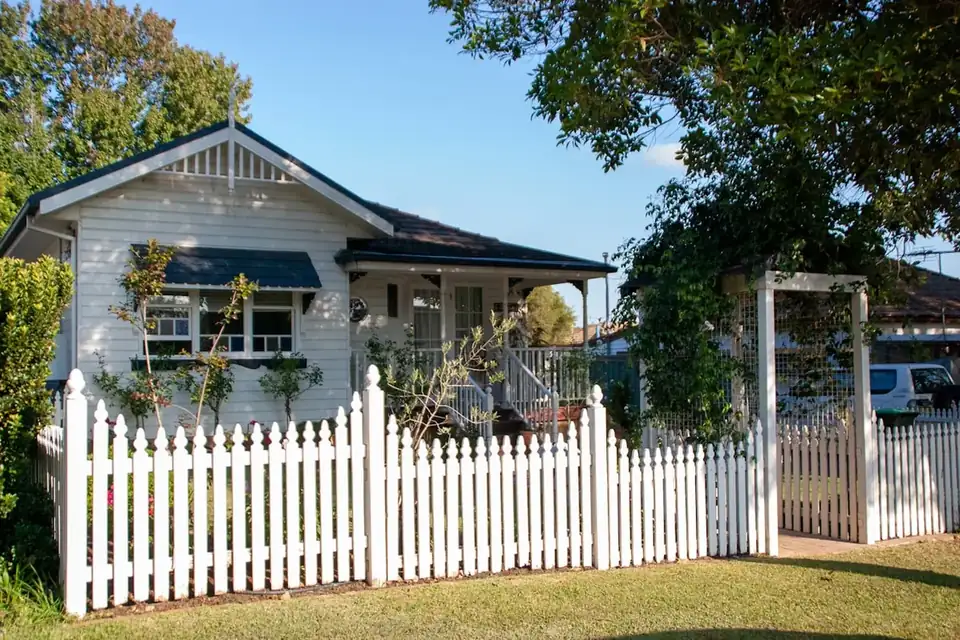
A Federation-era house with a tiled roof and front garden

Refinancing a Newington home loan: the saving

Calculate your savings

$550,000
6.40%
25
6.00%

Example rates only, not current advertised rates. Set both sliders to your own figures.

Interest at 6.40%Interest at 6.00%
You could save$40,706≈ $1,628 a year in repayments
Current repayments$3,679/month
New repayments$3,544/month

Over the remaining term, before switching costs and fees, we model those before recommending a move. Estimates only, not credit advice.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
I have had a number of dealings with Charles from Links Property Finance. He is very knowledgeable, thorough, and detailed with his advice. Importantly, he is very approachable and easy to deal with. His advice has been beneficial to myself and my acquaintances. I highly recommend him.
Joseph Google review
★★★★★
Highly recommend Charles! Professional, knowledgeable and very easy to work with. He helped us navigate the home loan process and found a great solution that suited our needs. Excellent service from start to finish.
Daniel Google review
★★★★★
Paperwork and finances were never my strong suit. He has made this process as simple and dummy proof for me as humanly possible. This is not the first time I use a mortgage broker, however it was the easiest and most pleasant.
Mikhail Google review

Fixed, variable or split in Newington

A fixed rate stays the same for a set period, which makes repayments predictable. In exchange, fixed loans usually limit extra repayments, often lack a full offset, and can carry break costs if you repay or change the loan early.

A variable rate moves with the market, and usually allows extra repayments, redraw and an offset.

A split loan divides the balance, with part fixed and part variable. It gives some certainty while keeping flexibility on the variable part.

Nobody can reliably predict where rates will go, so the choice is best made on how much certainty and flexibility you need. Fixed or variable in detail

Terrace houses along a tree-lined street

Owners and families in Newington

A family on the porch of their home
  • Links Property Finance is based in Enfield, about fifteen minutes from Newington, with conversations by phone, video or in person.The first one is about your budget, your plans and how you use your savings.
  • About four in ten Newington homes are owned with a mortgage, against about a third across New South Wales.Many owners here are mid-loan, weighing up rate choices.

What does each rate type trade?

A first home buyer working through their numbers at the kitchen table
  • Fixed gives certainty.The same repayments for the fixed period, with limits on extra repayments.
  • Variable gives flexibility.Extra repayments, redraw and offset, with repayments that can move.

The Athletes village, the river and Newington housing

Newington lies about sixteen kilometres west of the city in the City of Parramatta, on the Parramatta River, about a kilometre north-west of Sydney Olympic Park.

It is best known as the site of the Athletes Village for the 2000 Summer Olympics and Paralympics, which was converted into a residential suburb after the Games, with more apartments and houses built since.

Newington Marketplace, an outdoor shopping centre, is at its heart, and a reserve opposite carries a memorial listing the Australian team at the 2000 Games.

  • The name comes from the Newington Estate, named by John Blaxland after his family estate in Kent.
  • When a Newington owner is choosing a rate type, Links compares a panel that includes Westpac, Macquarie, ING, ANZ and Resimac.
Read the full detail

The name comes from the Newington Estate, named by John Blaxland after his family estate in Kent. Blaxland acquired more than five hundred hectares here in 1807 and established salt pans along the Parramatta River.

Later, part of the estate became an asylum for aged women. Today the suburb’s homes are a mix of houses, semis and apartments.

When a Newington owner is choosing a rate type, Links compares a panel that includes Westpac, Macquarie, ING, ANZ and Resimac.

Example scenario (illustrative, not a real client): a Newington couple are refinancing and want certainty on repayments while their children are young, but also make regular extra repayments.

They choose a split loan, fixing part of the balance for a few years and keeping the rest variable with an offset account for savings and extra repayments.


Break costs on fixed loans

If you repay a fixed loan early, refinance or sell during the fixed period, the lender may charge a break cost. It depends on how rates have moved since you fixed, and can be significant.

If you might sell or refinance within the fixed period, that is worth weighing before you fix. Managing your home loan.

A red-roofed house on a quiet street

How does a split loan work?

A split loan divides the balance into separate portions, one fixed and one variable. You choose the proportions, and each portion follows its own rules.

The variable part can carry the offset and extra repayments, while the fixed part gives predictable repayments. Offset accounts explained.

When does the fixed period end?

At the end of a fixed period, the loan usually moves to the lender’s standard variable rate, which may not be its sharpest. Lenders often contact you beforehand, but it is worth reviewing your options a couple of months ahead.

You can fix again, go variable or refinance. When your fixed rate ends.

Fixed, variable or split?

Three ways to set up the rate, and what each means.

  • Fixed. Predictable repayments for the fixed period. Limited extra repayments, and possible break costs.
  • Variable. Moves with the market. Usually allows extra repayments, redraw and offset.
  • Split. Part fixed, part variable. Certainty with some flexibility.

What should I check before choosing a rate type?

The questions that point to the right structure.

  • How long you will staySelling during a fixed period can cost.
  • Extra repaymentsHow much you plan to pay extra.
  • Your savingsWhether an offset would help.
  • Your budgetHow much repayment certainty you need.
  • Fixed rate end datesDiary them if you fix.
  • Break costsUnderstood before you commit.

Common questions about fixed and variable loans in Newington

Should I fix my home loan?

It depends on how much certainty you need and how much flexibility you use. Fixing gives predictable repayments, while variable usually allows extra repayments and an offset. Nobody can reliably predict rates.

What is a split loan?

A loan divided into portions, with one fixed and one variable. It combines some certainty with some flexibility.

Can I make extra repayments on a fixed loan?

Most fixed loans allow only a modest amount extra each year before fees apply. That is one reason Newington owners who plan to pay extra often keep part of the loan variable.

Do fixed loans have an offset account?

Usually not a full one: some fixed loans offer a partial offset or none at all, while variable loans more commonly have a full offset.

What are break costs?

Fees that may apply if you repay or change a fixed loan early. They depend on how rates have moved since you fixed and can be significant.

What happens when my fixed rate ends?

The loan usually moves to the lender’s standard variable rate. Reviewing your options a couple of months before the end date is worthwhile.

Talk to a broker about your Newington home loan

One free call covers what you could borrow in Newington, the lenders that suit the property you want and the order to do things in.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.