


Call Charles Book a meeting
Mortgage Broker Oran Park

Links Property Finance · Home loans in Oran Park and across Sydney: Mortgage Broker in Oran Park

Oran Park is a master-planned town built in stages, where nearly every purchase is a house-and-land package.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

What does an Oran Park purchase take to finance?

A construction loan, sequenced around registration. The land settles when the estate registers, then the build is paid in stages as each one is inspected.

Read more

Pre-approval often lapses before registration, so the lender is chosen for how it refreshes approvals, and the 5% Deposit Scheme can apply within its caps.

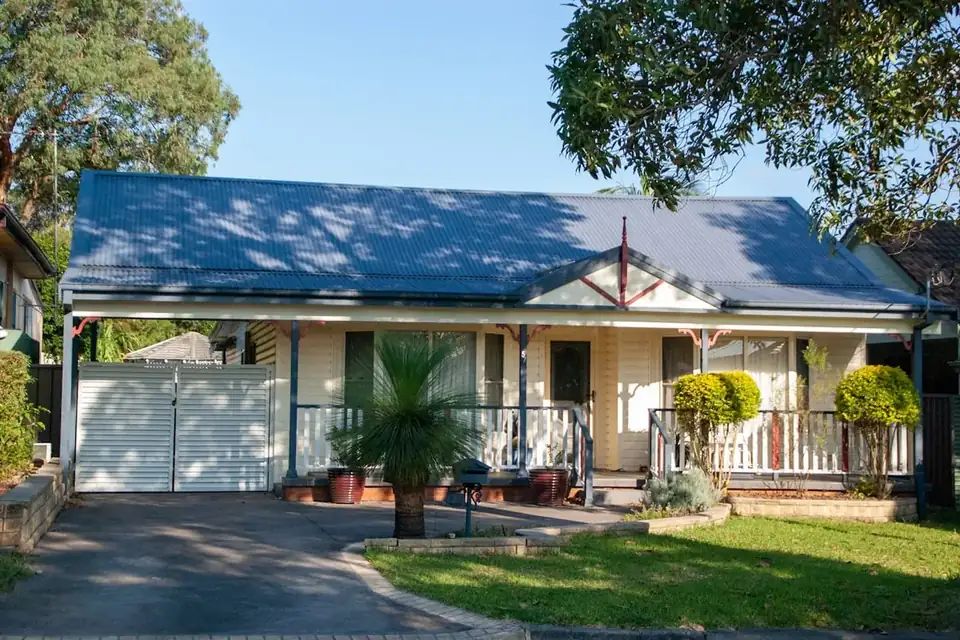
A blue-roofed house with a front path
In Oran Park, houses make up 86.9% of homes, terraces and semis 11.7% and apartments 1.1% (ABS Census 2021).

The housing mix in Oran Park

Just under nine in ten homes in Oran Park are separate houses on their own block. Owners here often build equity faster than they expect, which opens a top-up, a renovation or help for family later. Just over half of the homes are owned with a mortgage, above the 32.5% across NSW. Many of those loans were priced years ago, and a rate review is often the quickest saving available.

  • Postcode2570
  • CouncilCamden Council
  • From the Sydney CBD59 km south west
1.1%

apartments NSW 21.7%

86.9%

separate houses NSW 65.6%

11.7%

terraces and semis NSW 11.7%

35.5%

rented NSW 32.6%

53.6%

with a mortgage NSW 32.5%

5,612

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL13102).

Terrace houses along a tree-lined street

Can I get a better rate on an Oran Park home loan?

Calculate your savings

$550,000
6.40%
25
6.00%

Example rates only, not current advertised rates. Set both sliders to your own figures.

Interest at 6.40%Interest at 6.00%
You could save$40,706≈ $1,628 a year in repayments
Current repayments$3,679/month
New repayments$3,544/month

Over the remaining term, before switching costs and fees, we model those before recommending a move. Estimates only, not credit advice.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
I have had a number of dealings with Charles from Links Property Finance. He is very knowledgeable, thorough, and detailed with his advice. Importantly, he is very approachable and easy to deal with. His advice has been beneficial to myself and my acquaintances. I highly recommend him.
Joseph Google review
★★★★★
Had a great experience with Charles at Links Property Finance. He made the whole home loan process straightforward and easy to understand, kept me updated throughout and was always quick to answer any questions.
Louie Google review
★★★★★
Highly recommend Charles! Professional, knowledgeable and very easy to work with. He helped us navigate the home loan process and found a great solution that suited our needs. Excellent service from start to finish.
Daniel Google review

Helping buyers and builders in Oran Park

A family on the porch of their home
  • Links Property Finance works across the south west by phone, video and in person when it helps.Oran Park files are package files almost by definition: land contracts awaiting registration, fixed-price builds awaiting land, and completed near-new homes trading with builder warranties still current, the simplest door for buyers who'd rather skip the wait.
  • The town's planning does real work, town centre, schools, sport, but the finance disciplines are the frontier's: timing, contingency and approvals kept current while dates move.

The package, in the right order

A family together in their backyard
  • The sound sequence starts before any contract: borrowing verified across land plus build plus contingency, the registration estimate treated as an estimate, and the build contract's price-review clauses read by your solicitor while the finance is structured to absorb them.
  • Then it runs itself: land settles on registration, five build stages draw down after inspections, interest accrues only on released funds, and completion converts to standard repayments.The construction guide walks every step.

Oran Park town, from the old raceway to new release stages

Oran Park Town is built on the site of the former Oran Park Raceway, beside The Northern Road, with many of its streets named after motor racing figures and the Oran Park Podium shopping centre at its heart.

There is no railway station in the suburb. Buses connect the town with Leppington and Campbelltown stations, and The Northern Road is the main road link north and south.

  • The housing is almost all recent: house-and-land packages in the current release stages, and established and near-new homes in the earlier ones.
  • Links sets ANZ, Westpac, Macquarie, ING, Resimac and other lenders side by side, because construction terms and progress payment handling differ from one lender to the next.
Read the full detail

The housing is almost all recent: house-and-land packages in the current release stages, and established and near-new homes in the earlier ones. For a lender, a package means a land contract that settles on registration, a build contract drawn down in stages and a valuation on the finished home.

Earlier stages give valuers streets of established resale evidence. Newer stages lean more on the fixed-price build contract and recent land sales. A near-new house with its builder warranty still running is assessed like any established home, with a single settlement.

Links sets ANZ, Westpac, Macquarie, ING, Resimac and other lenders side by side, because construction terms and progress payment handling differ from one lender to the next.

Example scenario (illustrative, not a real client): A young couple from Narellan sign for a block in a new Oran Park release, with a fixed-price build contract to follow once the land registers.

Registration is only an estimate, their pre-approval may lapse before it happens, and they plan to use the 5% Deposit Scheme. Comparing lenders on construction policy and on how each handles a long wait for registration shows which one can carry the land and the build as a single plan, and when the application will need refreshing.


A row of red-brick terraces

Oran Park, financed

The four decisions that shape every package file here.

Read the full detail

First home buyers in Oran Park

New-build supports were made for this town.

  • The 5% Deposit SchemePackages qualify under the $1.5 million cap, five per cent across land and build, no lender's insurance, timing sequenced. Check eligibility.
  • First Home Owner Grant$10,000 on eligible new builds within the grant’s value caps, which some packages exceed, stacked where criteria align.
  • Duty on land, not houseBuying land then building can mean duty on the land price alone, a structural saving worth understanding early. Run the comparison.
  • Help to Buy, liveShared equity from 2% inside its caps, fitted to corridor pricing. Settings verified against your file.

Common questions about building in Oran Park

What's the real all-in cost of a package here?

Land plus build plus site costs plus selections plus contingency plus duty and legals, several of which the display-suite price doesn't headline. The accurate number gets assembled before contracts, with the duty saving from land-then-build counted and the contingency held rather than hoped. We build that figure with you first.

How do lenders value a home in an early Oran Park release compared with a new one?

Earlier stages have streets of completed homes that have already resold, so a valuer has direct evidence to work from. A new release has less of that, and the valuation leans on recent land sales, the fixed-price build contract and sales of similar new homes nearby.

Either can finance well. The difference is how much buffer to hold in case the valuation on completion lands below the combined land and build price.

The land registers 'mid next year'. How do I plan finance around that?

As a window, not a date: approvals structured to be refreshed, your position kept deliberately stable through the wait, and headroom held so a policy or rate shift between now and registration doesn't strand the file. Slippage is normal here; being hurt by it is optional.

Progress payments, how do they work?

The lender releases funds at completed stages, slab, frame, lockup, fit-off, completion, each after inspection, and you pay interest only on what's been drawn. It keeps the build in check, the costs staged, and the pressure manageable. Variations draw from contingency, which is why it lives inside the approved facility.

Package build or a near-new completed home?

The build gets you selection control, the grant where eligible and land-then-build duty treatment, at timeline risk. Near-new gets immediate settlement, warranty remainder and known streets, at a completed-home price. Both are legitimate Oran Park doors; the comparison is numeric and personal, we run the numeric half properly.

Can we use the 5% scheme on a house-and-land package?

Commonly yes: new builds qualify under the cap, with the scheme place sequenced against land registration and build completion, administration that has to be right rather than difficult. Stacked with the grant and the duty treatment, Oran Park first files carry some of the strongest support loads in Sydney.

Talk to a broker about your Oran Park home loan

One free call covers what you could borrow in Oran Park, the lenders that suit the property you want and the order to do things in.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.