Quick repayment estimate
If things change
Principal and interest, constant rate, monthly repayments. An estimate only, not credit advice or an offer.
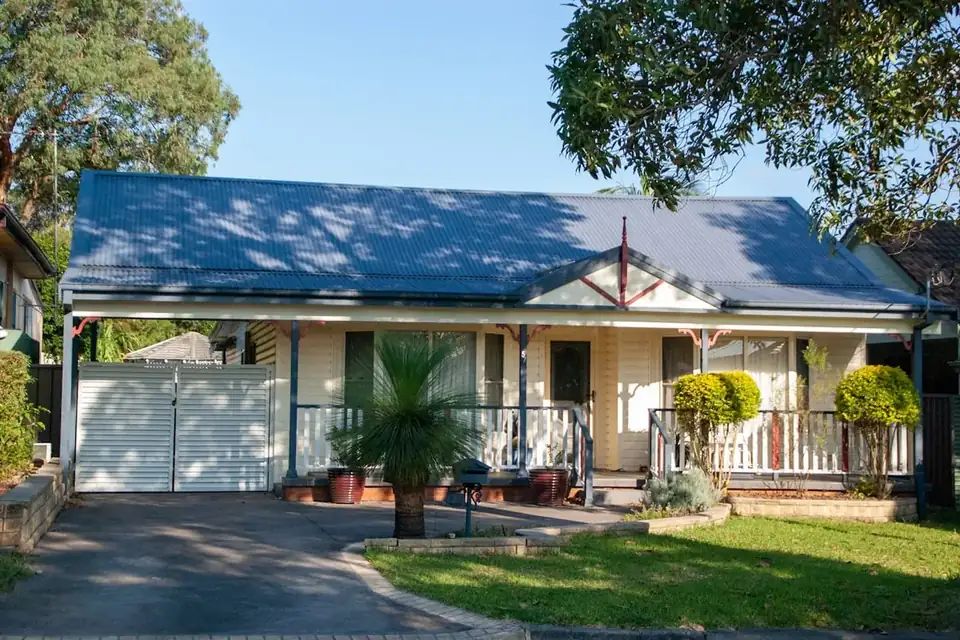
Cabarita’s park, wharf and quiet waterside streets hold period homes that families keep for decades, and renovate rather than leave.
Smaller work from savings, an offset or redraw; larger work from a loan top-up valued on the finished home or a construction loan paid in stages.
Lenders want plans, quotes and approvals first, and an extension on a waterfront period home is valued on recent sales nearby.

Apartments are four in ten homes here (41.0%, against 21.7% statewide). Small studios and older blocks with thin sinking funds narrow the lender list, which is worth knowing before you bid. Cabarita is an owner-occupier suburb: just 18.2% of homes are rented.
Long tenures mean plenty of equity in the street, which is often what funds the next purchase or a family guarantee. With only 790 dwellings, Cabarita sees few sales in any year, and valuers sometimes reach into neighbouring suburbs for evidence.
Separate housesTownhouses and semisApartments
apartments NSW 21.7%
separate houses NSW 65.6%
terraces and semis NSW 11.7%
rented NSW 32.6%
with a mortgage NSW 32.5%
private dwellings
Source: ABS Census 2021, Suburbs and Localities (SAL10734).

Quick repayment estimate
If things change
Principal and interest, constant rate, monthly repayments. An estimate only, not credit advice or an offer.
Confirm your numbers.
Charles and the team at links property finance recently assisted me with my purchase of my first property in Burwood. As a first home buyer, Charles made the process simple and easy. I would recommend Charles to all first home buyers
As a first home buyer, I was pretty overwhelmed at the start, but Charles made everything much easier. He explained the process step by step and helped me understand my borrowing options. His professionalism and responsiveness were excellent.
Charles went above and beyond to help us secure our home loan. He worked hard to find the best option for us and kept us updated throughout the whole process. His knowledge of the lending market was impressive and he made everything straightforward.
Bring the Cabarita plan, the purchase, the build, the switch, and leave with the lending mapped: which lenders fit, what it costs monthly and what to do first. Free, no obligation.
Prefer a callback?
Charles calls back within one business day. No documents needed yet.


Cabarita has no railway station, but it does have Cabarita ferry wharf in Cabarita Park, served by Parramatta River ferries running between Circular Quay and Parramatta. Both are a short walk from the waterfront complexes and the older house streets.
For a lender, the wharf and park show up in value rather than policy. A house near the water with few recent comparable sales can be valued conservatively, especially where an extension is planned, while units in the larger complexes usually have recent sales in the same building to compare.
The housing splits almost evenly between houses and apartments, with some semis and townhouses between. Waterfront communities such as Cape Cabarita and Edgewood include shared recreational facilities, so for a home inside one of them the strata or community scheme records, and the levies that fund those facilities, belong in the assessment.
The houses are the renovation file this page describes: equity release for smaller works, construction lending for extensions, and character or heritage controls to confirm before plans are drawn.
Valuation and construction policy both vary, so a Cabarita extension or apartment is compared across lenders such as ANZ, Westpac, Macquarie, ING and Resimac before one is chosen.
Example scenario (illustrative, not a real client): a family who bought a period house a few streets from Cabarita Park now want a rear extension and a second storey. Their builder has quoted a fixed-price contract with staged payments, and there are few recent sales of comparable houses nearby.
Lenders differ on as-if-complete valuations and on how progress payments are drawn, so comparing construction policy before signing shows which lender’s process fits the builder’s schedule and a conservative end value.


The mechanics, in the order the project meets them.
Lenders lend against current value, typically to 80% without insurance. The question isn’t only how much you can release, it’s how much the project needs with a contingency, so you’re not returning mid-build for a top-up assessed at a worse moment. Estimate the available equity.
Fixed-price contract, staged invoices, an “as if complete” valuation: once those appear, the facility should be built for them. Progress draws matched to the builder’s schedule keep the site moving; a mismatch is the classic stalled-extension story.
For big projects, lenders weigh the completed value. Near the water that judgement can be conservative, improvements cap out against street norms in a valuer’s eyes, even when buyers would pay. Structure around the conservative case and let the upside be a bonus.
Parts of the area carry character controls that shape what can be built and how long approvals take. Finance should follow the approval pathway, not race ahead of it, an approved plan borrows better than an ambition.
Purchases here are typically larger-loan territory with thin comparables, the waterfront valuation dynamics covered on our Drummoyne page apply with the same force. Pre-approval, a checked contract and a bid ceiling before auction; the suburb rewards prepared buyers because there are so few second chances.
Long-held Cabarita homes often fund children’s first deposits, as documented gifts or through family guarantees where equity stands behind a child’s loan without cash moving. Both routes work; both deserve the paperwork done properly. Guarantees, both sides explained.
It depends on the paperwork: if the work runs on quotes you pay as they come, an equity release gives simple flexibility; if a builder works to a fixed-price contract with progress payments, a construction loan funds the stages.
If there’s a fixed-price contract with staged invoices, typical for extensions and second storeys, a construction facility matches money to milestones and usually keeps the lender happier at the sizes involved. The wrong structure works too; it just works with friction.
Not as a separate line item. A valuer works from recent sales of similar homes, and because Cabarita is small and turnover is low, house sales near the park and wharf can be few and far between.
That is why house valuations here can land conservatively, particularly for an extension. Apartments in the larger waterfront complexes usually have more recent comparable sales, which tends to make their valuations more predictable.
Yes, for construction facilities: lenders use an “as if complete” valuation, the current property plus contracted works. It is a professional judgement that near the water often lands conservative, so plan the borrowing against the valuation you might get, not the one you deserve.
Typically up to 80% of current value minus what you owe, without lenders mortgage insurance, subject to servicing the larger loan on your income. The calculator gives the arithmetic; the application tests the income side. Run your numbers.
Not directly, lenders don’t price heritage. Indirectly, controls lengthen approvals and constrain designs, which shapes contract timing and the completed value. The sane sequence is approval first, finance structured to the approved scope, then contract. Finance leading design is how budgets get rebuilt twice.
Usually, with structure. A guarantee uses equity without moving cash but sits on your title until released; a documented gift moves cash but keeps your property unencumbered.
Which suits depends on your renovation plans, since both interact with how much of your equity stays deployable. Worth mapping together rather than deciding piecemeal.
General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.