





Call Charles Book a meeting
Mortgage Broker Clemton Park

Links Property Finance · Home loans in Clemton Park and across Sydney: Mortgage Broker in Clemton Park

Clemton Park is a small suburb of fewer than six hundred homes, three in four of them separate houses, and about a third still carry a mortgage.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Folding car loans and cards into your Clemton Park mortgage: does it save money?

Usually each month, because the debts move to the mortgage rate. It can cost more in total if a five-year car loan is stretched over thirty years.

Read more

Putting the consolidated debts in a separate split and repaying it over a short term keeps the saving real.

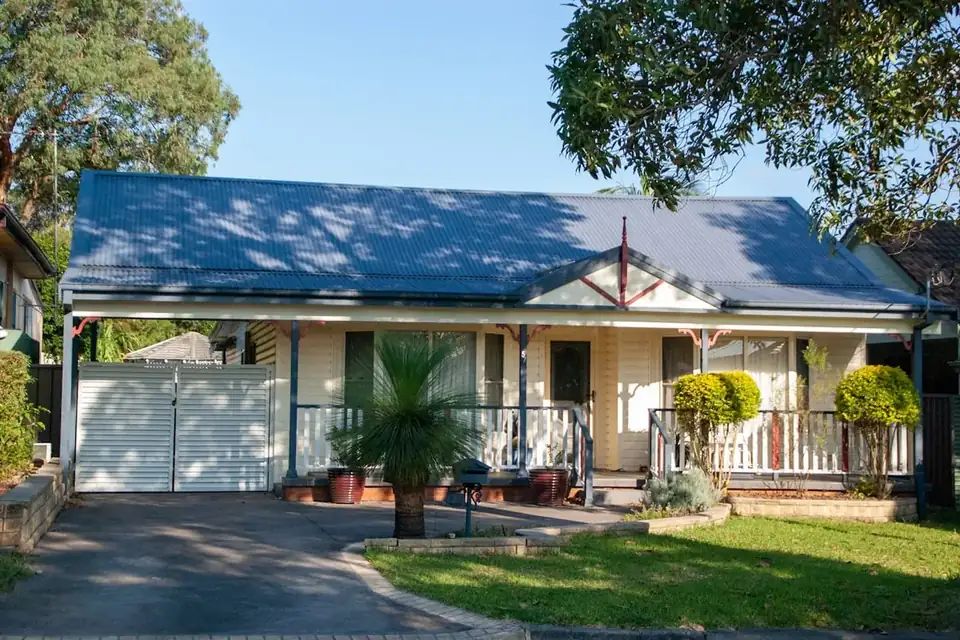
A house with a wide front verandah
In Clemton Park, houses make up 76.9% of homes, terraces and semis 18.0% and apartments 3.8% (ABS Census 2021).

Clemton Park’s housing, in numbers

Clemton Park is mostly detached homes, 76.9% of everything built here. A house on its own title is the simplest security a lender takes, and the land carries most of the value. With only 580 dwellings, Clemton Park sees few sales in any year, and valuers sometimes reach into neighbouring suburbs for evidence.

  • Postcode2206
  • CouncilCity of Canterbury-Bankstown
  • From the Sydney CBD13 km south west
3.8%

apartments NSW 21.7%

76.9%

separate houses NSW 65.6%

18.0%

terraces and semis NSW 11.7%

25.8%

rented NSW 32.6%

34.1%

with a mortgage NSW 32.5%

580

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL10927).

A terrace with an iron-lace balcony

Refinancing a Clemton Park home loan: the saving

Calculate your savings

$550,000
6.40%
25
6.00%

Example rates only, not current advertised rates. Set both sliders to your own figures.

Interest at 6.40%Interest at 6.00%
You could save$40,706≈ $1,628 a year in repayments
Current repayments$3,679/month
New repayments$3,544/month

Over the remaining term, before switching costs and fees, we model those before recommending a move. Estimates only, not credit advice.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Had a really good experience with Charles at Links Property Finance. He was easy to deal with, always quick to respond and kept everything simple and clear throughout the whole process. You can tell he genuinely cares about getting the best outcome for his clients rather than just getting things done quickly. Really happy with the experience and would happily recommend Charles and Links Property Finance to anyone.
Christian Google review
★★★★★
Paperwork and finances were never my strong suit. He has made this process as simple and dummy proof for me as humanly possible. This is not the first time I use a mortgage broker, however it was the easiest and most pleasant.
Mikhail Google review
★★★★★
Had a great experience with Charles at Links Property Finance. He made the whole home loan process straightforward and easy to understand, kept me updated throughout and was always quick to answer any questions.
Louie Google review

Consolidating debts in Clemton Park

Rolling a car loan, credit cards or a personal loan into your home loan usually lowers the interest rate on that debt and reduces the total monthly repayment.

What it does not do on its own is make the debt cheaper overall, because a few years of car loan spread over a twenty or thirty year mortgage can cost more in total interest.

It works best with a plan to repay the consolidated amount quickly, through extra repayments or a separate split, and with the cards closed afterwards so the balance does not build up again.

The lender will want to see the old debts paid out at settlement. Debt consolidation in detail

A blue-roofed house with a front path

Owners and equity in Clemton Park

A Sydney house with a picket fence
  • Links Property Finance is based in Enfield, a short drive north of Clemton Park.Conversations run by phone and video, and the first one is about what you owe, what it costs and what you want to change.
  • Three in four Clemton Park homes are separate houses, and more than a third are owned outright.Owners here often have equity to work with, which is what makes consolidation possible in the first place.

What does a lender check when you consolidate?

A family together in their backyard
  • That the new loan is affordable on your income.Consolidation lowers your total repayments, but the lender still assesses the larger home loan against your income and expenses.
  • That the old debts will close.Lenders usually pay the debts out directly at settlement and may ask for credit cards to be closed or their limits reduced.

Cup and Saucer Creek, Yatama Park and Clemton Park houses

Clemton Park lies about thirteen kilometres south-west of the city in the City of Canterbury-Bankstown. It is roughly bounded by Cup and Saucer Creek, Bexley Road, William Street and Kingsgrove Road, though most properties facing those roads belong to Earlwood, Kingsgrove or Campsie.

Clemton Park Public School and the small group of shops at Bexley Road and William Street are just over the border in Earlwood, and within the suburb itself is Yatama Park.


The true cost of consolidating

Compare two numbers, not one. The monthly repayment usually falls after consolidation, but the total interest over the life of the loan can rise if the old debts are stretched over decades.

The fair comparison is what each option costs in total, over the time you intend to take to repay it.

A red-roofed house on a quiet street

Credit cards, limits and borrowing power

Lenders count credit card limits, not balances, when working out what you can afford.

An unused card with a large limit reduces your borrowing power just as a used one does, so closing cards or reducing limits as part of a consolidation can make the application stronger.

Buy now pay later accounts and personal loans also appear on your credit file and in the assessment. Listing every debt, with its balance, limit and repayment, is the first step. Check your borrowing power.

Missed payments and your options

If some payments have been missed, consolidation is still sometimes possible, but the choice of lender narrows and conditions tighten. What matters is the pattern, the reason and how recent it is. A short, explained period of difficulty is treated differently from repeated defaults.

Some specialist lenders consider borrowers with recent credit problems, usually at a higher rate for a period. The right move depends on your full position, and sometimes the better first step is to steady repayments before applying. Borrowing with credit problems.

From first conversation to one loan

Stage one. Your debts. Every loan and card, with balances, limits and repayments. No documents are needed for this part.

  • Stage two. The comparison. The current total cost against a consolidated loan, over the time you plan to take to repay it.
  • Stage three. The application. Income evidence, statements for each debt and the home loan go in together, with the valuation ordered by the lender.
  • Stage four. Settlement. The lender pays out the old debts directly, and the cards are closed or their limits reduced. Book a call or call 0423 952 184.
A row of red-brick terraces

Common questions about consolidating debt in Clemton Park

Will consolidating my debts save me money?

It can, but not automatically. The interest rate on the old debts usually falls, and so does the monthly repayment. If the debts are then repaid over the full mortgage term, the total interest can be higher than before.

Can I consolidate a car loan into my mortgage?

Usually, yes, if there is enough equity and the lender is satisfied with your income. The car loan is paid out at settlement.

Do lenders count my credit card limit or balance?

Most count the limit. A card with a large limit reduces your borrowing power even if it is paid off each month. Closing unused cards or reducing limits before or during a consolidation can make a noticeable difference.

Can I consolidate debts if I have missed payments?

Sometimes. It depends on how recent and how serious the missed payments are, and why they happened. Mainstream lenders may still help after a short, explained period of difficulty, while specialist lenders consider more complex histories, usually at a higher rate.

Will consolidating affect my credit score?

A little at first, then usually for the better: the new application appears on your credit file and closing accounts changes it, but fewer debts and on-time repayments generally help over time.

Talk to a broker about your Clemton Park home loan

One free call covers what you could borrow in Clemton Park, the lenders that suit the property you want and the order to do things in.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.




