Call Charles Book a meeting
Mortgage Broker Lilyfield

Links Property Finance · Home loans in Lilyfield and across Sydney: Mortgage Broker in Lilyfield

Half of Lilyfield’s homes are separate houses, many of them former workers’ cottages, and a third carry a mortgage.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Buying a Lilyfield cottage that needs work: how is the renovation funded?

In stages. The purchase is valued as the cottage stands today, so the deposit is based on that. Lenders want the costings before they lend against the improvement.

Read more

Cosmetic work can come from savings or a redraw; structural work usually needs plans, quotes and either a loan top-up valued on the finished home or a construction loan.

A terrace with an iron-lace balcony
In Lilyfield, houses make up 49.9% of homes, terraces and semis 22.8% and apartments 27.0% (ABS Census 2021).

Lilyfield by its homes

Terraces and semis are a familiar sight in Lilyfield, at 22.8% of the housing. Heritage controls on some streets limit what can be changed, which matters if the plan is to renovate with the loan.

  • Postcode2040
  • CouncilInner West Council
  • From the Sydney CBD6 km west
27.0%

apartments NSW 21.7%

49.9%

separate houses NSW 65.6%

22.8%

terraces and semis NSW 11.7%

36.1%

rented NSW 32.6%

34.3%

with a mortgage NSW 32.5%

3,328

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL12334).

A brick bungalow with a tidy front lawn

How much equity could you use in Lilyfield?

Home equity calculator

Home equity calculator

For upgraders and investors, how much of your home could work as a deposit.

$1,100,000
$600,000
  • Total equity$500,000
  • Usable equity (to 80% LVR)$280,000

That usable equity could work as a deposit on an investment property or renovation, structured so your properties aren’t tied together unnecessarily.

Usable equity assumes lending to 80% of your home’s value against your current loan. Lender policy and serviceability decide the real figure.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles and the team at links property finance recently assisted me with my purchase of my first property in Burwood. As a first home buyer, Charles made the process simple and easy. I would recommend Charles to all first home buyers
Elijah Google review
★★★★★
Paperwork and finances were never my strong suit. He has made this process as simple and dummy proof for me as humanly possible. This is not the first time I use a mortgage broker, however it was the easiest and most pleasant.
Mikhail Google review
★★★★★
I honestly couldn’t recommend Links Property Finance and Charles highly enough. After speaking with others who weren’t able to help me, Charles went above and beyond to understand my situation…
Evangelos Google review

Buying a renovator in Lilyfield

When you buy a property that needs work, the lender values it as it stands today, not as it could be.

Visible problems, such as a failing roof, damp or structural movement, can lower the valuation and occasionally make a lender cautious about the property as security. A building report before you commit tells you what you are taking on.

Funding the renovation is a second question. Smaller jobs can be paid from savings, an offset account or a later top-up.

Larger work usually needs a construction loan, which relies on approved plans and a fixed-price contract and releases money in stages as the work is done. Renovation lending in detail

A red-roofed house on a quiet street

Cottages and renovations in Lilyfield

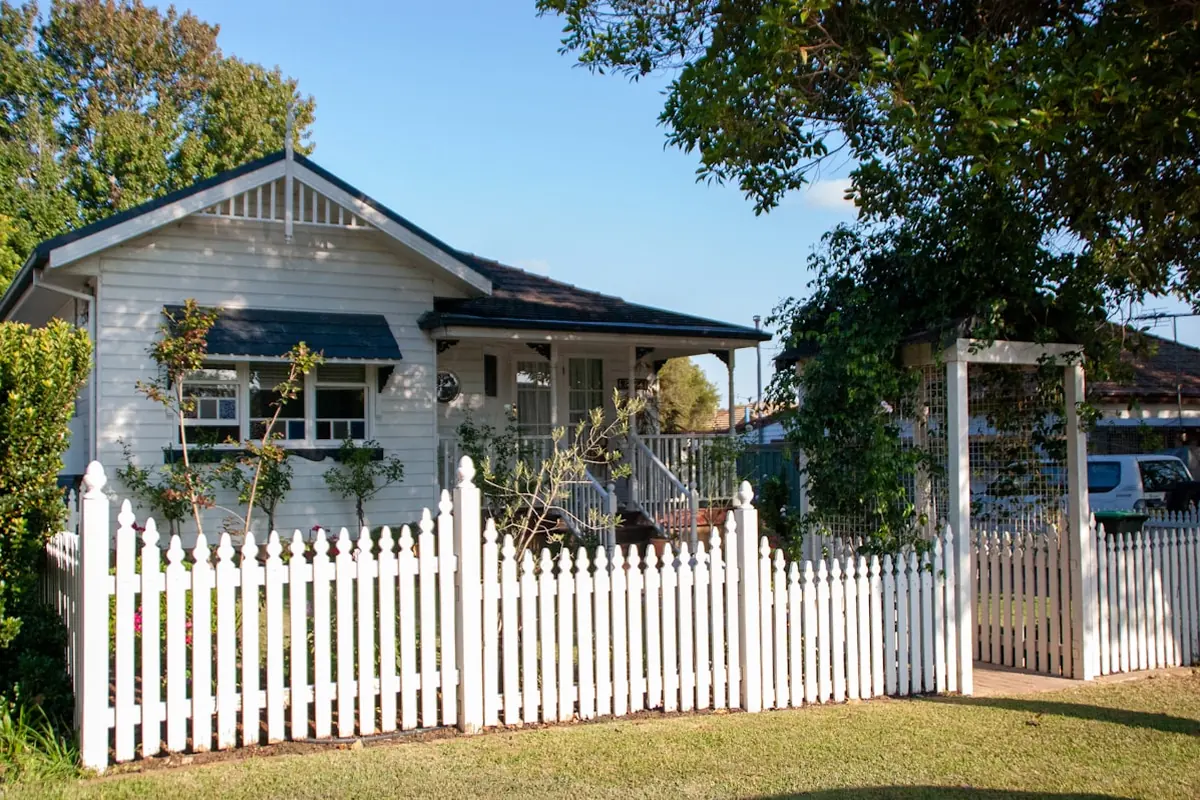
A corner cottage in Sydney
  • Links Property Finance is based in Enfield, with conversations by phone and video.The first one is about the property, the work it needs and how you want to pay for it.
  • Half of Lilyfield’s homes are separate houses, against about two in three across New South Wales.Many are older cottages on small lots, which is why condition and building reports come up so often in valuations here.

As is, and as if complete

A Federation-style house in Sydney
  • The purchase is valued as is.The loan to buy is based on the property in its current condition, whatever you plan to do next.
  • A construction loan is valued as if complete.For larger work, the lender estimates the value once the renovation is finished and sizes the construction funding against that.

Callan Park, the light rail and Lilyfield housing

Lilyfield lies about six kilometres west of the city in Inner West Council, with Iron Cove to the west and Annandale, Rozelle and Leichhardt around it. Leichhardt Park, with its aquatic centre, sits on the Iron Cove foreshore.

The Lilyfield light rail stop on Catherine Street opened in 2000 on a former goods line, and was the end of the line until the extension to Dulwich Hill in 2014.

Top-up, redraw or construction loan?

For modest work with a clear price, drawing on savings, an offset balance or redraw is the simplest route. A top-up, which increases your loan against the current value of the home, suits jobs that fit within your existing equity.

For a larger renovation, a construction loan is designed for the job: funds are released in stages against the builder’s invoices, and the loan can be based on the home’s value once the work is finished. It needs more paperwork, including approved plans and a fixed-price contract. Construction loan documents.

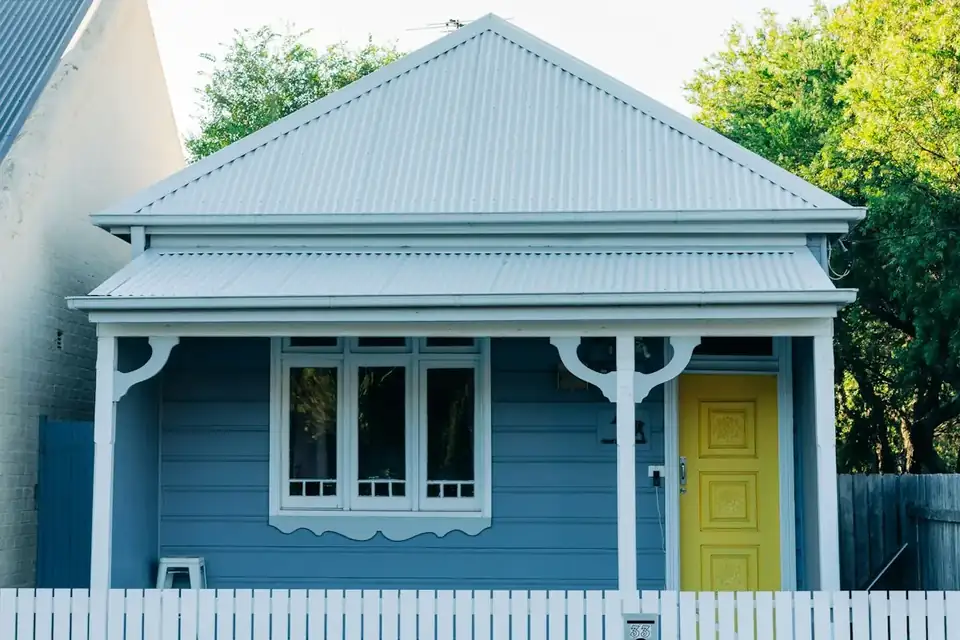
A blue weatherboard cottage

What can a building report change?

A building and pest report shows the condition of the structure, roof, plumbing and any termite activity. On an older cottage it often finds work you had not budgeted for, and occasionally something serious enough to change the price or your decision.

Getting the report before you commit gives you a negotiating position, and a realistic renovation budget from the start. Questions to ask before you offer.

Owner-builders and trades

Many lenders prefer a licensed builder on a fixed-price contract for construction lending. Owner-builder projects, where you manage the work yourself, are assessed more cautiously, and fewer lenders fund them.

If you plan to do some work yourself, it may be simpler to fund that part from savings and use a builder for the structural work the lender will fund. A renovation with a buffer.

From first conversation to the finished renovation

Stage one. The property and the plan. What you want to buy, the work it needs and your budget for both. No documents are needed for this part.

  • Stage two. The purchase loan. Pre-approval, and a loan based on the property’s value as it stands today.
  • Stage three. The renovation funding. A top-up or a construction loan, depending on the size of the work, with approvals and a contract in place.
  • Stage four. The build. Funds released as work is completed, and a revaluation once it is finished if you want to use the new equity. Book a call or call 0423 952 184.
A house with a wide front verandah

Cosmetic, structural or rebuild?

Three scales of Lilyfield renovation, and what each means for the loan.

  • Cosmetic. Paint, flooring, a kitchen or bathroom, often paid from savings or a top-up. Usually no council approval, and no change to how the loan is set up.
  • Structural. Extensions, new rooms or roof changes, usually needing approval and a builder. Commonly funded with a construction loan released in stages.
  • Rebuild. Knocking down or substantially rebuilding an older cottage. A construction loan based on the finished value, with more planning and approvals.

What should I check before buying a renovator in Lilyfield?

The groundwork for buying the property and funding the work.

  • A building reportBefore you commit, so the budget reflects the real condition.
  • A renovation budgetRealistic quotes rather than guesses, plus a contingency.
  • The approval pathWhether the work needs council approval or complying development.
  • Heritage controlsCheck the planning certificate for any conservation area.
  • Money for early workSavings or an offset balance for anything done before a construction loan.
  • A licensed builderMost lenders fund work by a licensed builder on a fixed-price contract.

Common questions about renovating in Lilyfield

Will a lender finance a house that needs a lot of work?

Usually, if the property is sound enough to be acceptable security. The loan is based on its value in its current condition, and serious structural problems can lower the valuation or make some lenders cautious. A building report before you commit tells you where you stand.

Can I include the renovation cost in my purchase loan?

Not usually at the start, because the purchase is valued as it stands. Smaller work can be funded later with a top-up once you own the home. Larger work is typically funded with a construction loan once you have approved plans and a fixed-price contract.

What is the difference between a top-up and a construction loan?

A top-up increases your loan against the home’s current value and releases the money in one amount. A construction loan releases funds in stages as work is completed, and can be based on the value once the renovation is finished, which suits larger projects.

Do I need council approval before the lender releases renovation funds?

For structural work, yes, lenders generally want the required approvals in place. Cosmetic work usually does not need approval. Heritage controls can affect what is allowed and how long approvals take.

Can I do some of the work myself?

You can, but lenders are more cautious about owner-builder work and fewer will fund it. A common approach is to pay for the work you do yourself from savings and use a licensed builder for the structural work the lender funds.

Will renovating increase my equity?

It can, but not always by as much as it costs. Once the work is finished, a revaluation shows the new value, and any increase can be used for other purposes if you choose. Planning the work with resale value in mind helps.

Talk to a broker about your Lilyfield home loan

One free call covers what you could borrow in Lilyfield, the lenders that suit the property you want and the order to do things in.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.