
Call Charles Book a meeting
Mortgage Broker Kogarah

Links Property Finance · Home loans in Kogarah and across Sydney: Mortgage Broker in Kogarah

Kogarah is built around a hospital, so many buyers earn rostered income, penalties and overtime.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Hospital shift income in Kogarah: which lenders count it in full?

Some lenders count regular shift penalties and overtime at close to full value after a few months; others take a two-year average or discount it heavily.

Read more

On a hospital payslip that difference can change borrowing power by tens of thousands, so the lender is chosen for how it reads your income before you apply.

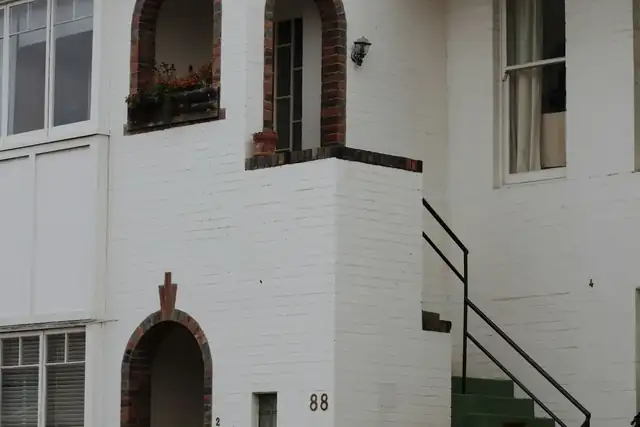
A white apartment block in the sun
Kogarah housing mix: 20.9% houses, 6.9% terraces and semis, 71.2% apartments (ABS Census 2021).

Kogarah by its homes

Units account for 71.2% of homes in Kogarah, nearly three times the state figure. That brings the levies, the sinking fund and any defect history into how a lender reads the building. 48.4% of homes here are rented, against 32.6% across NSW. High rental demand here helps an investment loan, because lenders count part of the expected rent toward servicing.

  • Postcode2217
  • CouncilGeorges River Council
  • From the Sydney CBD14 km south west
71.2%

apartments NSW 21.7%

20.9%

separate houses NSW 65.6%

6.9%

terraces and semis NSW 11.7%

48.4%

rented NSW 32.6%

26.8%

with a mortgage NSW 32.5%

7,232

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL12190).

Terrace houses along a tree-lined street

Buying in Kogarah with a 5% deposit

What could a 5% deposit get you?

$800,000
$40,000 A 20% deposit would be $160,000

No LMI: an estimated $22,800 premium avoided (a broad guide; real premiums vary by lender and loan).

Stamp duty: $0 for eligible NSW first home buyers (saves $30,187).

Indicative only. The deposit excludes stamp duty, legal and inspection costs, and a participating lender, not this calculator, confirms 5% Deposit Scheme eligibility.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles at Links Property Finance made buying our first home so much easier than we expected. As first home buyers, we had a lot of questions around borrowing capacity, our deposit and the different government schemes available to us. Charles explained everything clearly, compared different lenders and kept us updated throughout the whole process. He was always easy to reach and made sure we understood what was happening from pre approval right through to getting our home loan approved. We would definitely recommend Links Property Finance to anyone looking for a mortgage broker, especially first home buyers who want someone to guide them through the process.
Michael Google review
★★★★★
Had a great experience with Charles at Links Property Finance. He made the whole home loan process straightforward and easy to understand, kept me updated throughout and was always quick to answer any questions.
Louie Google review
★★★★★
I have had a number of dealings with Charles from Links Property Finance. He is very knowledgeable, thorough, and detailed with his advice. Importantly, he is very approachable and easy to deal with. His advice has been beneficial to myself and my acquaintances. I highly recommend him.
Joseph Google review

Helping the precinct's workforce buy in Kogarah

A Sydney house with a blue roof
  • Links Property Finance works across the St George area by phone, video and in person when it helps.Kogarah files frequently carry an advantage their owners have never been told about: healthcare professionals appear on professional lending lists at some lenders, and rostered income is treated far more generously at others than at the bank the borrower already uses.
  • Beyond the precinct, Kogarah is a conventional St George market: apartments near the station, established houses behind them, and prices where the first home buyer schemes still apply.

Rostered income, counted properly

A family together in their backyard
  • Base salary is the easy part.Penalties, overtime and allowances are where lenders diverge: a common treatment is a percentage of a two-year average, but the percentage varies widely, some lenders count rostered award penalties at full value where the employment is permanent, and evidence requirements differ.
  • For a nurse, midwife, paramedic or registrar whose variable income is a third of the total, that spread routinely changes the borrowing figure by six figures.The overtime guide and the healthcare guide cover both halves.

Kogarah station and the St George hospital precinct

Kogarah station sits between Rockdale and Carlton stations, a short walk from St George Hospital on Gray Street. For a buyer on rostered shifts, being able to walk to both can be a large part of the appeal of the apartments near the station.

Lender policy does not change with that walk, but the valuation evidence does: a valuer looks for sales of comparable units within the same station and hospital catchment, and a rental appraisal for an investor should reflect that same position.

  • Apartments are the majority of Kogarah’s homes, with established houses on the streets behind them.
  • For a Kogarah buyer on hospital rosters, Links sets ANZ, Westpac, Macquarie, ING and Resimac, among other lenders, side by side on how they count penalties and overtime, as well as how they view the building.
Read the full detail

Apartments are the majority of Kogarah’s homes, with established houses on the streets behind them. For a unit, the file turns on internal size, the strata record and how exposed the lender already is to that building.

For a house, it turns on condition, past approvals and the valuation. Either way, the income side of a precinct worker’s file often matters as much as the property.

For a Kogarah buyer on hospital rosters, Links sets ANZ, Westpac, Macquarie, ING and Resimac, among other lenders, side by side on how they count penalties and overtime, as well as how they view the building.

Example scenario (illustrative, not a real client): a registered nurse on permanent rostered shifts at St George Hospital wants a one-bedroom unit near Kogarah station. Her current bank counts only part of her penalty income, which caps her price range, and the unit is small enough inside to rule out some lenders.

Comparing lender policies shows which options treat both the rostered income and the floor area more favourably, so she knows her real range before she makes an offer.


An aerial view of a Sydney suburb

The precinct advantage

Four things worth checking before assuming your bank's number is the number.

Read the full detail

First home buyers in Kogarah

Precinct incomes plus schemes that still reach the stock.

  • The 5% Deposit SchemeThe $1.5 million cap covers the Kogarah market comfortably. Five per cent down, no lender's insurance. Check eligibility.
  • Stamp duty reliefExemption to $800,000 and concession to $1 million across the unit market. Your figure.
  • Shift income, read rightThe difference between lenders on penalties and overtime is frequently worth more than any rate discount. How they differ.
  • Professional policiesWorth checking before saving toward twenty per cent, because a waiver may mean you never needed one.

Common questions about buying in Kogarah

I work at the hospital. Will my overtime count?

It depends entirely on the lender, and the spread is wide. Some count a conservative percentage of a two-year average; others count rostered award penalties at close to full value where your employment is permanent.

On payslips where variable income is a large share of the total, that difference frequently decides the suburb you can buy in.

Do I need a car space in a unit near Kogarah station?

Not as a rule, but it can change who will fund the purchase. Some lenders read a unit without parking more cautiously, and the valuer compares it with similar units nearby rather than with ones that include a space.

Being a short walk from Kogarah station and St George Hospital does not change that policy, although it is part of what buyers weigh. If the unit has no space, or one on a separate title, settle the lender choice before you offer.

Do healthcare workers get professional lending benefits?

At some lenders, yes. Concessions can include borrowing at a higher loan-to-value ratio with reduced or waived mortgage insurance. Which occupations qualify, and on what terms, differs between lenders and changes over time, so it is confirmed against current policy rather than assumed from a colleague's experience.

I am a registrar on a training contract. Does that count against me?

Not with the right lender. Fixed-term and training roles are read differently across the market, and continuity in the same field carries real weight at lenders whose policy accommodates it. It is a placement question rather than a problem with your file.

What evidence should I gather before applying?

Two years of payslips and both PAYG summaries, plus an employment letter that describes the roster and the permanency accurately. A letter that calls overtime 'available' reads very differently from one that describes rostered penalties as part of the role.

Is Kogarah worth considering as an investment?

It can be: hospital and rail proximity underwrite steady tenant demand, and entry prices sit below much of the inner south, though lenders assess rent conservatively. Settle the investment structure before contracts rather than after.

Talk to a broker about your Kogarah home loan

Bring your Kogarah plans to a free 30-minute call: your borrowing range, the lenders that fit the property and your next step.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · All areas

General information only, not credit or financial advice. Property types and lender policies differ and change over time; your position is confirmed in a full assessment. Links Property Finance works across Sydney and Australia-wide.

Official sources for the figures on this page: Housing Australia, 5% Deposit Scheme · Revenue NSW, First Home Buyers Assistance Scheme. Scheme rules change; the official pages are the final word. Checked against these sources on 12 October 2026.