Call Charles Book a meeting
Mortgage Broker Canterbury

Links Property Finance · Home loans in Canterbury and across Sydney: Mortgage Broker in Canterbury

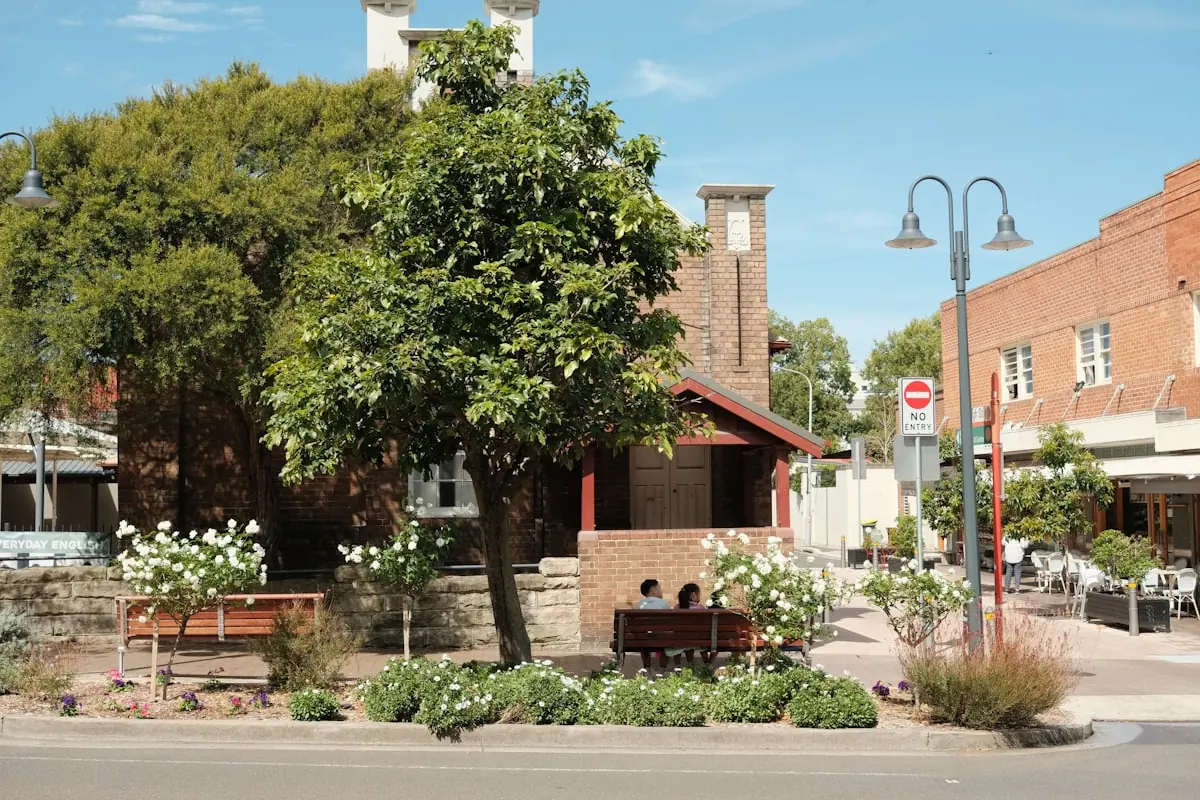
Six in ten Canterbury homes are apartments and nearly half are rented, many of them in newer buildings along Canterbury Road and nearby streets.

Reviewed by Charles Touma Updated 18 October 2026

$0broker fee on most loans
5.0from 32 Google reviews
70+lenders on our panel
Charles Touma, mortgage broker at Links Property Finance

Charles Touma Sydney mortgage brokerYou deal directly with Charles.

Book a free call

Buying a Canterbury apartment to rent out: how do lenders count the rent?

At around 80 per cent of the expected rent, from a rental appraisal or lease, to allow for vacancy and costs. That shaded rent plus your income sets the borrowing figure.

Read more

In newer Canterbury Road buildings, lenders also look at their limit in the building, the unit’s size and how many units are investor-owned.

A terrace with an iron-lace balcony
Of Canterbury's homes, 29.3% are houses, 6.3% terraces and semis and 62.8% apartments (ABS Census 2021).

How a lender reads an address in Canterbury

Apartments are just over six in ten homes here (62.8%, against 21.7% statewide). Lenders measure internal living area, not the advertised size, so check the floor plan on the contract before the bank does. Just under half of the homes in Canterbury are rented, well above the state average. The suburb suits buyers weighing rentvesting: renting where you live and buying where the numbers work.

  • Postcode2193
  • CouncilCity of Canterbury-Bankstown
  • From the Sydney CBD11 km south west
62.8%

apartments NSW 21.7%

29.3%

separate houses NSW 65.6%

6.3%

terraces and semis NSW 11.7%

47.9%

rented NSW 32.6%

28.8%

with a mortgage NSW 32.5%

4,239

private dwellings

Source: ABS Census 2021, Suburbs and Localities (SAL10796).

Houses stepping down to Sydney Harbour

Run an investment loan on a Canterbury property

Will the rent cover it?

Will the rent cover it?

The first question every Sydney investor asks, repayments against rental income, the way a lender sees it.

$700,000
6.10%
$650
  • Repayments (P&I, 30 years)$4,242/mo
  • Rent a lender counts (~80%)$2,253/mo
  • Monthly gap to cover−$1,989

A gap isn’t a dealbreaker, negative gearing, interest-only periods and offset structure change the cash-flow picture. That’s the conversation.

Estimates only, rates, vacancy, costs and tax change the real picture. Not credit or tax advice.

Confirm your numbers.

Charles Touma, mortgage broker at Links Property Finance

Real outcomes for real borrowers.

★★★★★
Charles and the team recently assisted us with a refinance of our investment property. Recommend Charles and the team to all
Tony Google review
★★★★★
Charles Touma from Links Property Finance was a great help with buying my first home. I had plenty of questions and he took the time to explain things clearly without making me feel rushed. He kept me updated throughout and made the process much less stressful. Really appreciated his patience and would happily recommend him to other first home buyers.
Catherine Google review
★★★★★
Had a great experience with Charles. He made the home loan process straightforward, was always easy to communicate with, and really knew his stuff. Would definitely recommend Charles and the team!
Jacob Google review

Buying an investment apartment in Canterbury

When you buy to rent out, the lender counts the expected rent as income, but usually not all of it. A share is set aside for vacancies, management and costs, so only part of the rent adds to your borrowing power.

The lender also assesses the new loan at a buffer above the actual rate, alongside your existing debts and living expenses.

The rent estimate normally comes from the valuer or an appraisal from a local agent. With many similar apartments nearby it is usually straightforward to support, but it should be weighed against the levies, rates and insurance you will pay before you commit. Estimate the cost of owning

An aerial view of a Sydney suburb

Investors and apartments in Canterbury

A local shopping strip in Sydney
  • Links Property Finance is based in Enfield, a short drive north-west of Canterbury.Conversations run by phone and video, and the first one is about what the investment needs to achieve for you.
  • Six in ten Canterbury homes are apartments, compared with about one in five across New South Wales.A deep pool of similar apartments gives valuers plenty of comparable sales, which usually helps a valuation land predictably.

How rent is counted?

House keys beside a model home
  • Lenders usually count only part of the expected rent.The rest is set aside for vacancies and costs, so rental income adds less to borrowing power than the headline figure suggests.
  • The rent estimate needs support.It usually comes from the valuer or an agent’s appraisal and, for an established property, sometimes the current lease.

Canterbury Road, the Cooks River and Canterbury housing

Canterbury lies about ten and a half kilometres south-west of the city in the City of Canterbury-Bankstown. The former City of Canterbury took its name from the suburb, though its administrative centre was in neighbouring Campsie.

Canterbury Road runs through the suburb and is its only road crossing of the Cooks River, whose banks are lined with parkland, including Canterbury Park Racecourse and Tasker Park, with its pool and ice rink.

Interest-only or principal and interest?

Interest-only repayments keep the monthly cost lower for a set period, often up to five years for an investment loan, after which the loan reverts to principal and interest over the remaining term and the repayments rise.

Lenders assess whether you could afford those higher repayments, not just the interest-only ones.

Terrace houses along a tree-lined street

Buying new or established

A new apartment usually comes with a builder’s warranty period and lower early maintenance, while an established one has a strata history you can read and a rent you can check.

If you buy off the plan, the lender values it close to settlement, and that value can differ from the price you agreed years earlier.

First home concessions and investing first

The Australian Government 5% Deposit Scheme and the New South Wales first home buyer duty concessions are for buyers who will live in the property.

An investment purchase does not qualify, and buying one first can affect whether you qualify for first home buyer benefits later.

If a first home to live in is also on your list, check the current criteria before you buy an investment, so the order of purchases does not cost you a concession you would otherwise have had. First home buyer schemes in NSW.

A modern apartment building with balconies

Apartment, townhouse or house?

Three kinds of Canterbury investment, and what each means for the loan.

  • Apartment. The most common investment here. Levies, the strata report and the share of rented units in the building all deserve attention. Very small apartments can face tighter lender policy, so check the internal size.
  • Townhouse. Often strata or community title, with lower levies than a large apartment building. Check what the levies cover and whether the scheme has major works ahead.
  • House. Usually on its own title, with no levies but more maintenance for you as the owner. A house generally needs a larger deposit here, and the loan is assessed the same way.

What should I check before buying an investment in Canterbury?

The groundwork that keeps an investment loan straightforward.

  • A rent estimateGet an agent’s appraisal early so the numbers are realistic.
  • The full cost of holdingLevies, council rates, water, insurance, management fees and repairs, not just the loan.
  • A cash bufferAllow for vacancies and repairs, and for repayments rising after any interest-only period.
  • The strata reportCheck levies, defects, planned works and the capital works fund.
  • Tax adviceAsk your accountant how the purchase affects your tax before you commit.
  • Your first home plansCheck how buying an investment first could affect first home concessions later.

Common questions about investing in Canterbury

How much of the rent does a lender count?

Usually not all of it: most lenders count a share of the expected rent and set the rest aside for vacancies and costs. The share varies by lender and makes a real difference to how much you can borrow for an investment.

Do I need a bigger deposit for an investment property?

Not always, but it often helps. Many lenders price investment loans more keenly at lower loan-to-value ratios, and lenders mortgage insurance usually applies above 80 per cent. A 20 per cent deposit plus buying costs is a common starting point for investors, though some lenders go higher.

Is interest-only a good idea for my first investment?

It depends on your plans. Interest-only lowers repayments for a set period, which can help cash flow, but the balance does not fall and repayments rise when the period ends.

Lenders assess whether you could afford the higher repayments later, so it is worth comparing both options over the full term.

Can I use equity in my home as the deposit?

Often, yes. A lender can release equity from your home, subject to its valuation and your borrowing capacity, and that money can fund the deposit and costs of the investment.

How the loans are structured matters, including whether the two properties are secured separately, so it pays to get that right from the start.

Can I buy an investment before my first home?

You can, but check how it affects first home benefits. The 5% Deposit Scheme and the New South Wales first home buyer duty concessions are for owner-occupiers, and owning any property first can change your eligibility later. Read the current criteria before you decide the order.

Does a new apartment affect the valuation?

It can. A valuer compares it with recent sales of similar apartments, and where there are many new buildings, resale prices can differ from original off-the-plan prices. For an off-the-plan purchase, the valuation happens close to settlement, so the loan is based on the value at that time.

Talk to a broker about your Canterbury home loan

One free call covers what you could borrow in Canterbury, the lenders that suit the property you want and the order to do things in.

Prefer a callback?

Charles Touma, mortgage broker at Links Property FinanceCharles calls back within one business day. No documents needed yet.

A family in front of the sold sign at the home they bought together
Charles Touma, mortgage broker at Links Property Finance
Reviewed by Charles Touma Director & Mortgage Broker · MFAA member · Credit Representative 579003 under ACL 389328 About Charles · MFAA register · ASIC register · Complaints processEvery page is reviewed by Charles before it is published and checked against current lender policy and the official scheme pages linked where figures appear.

General information only, not credit or financial advice. Lender policies and government scheme criteria differ and change over time. All lending is subject to individual assessment and approval.